2024 February, Market Outlook: Navigating Central Bank Strategies and Growth Opportunities in Asia
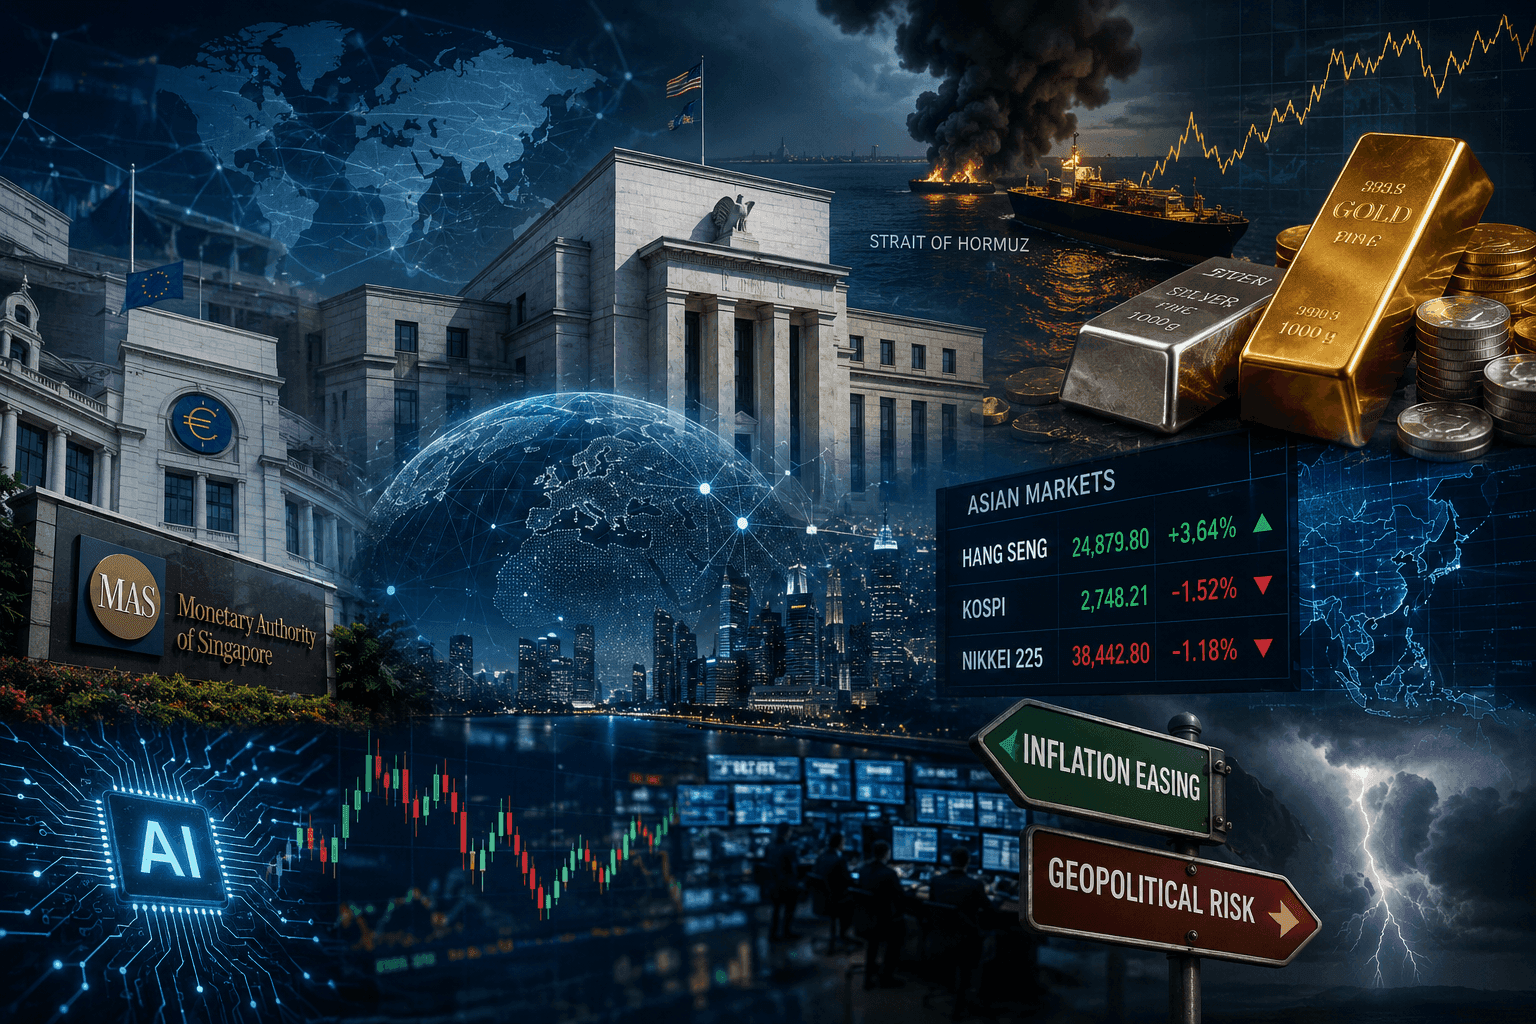
As we step into 2024, initial hopes for early interest rate cuts by the US Federal Reserve (FED) and the European Central Bank (ECB) are fading. Both central banks have downplayed the likelihood of reducing rates anytime soon, largely due to strong economic data released in recent months. The US economy continues to display resilience, with sustained expansion indicating that the FED must tread carefully. Lowering interest rates too soon could risk reigniting inflation, which the central bank is keen to avoid. At the same time, there are pockets of weakening growth within the economy, signaling the potential for a broader slowdown. This delicate balancing act places the FED in a challenging position, where policy mistakes could have significant consequences for both the US economy and global financial markets.
In line with our earlier expectations, the Eurozone also faces similar inflationary pressures, with energy prices remaining persistently high. As a result, inflation remains sticky, preventing the ECB from easing rates. We foresee that both central banks will need to remain vigilant in navigating the complex dynamics of their respective economies, weighing inflation risks against the threat of economic slowdowns.
Meanwhile, China's approach to monetary policy has taken a markedly different turn. The Chinese government recently lowered the 5-year loan prime rate by 25 basis points to 3.95%, signaling its determination to stimulate the economy and support the real estate sector. Under the “whitelist” initiative, commercial banks are encouraged to provide lending to property projects approved by local governments. These rapid, proactive measures underscore the government's commitment to front-loading stimulus to prevent weak sentiment in the housing market from deepening. We believe these policies will continue to evolve progressively, ensuring that the real estate sector stabilizes and recovers on a sustainable path.
Signs of improvement are already emerging in China’s economy. Recent data on monetary aggregates indicate positive movement, and domestic travel and spending during the Lunar New Year suggest a rebound in consumer activity. On the global stage, China’s exports have grown for the second consecutive month in December 2023, further reinforcing the positive outlook for 2024. These rapid policy moves come as the State Council calls for "forceful measures" to restore confidence in both the economy and financial markets.
Japan is also showing signs of strength, with the economy benefiting from long-anticipated corporate reforms. After decades of deflation, Japan appears to be breaking free from this prolonged economic phase. Reforms aimed at improving corporate profit margins and shareholder returns are finally coming to fruition, marking the end of the country's 30-year deflationary struggle. We believe these developments will unlock significant value for shareholders, creating opportunities for growth in the Japanese market.
In summary, we remain optimistic about the prospects for the Asian markets, particularly as China and Japan implement aggressive economic measures. Conversely, we approach the US markets with caution, given the headwinds presented by inflationary pressures and an overconcentration in the technology sector. As we move forward, the balancing act between growth, inflation, and central bank policy will continue to shape the global market landscape, with Asia emerging as a bright spot for investors in 2024.