

Insights
Explore the latest news, expert articles, and market outlooks to stay ahead of industry trends.
Newsroom
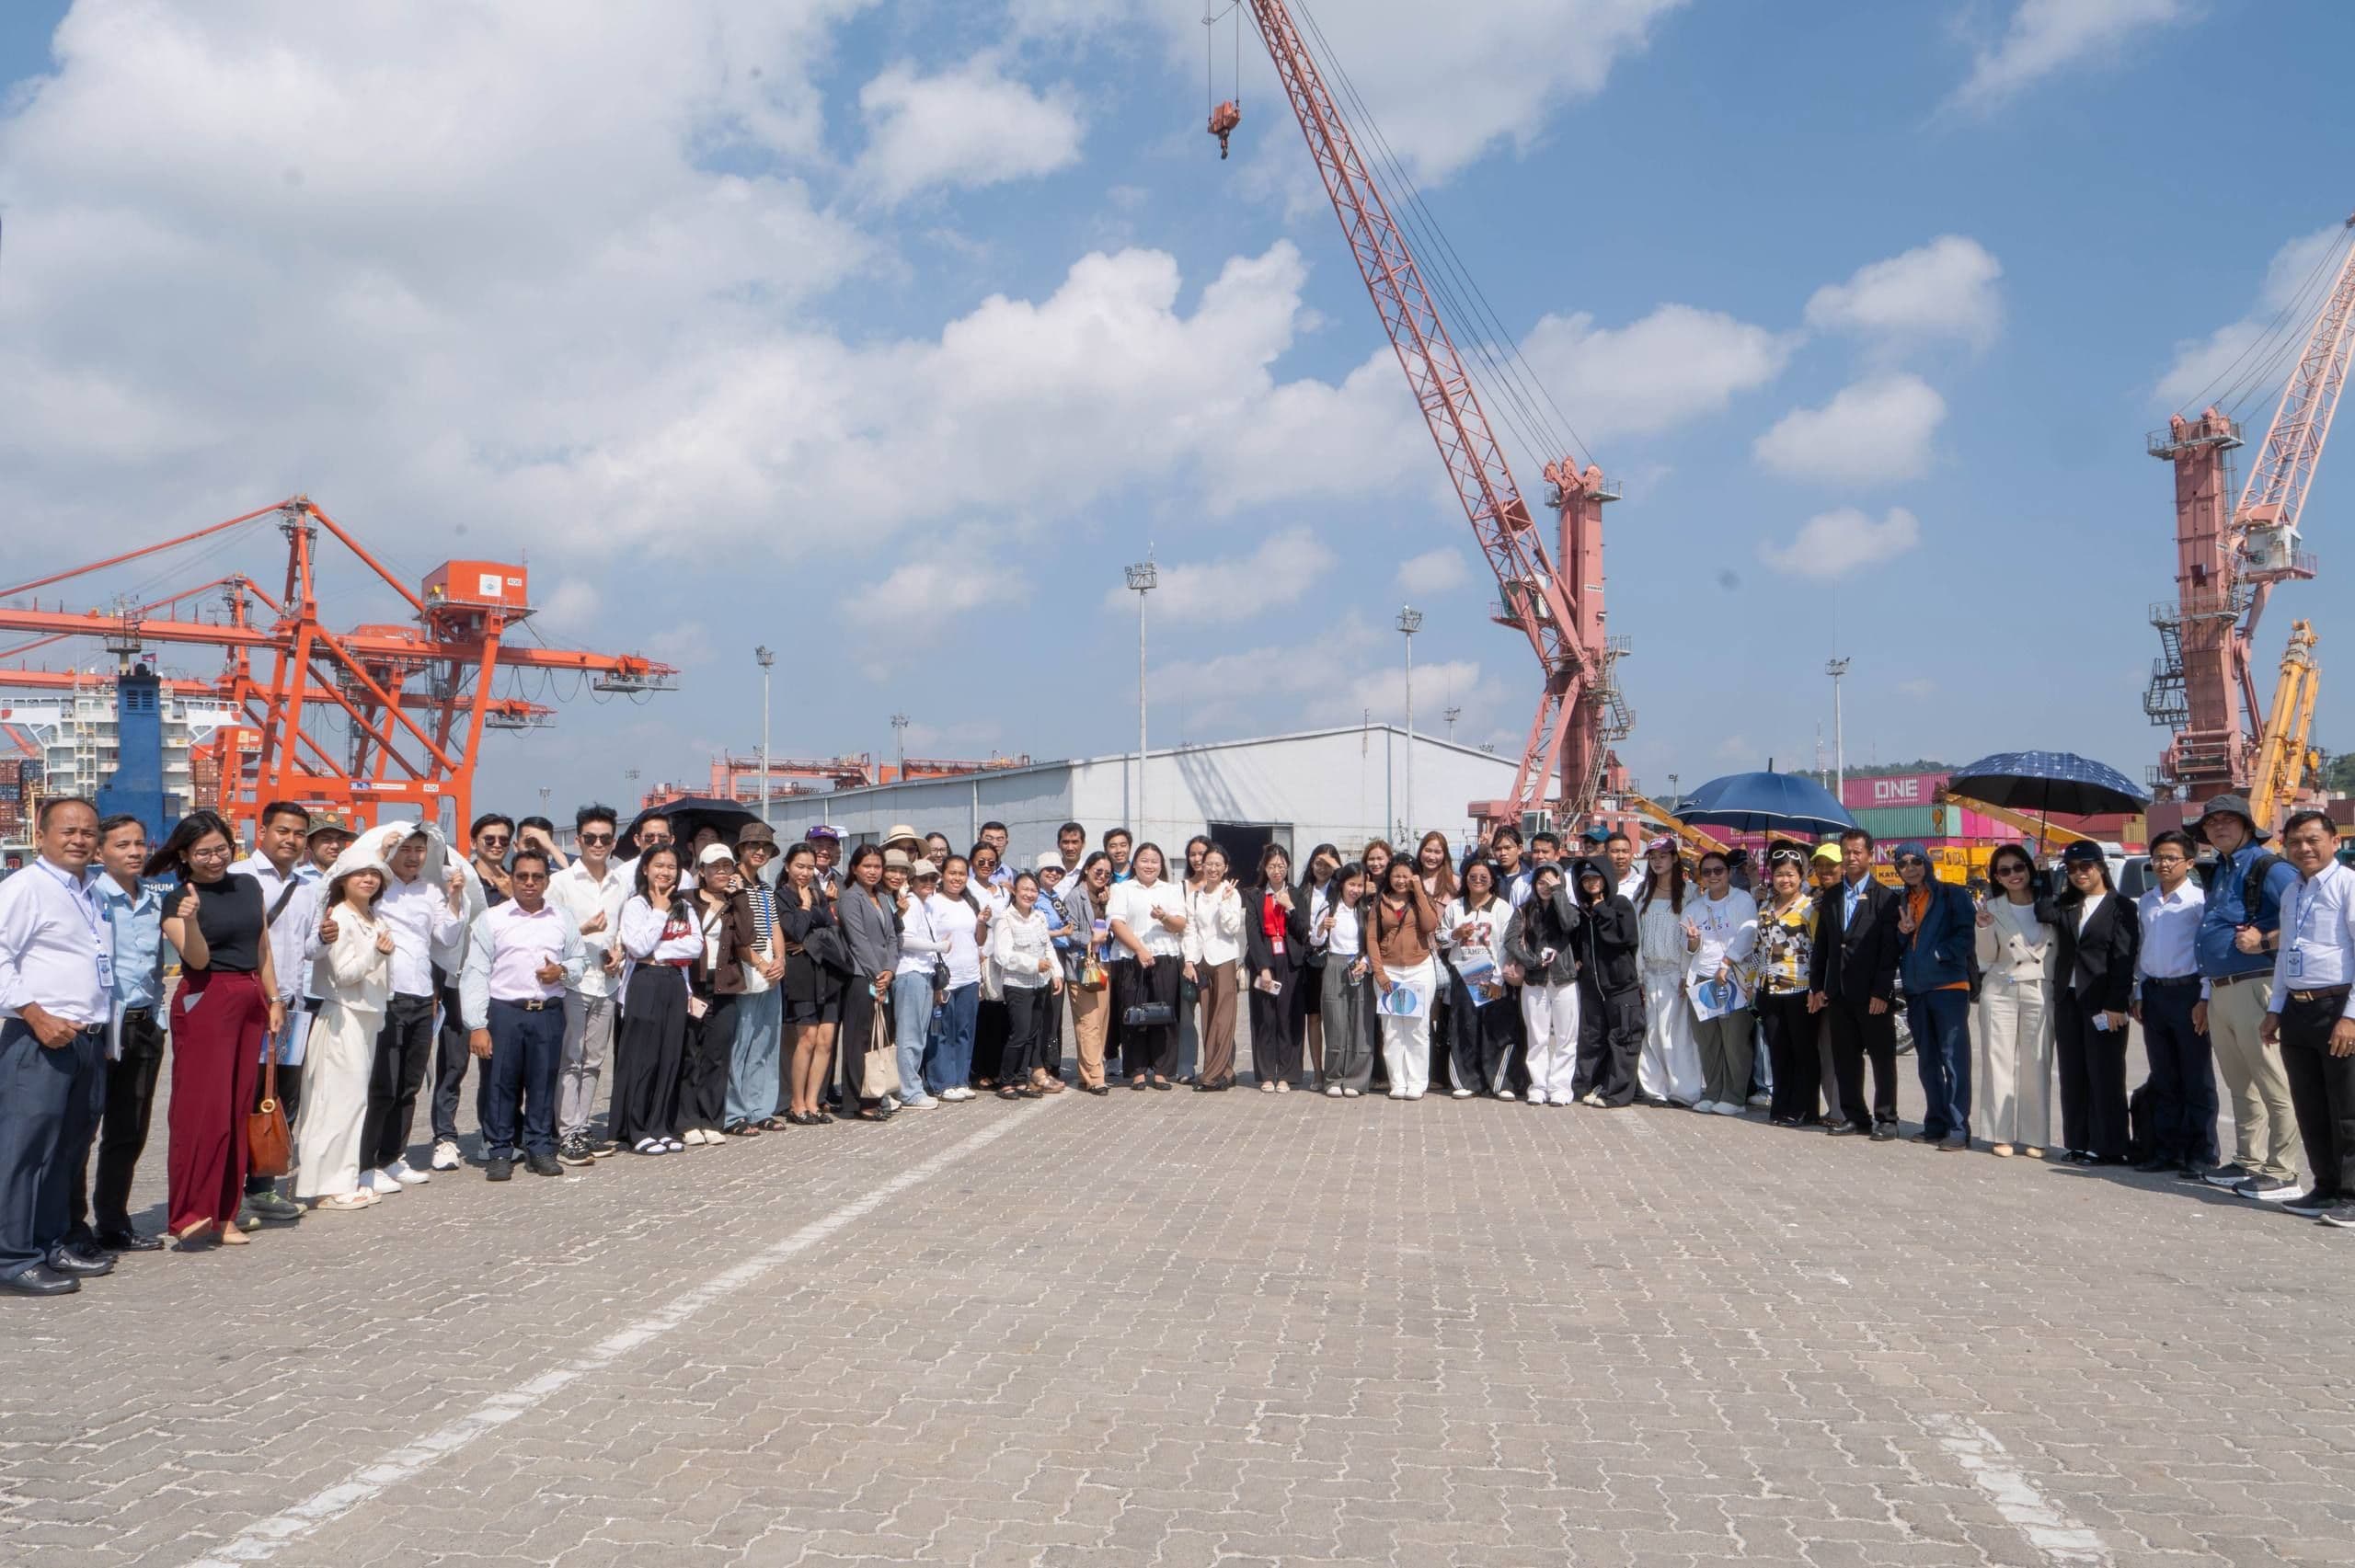
Potential of Sihanoukville Autonomous Port and Site Visit
Banjaran Asset Management (Cambodia) Plc. was honored to participate in the Listed Companies Forum on the topic: Potential of Sihanoukville Autonomous Port and Site Visit, organized by Cambodia Securities Exchange (CSX) on 06 April 2026. The forum, held at Sihanoukville Autonomous Port (PAS), was under the high presidency of H.E. Lou Kim Chhun, Delegate of the Royal Government of Cambodia in charge as Chairman & CEO of the Cambodia Securities Exchange (CSX), and H.E. Hong Sokhour, Delegate of the Royal Government in charge as CEO of the Cambodia Securities Exchange (CSX), highlighting the potential and business operations of the port. Our representatives, Mrs. Edeza Banquilis, Head of Growth & Strategy, and Mr. Sok Chantola, Deputy Sales & Marketing Manager, attended the event. The session and site visit provided valuable perspectives on Cambodia’s capital market growth and port development.
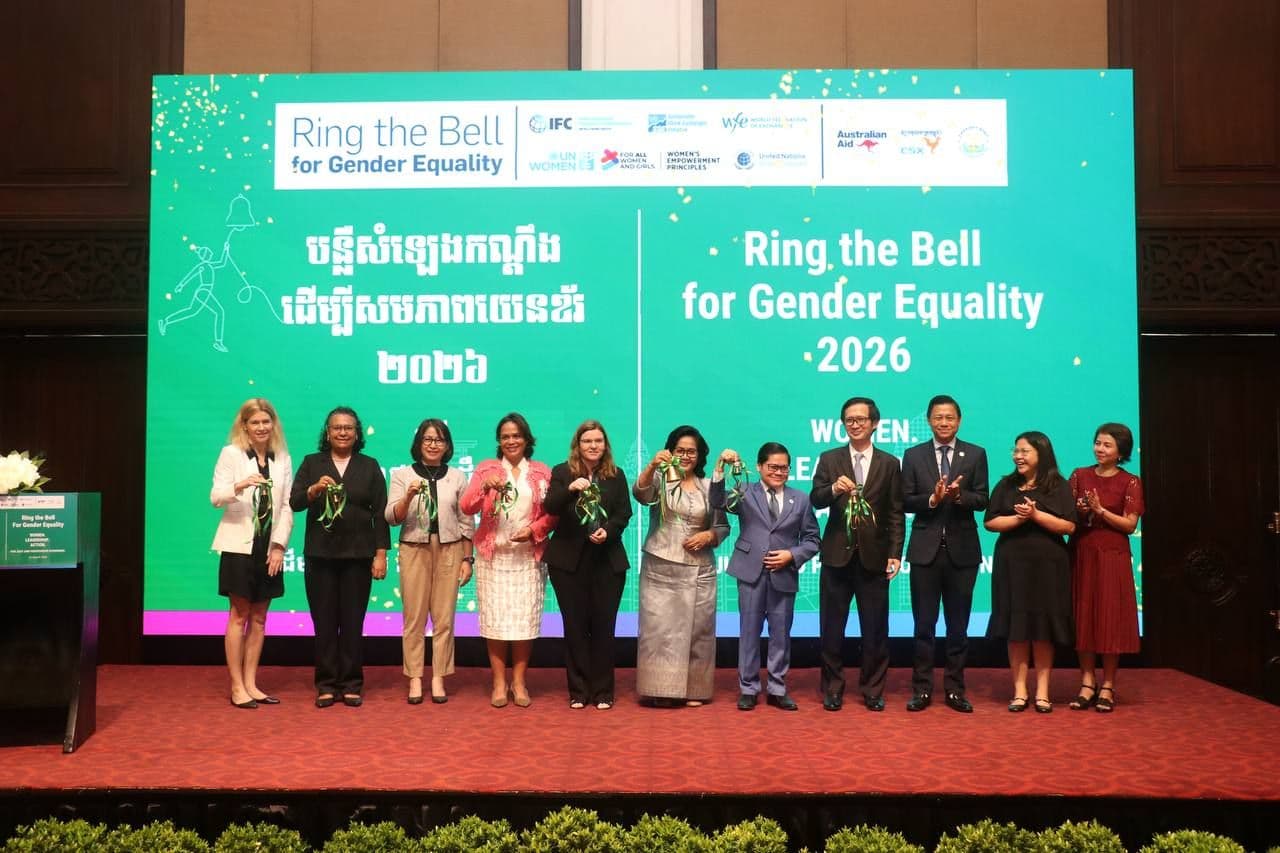
Ring the Bell for Gender Equality 2026
On 31 March 2026, Banjaran Asset Management (Cambodia) Plc. was honored to participate in the “Ring the Bell for Gender Equality 2026” event held at Sofitel Phnom Penh Phokeethra. The event featured the official Ring the Bell Ceremony, keynote sessions on women’s leadership in capital markets, and the launch of the Securities and Exchange Regulator of Cambodia (SERC). Scoping Survey on Gender-Responsive Finance and Sustainable Bonds. Our representative, Mrs. Nget Synat, Deputy Finance Manager, attended the session, gaining valuable insights and engaging in meaningful networking with industry professionals.
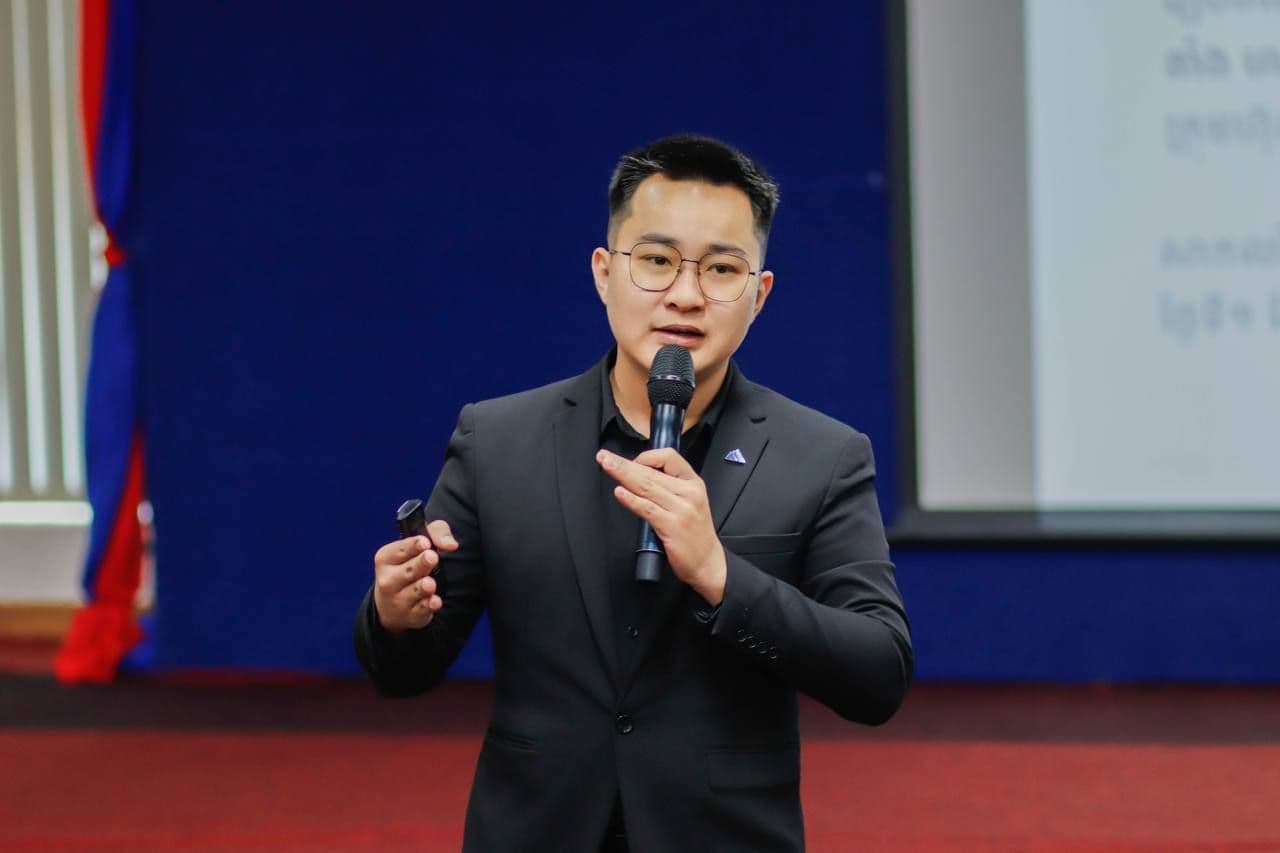
Training Program at ACLEDA University of Business
Banjaran Asset Management (Cambodia) Plc. was honored to participate in the recent “Smart Investing” training program held at ACLEDA University of Business on 1st April 2026. The event was organized by ACLEDA Securities Plc. in collaboration with the ACLEDA University of Business and was presided over by H.E. Sou Socheat, Delegate of the Royal Government in charge as Director General of the Securities and Exchange Regulator of Cambodia (SERC). During the session, Mr. Eric Loo, CEO and Executive Director, along with the team was present in supporting the financial literacy initiatives for the next generation. A key highlight featured by Mr. Taing Hoy, Legal and Compliance Officer, who delivered a comprehensive presentation on “Investment in Collective Investment Scheme (CIS)”, providing students with essential insights into financial planning and capital market opportunities.
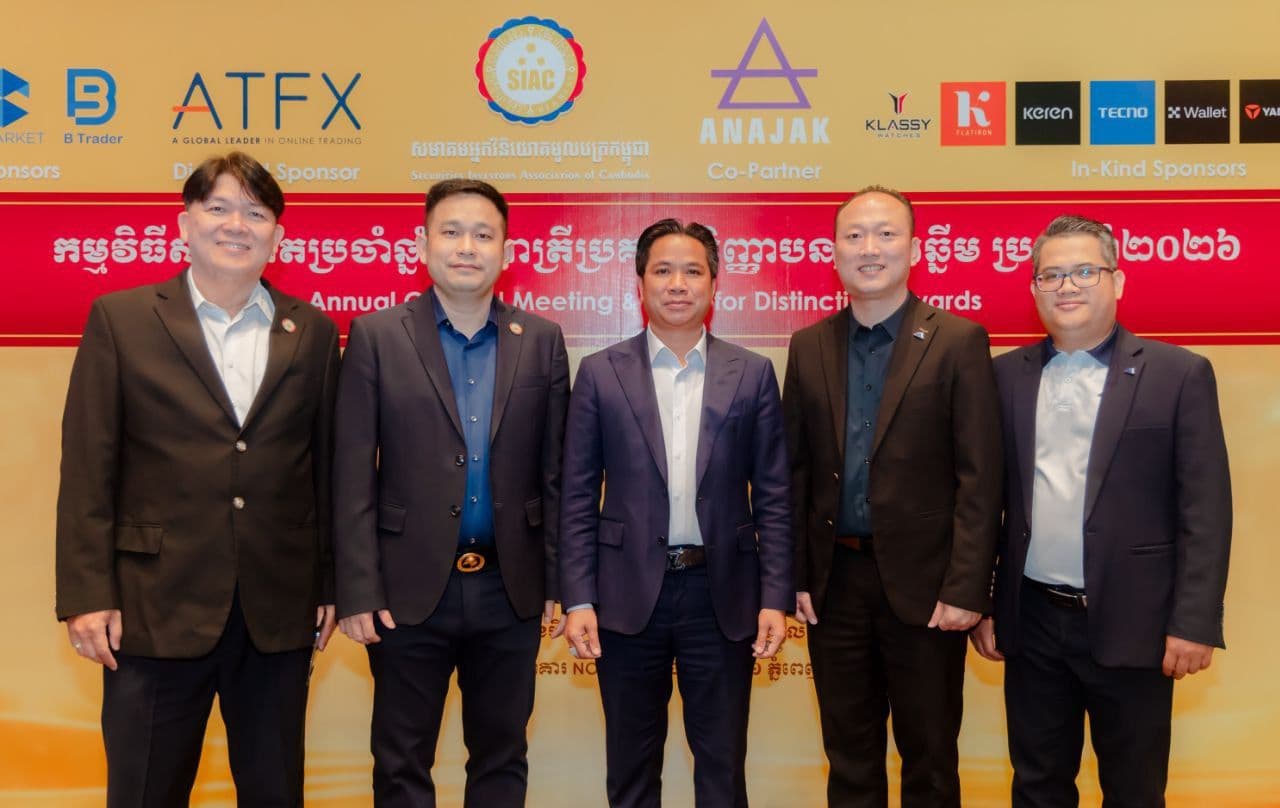
Annual General Meeting and Gala for Distinction Awards of Securities Investors Association of Cambodia (SIAC)
On 6 March 2026, Mr. Eric Loo, Chief Executive Officer, and Mr. Nhem Sopaul, Corporate Manager of Banjaran Asset Management (Cambodia) Plc., had the honor of attending the “Annual General Meeting and Gala for Distinction Awards of Securities Investors Association of Cambodia (SIAC),” held at the NOVOTEL Hotel. The event was presided over by H.E. Sou Socheat, Delegate of the Royal Government in charge as Director General of the Securities and Exchange Regulator of Cambodia (SERC) and Honorary President of SIAC. The event was also attended by Management and Senior Officials of SERC, the President of SIAC, presidents or representatives of relevant associations in the securities sector, presidents or founders of companies in the securities industry, representatives of the Cambodia Securities Exchange, and representatives of other related securities companies. During this distinguished event, Banjaran Asset Management (Cambodia) Plc. was honored to receive an Certificate of Distinction from SIAC, presented under the presidency of H.E. Sou Socheat, Delegate of the Royal Government in charge as Director General of SERC and Honorary President of SIAC.
Workshop on "Smart Investment" at National Institute of Social Affairs
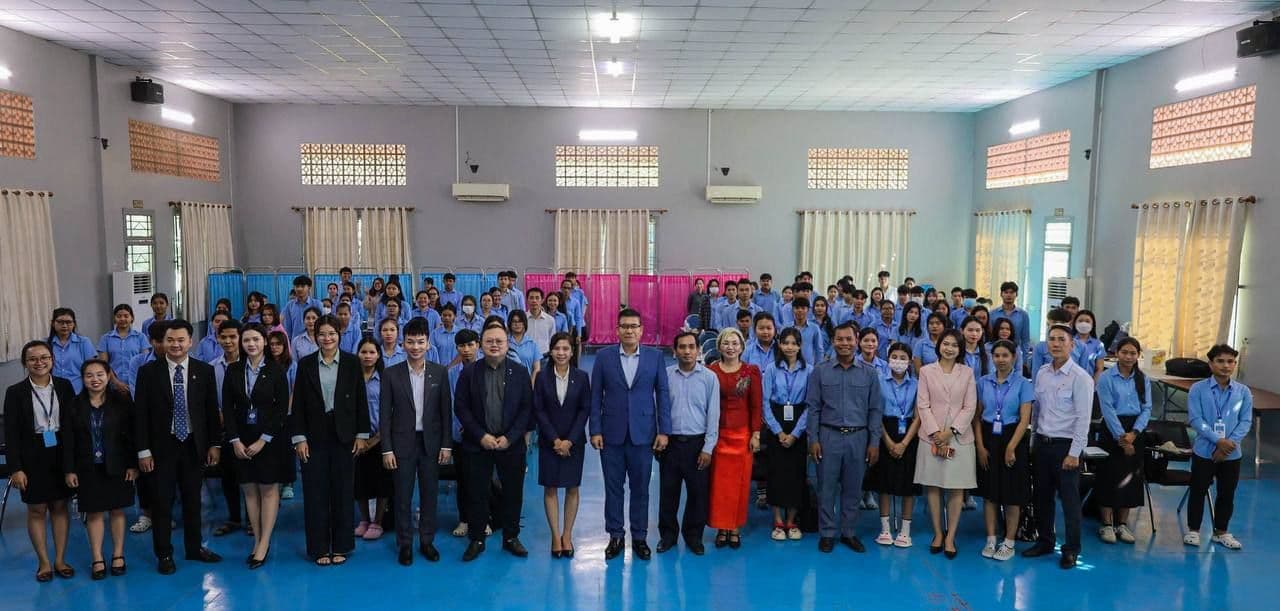
On 10th of March 2026, representatives from Banjaran Asset Management (Cambodia) Plc. participated in a workshop on "Smart Investment" Organized by ACLEDA Securities Plc., in collaboration with the Securities and Exchange Regulator of Cambodia (SERC) held at the National Institute of Social Affairs. During the session, Mr. Sok Chantola, Deputy Sales & Marketing Manager, delivered key details presentation on “Investment in Collective Investment Scheme (CIS)”. Sharing insights on investment opportunities and financial planning to future generation.
Cambodia-ASEAN Business Summit 2026 (Part 2)
4th March 2026, the Cambodia-ASEAN Business Summit 2026 was successfully held, under the theme “Transforming ASEAN: Innovation, Integration and Industrial Evolution.” The summit was presided over by The Prime Minister of the Kingdom of Cambodia, Samdech Moha Borvor Thipadei Hun Manet, at Sofitel Phnom Penh Phokeethra. Co-organized by the Cambodia Chamber of Commerce , ASEAN Business Advisory Council Cambodia , and International Chambers and Business Associations in Cambodia , the summit brought together government leaders, policymakers, business executives and thought leaders from across ASEAN, representing diverse industries and sectors, to strengthen regional collaboration and further encourage foreign investors to explore investment opportunities in Cambodia. Banjaran Asset Management (Cambodia) Plc. was honored to participate in the summit, with CEO, Mr. Eric Loo, and Mr. Mok Chinly, Legal and Compliance Manager, as well as, Legal and Compliance Officer, Mr. Taing Hoy, in attendance. Their presence reflects Banjaran AMC’s continued commitment to supporting Cambodia’s financial ecosystem and engaging with regional leaders to explore opportunities that contribute to the Kingdom’s growing investment landscape within ASEAN.
Cambodia-ASEAN Business Summit 2026
Banjaran Asset Management (Cambodia) Plc. was honored to participate in the Cambodia-ASEAN Business summit 2026, with CEO, Mr. Eric Loo, and Mr. Mok Chinly, Legal and Compliance Manager, as well as, Legal and Compliance Officer, Mr. Taing Hoy, in attendance. Their presence reflects Banjaran AMC’s continued commitment to supporting Cambodia’s financial ecosystem and engaging with regional leaders to explore opportunities that contribute to the Kingdom’s growing investment landscape within ASEAN, held at Sofitel Phnom Penh Phokeethra on 4th March 2026. Throughout the summit presided over by The Prime Minister of the Kingdom of Cambodia, Samdech Moha Borvor Thipadei Hun Manet, the team had the opportunity to network with high-level government officials, policymakers, and key industry leaders, exchanging insights on regional integration, innovation-driven growth, and ASEAN’s evolving investment landscape. The summit served as a valuable platform for dialogue and collaboration, further reinforcing Cambodia’s role as a growing country for investment and innovation in the region.
Strengthening Professional Education in Cambodia: A Landmark MOU Signing Ceremony
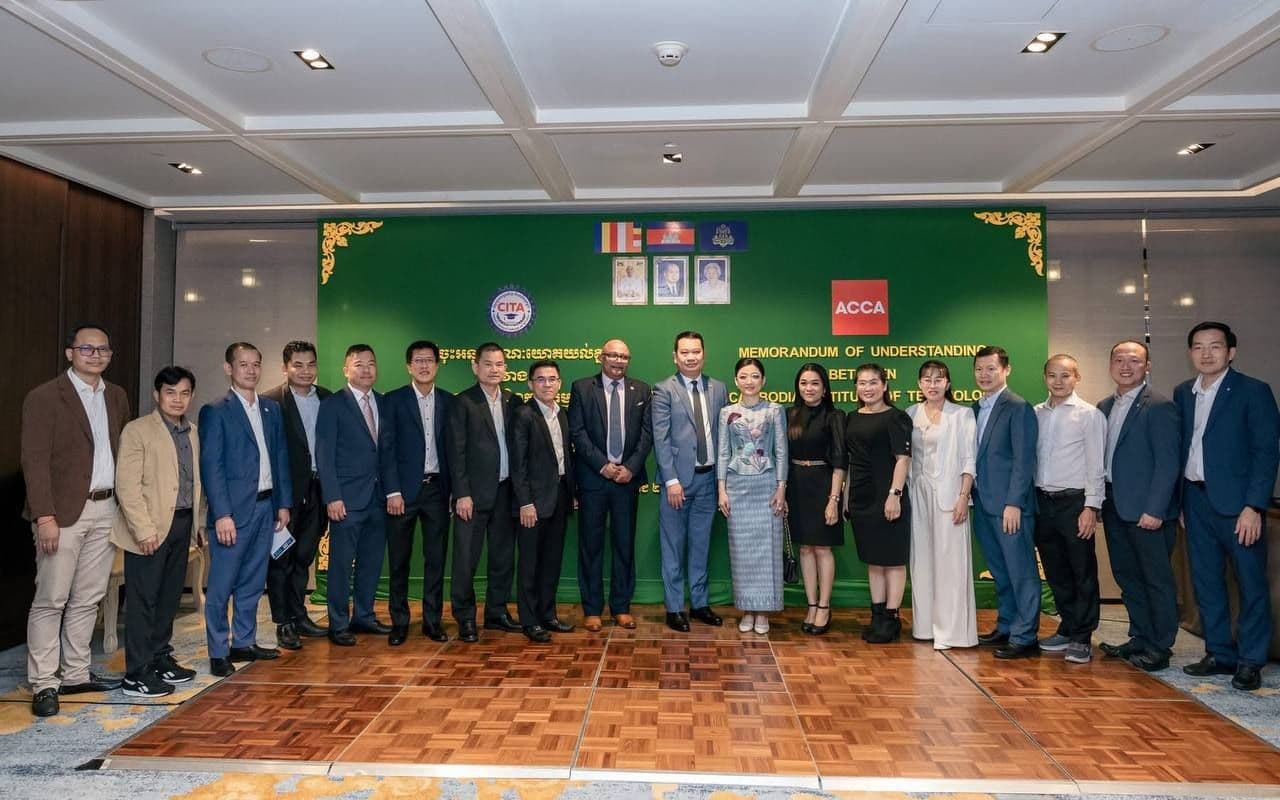
On 24th February 2026, we are honored to have witnessed a landmark moment for professional education in Cambodia! Our CEO, Mr. Eric Loo and Head of Growth & Strategy, Mrs. Edeza Banquilis, attended the official MOU signing ceremony between the Cambodia Institute of Technology and Agriculture (CITA), Business School of Accountancy (BSA) , and Association of Chartered Certified Accountants (ACCA) . The ceremony was a high-profile success, graced by H.E. Chea Kosal, Secretary of State and High Representative of H.E. Heng Sour, Minister of Labour and Vocational Training. At Banjaran AMC, we are proud to support initiatives that foster talent and drive sustainable economic development across the region.
Let’s Talk Investment! Topic on: Collective Investment Scheme (CIS)
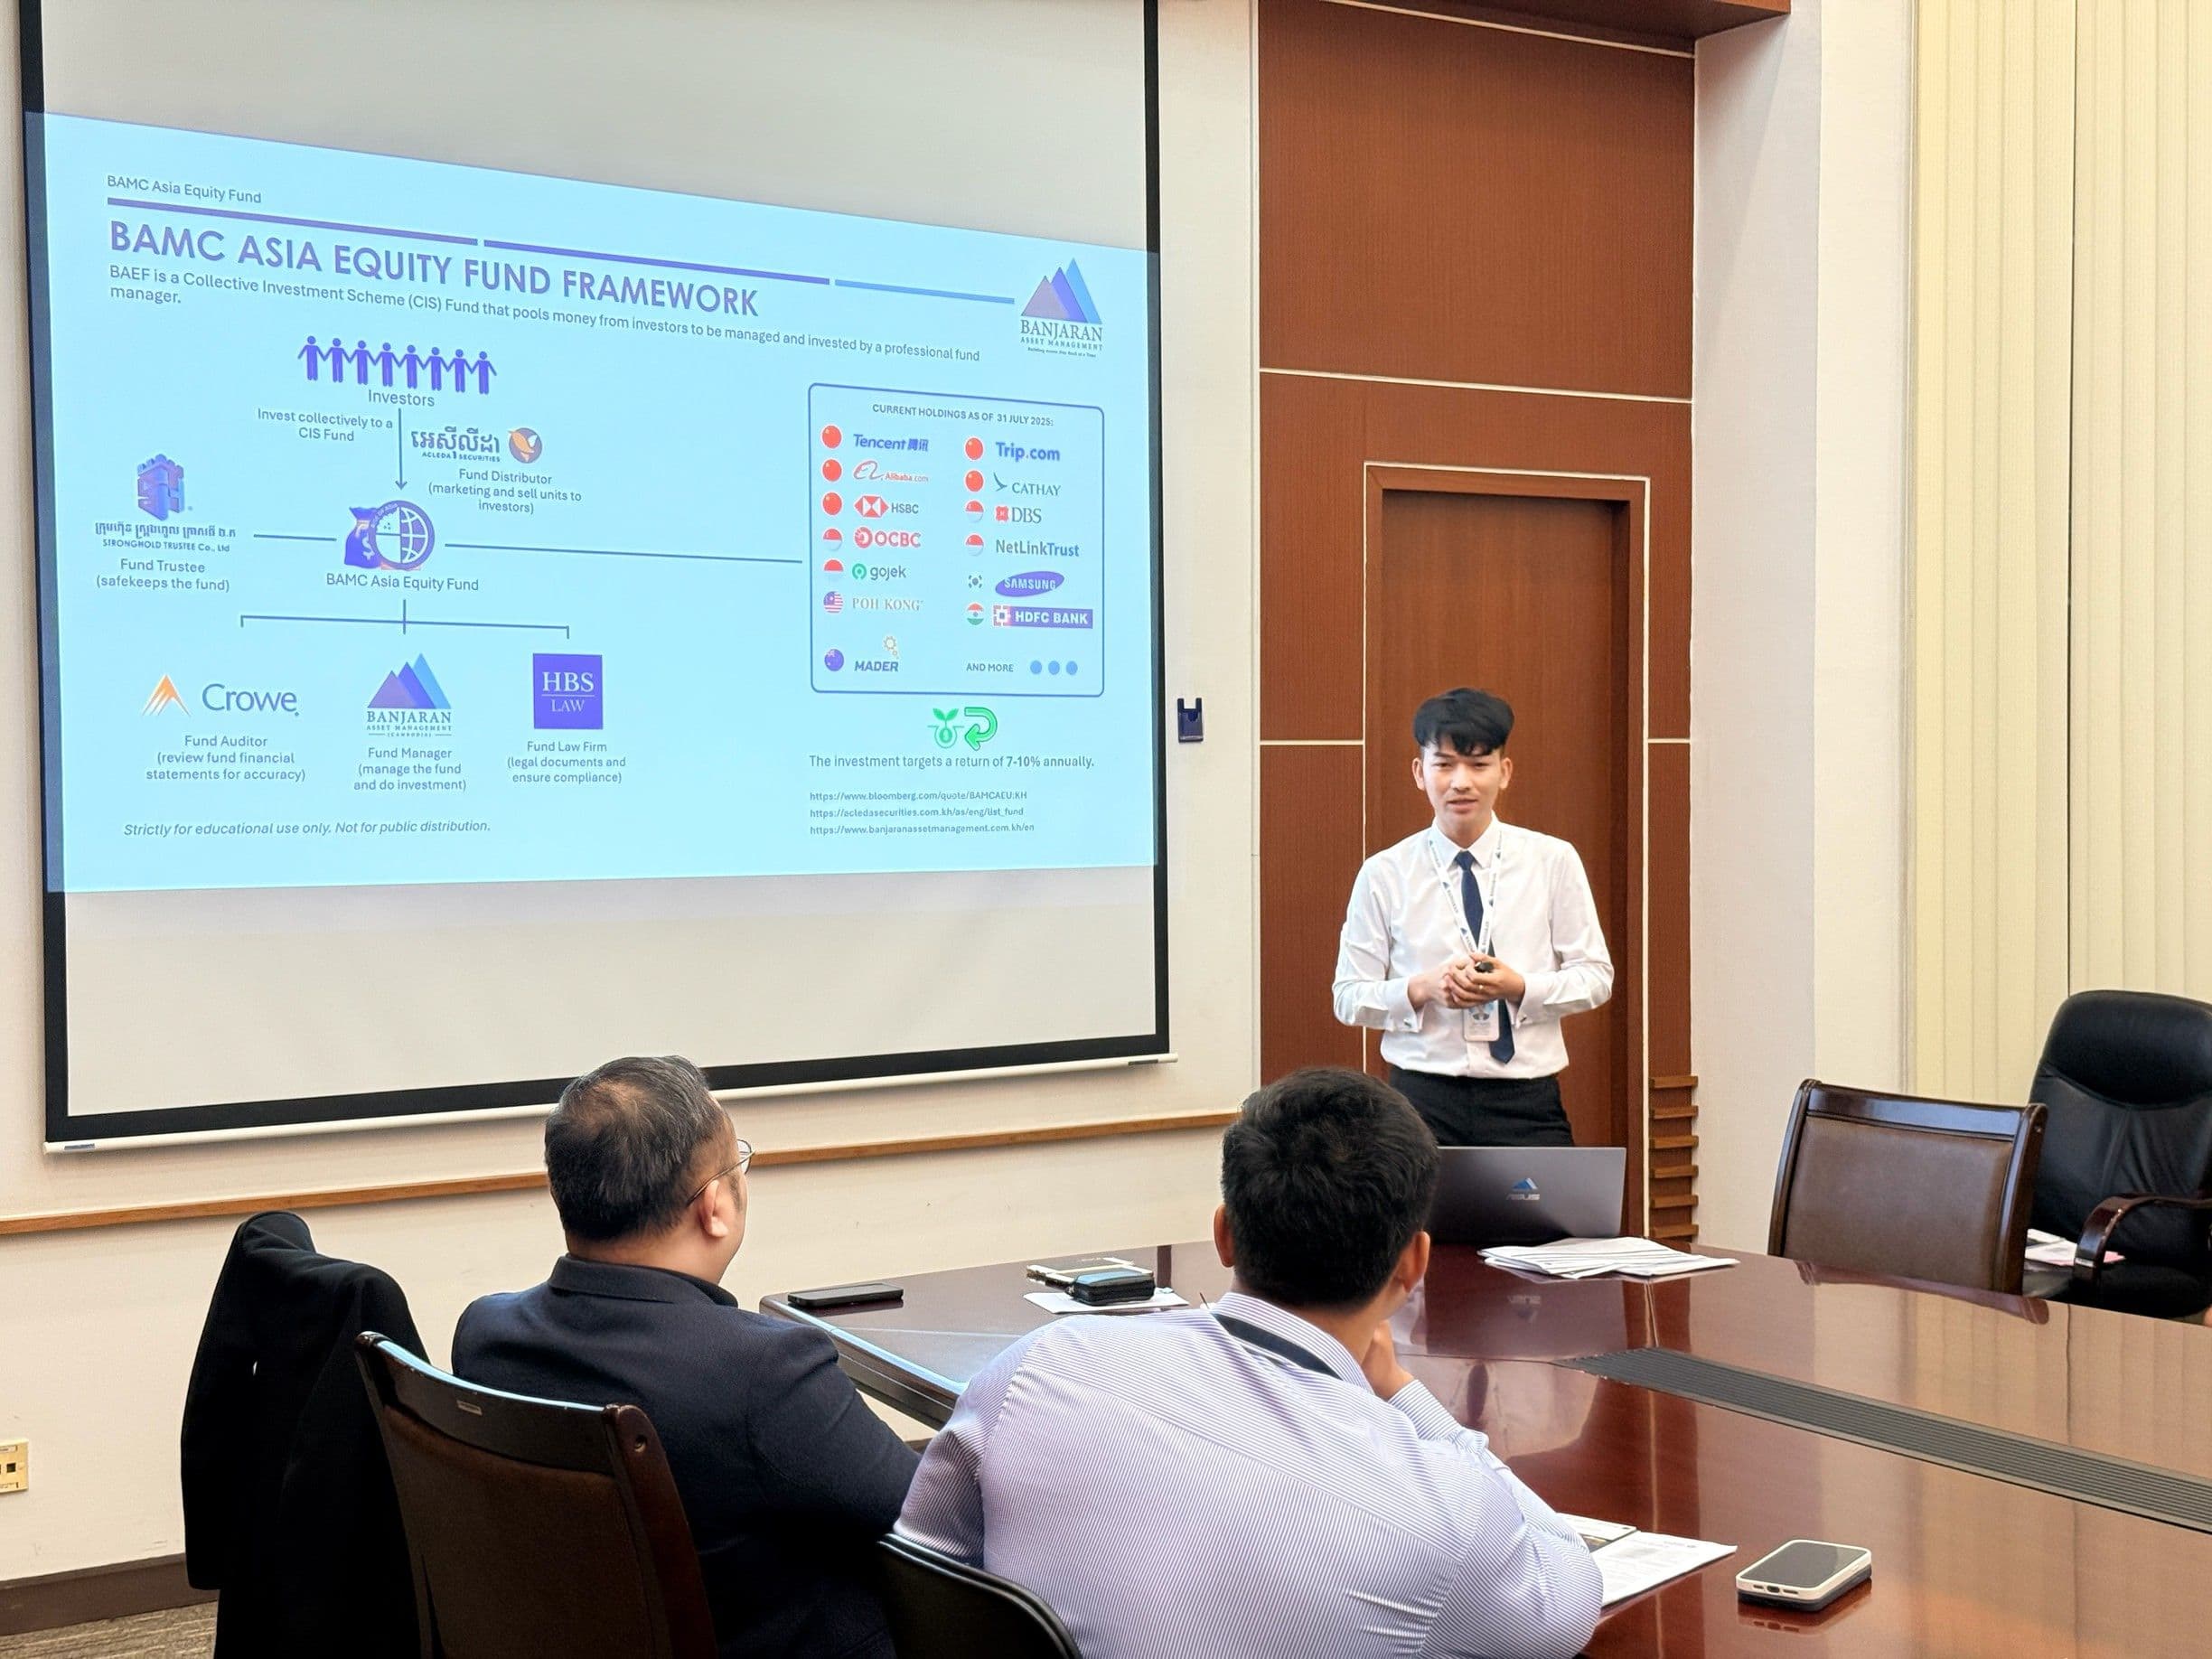
Thank you to everyone who joined us today for this session on 16th January 2026 at ACLEDA Securities Plc., centered on building a clearer understanding of Collective Investment Schemes and their role in long-term investing. We truly appreciate the participants for the opportunity to share practical investment insights and contribute to building greater financial confidence within the Cambodian market. We look forward to continuing this learning journey together in the future!
Market Outlook
2026 February Market Outlook: From U.S. Policy Turmoil to Mixed Signals Across Asia
The geopolitical scene in the US has been uncertain and volatile. The January jobs report exceeded expectations, though employment gains were largely concentrated in the healthcare sector. Kevin Warsh, known for his hawkish stance, has been nominated as the next Federal Reserve Chair, though this remains to be confirmed by the Senate. In the past week, the Supreme Court has ruled against President Trump’s International Emergency Economic Powers Act (“IEEPA”) tariffs. In return, the Trump administration acted quickly to impose 10% global tariffs, and immediately raised to 15% that will remain effective for 150 days under a separate trade law. These developments have contributed to a weakening US dollar, which is further exacerbated by rising US-Iran military tensions. Gold extended its rally and reached new highs, while silver surrendered most of its gains. Investors remain cautious amid sharp swings in these traditional safe haven assets. In Asia, market performance has been mixed. Indonesia experienced its largest stock crash since 1998, whereas South Korea and Taiwan delivered strong returns. Markets have shown heightened sensitivity to the external macro environment, resulting in intermittent pullbacks. Most recently, Chinese stocks rose as IEEPA tariffs were removed as China is set to face lower duties on shipments to the US. The Shanghai Composite and Hang Seng indexes also experienced recent declines, as is expected due to thin trading volumes during the Lunar New Year holiday season. Overall sentiment towards Asian equity markets amid the uncertain global political climate remains positive. Against this backdrop, we continue to diversify across different markets and sectors while remaining selective to stock selection, particularly within the technology sector. We continue to maintain a disciplined, bottom-up approach in portfolio construction.
2026 January Market Outlook: A Month That Redirected Market Attention
The New Year began with subdued volatility, but the calm was subsequently shattered by geopolitical events, notably US’s desire to take over Greenland for its strategic Arctic Circle argument. Demand for gold and silver skyrocketed with prices hitting new fresh highs. However, these high precious metal prices can create a range of challenges for precious metal-dependent industries like solar panel makers and EV producers which use silver as part of their components in their production. This may further impact the profitability of the solar panel makers which are already facing an oversupply situation. Asian markets started the year mixed but with some positive moves. Several key themes are driving the markets, central amongst them is a strong Asian IPO pipeline especially in Hong Kong and India. Other country-specific themes that are driving the markets include the deployment of funds from the Equity Market Development Programme in Singapore. The Korean Kospi has exceeded their President’s target, with technology companies fueling the rally on accelerated semiconductor demand. China surprised with an export outperformance with a record 2025 trade surplus, plus resurgent interests in AI-related tech names. While in Japan, performance is mixed where there are concerns with the volatility and soaring yields in the Japanese Government Bonds market. In 2025, US technology stocks dominated investor attention for much of the year, later turning to precious metals commodities. This period also underscored the importance of diversification and currency exposure beyond the US. With growth now amplifying across global markets, moderate softening of the US dollar may act as a drag on returns from US assets. Against this backdrop, we retain our emphasis on broadening exposure to other markets and sectors while being mindful of our stock selection, particularly in the technology sector. We continue to maintain a disciplined, bottom-up fundamental approach in portfolio construction.
2025 December Market Outlook: Protecting Value as Risks Reprice.
The hawkish rate cut signaled the Fed’s caution, even as tariff-related inflation pressures appeared to be fading. November’s jobs report suggested a subdued consumer environment. Unemployment had risen to its highest level since 2021, and retail sales remained unchanged despite Black Friday sales. Though the Trump administration has softened its language on China, recent developments highlight the delicate truce in their trade war. The U.S. has restricted China’s access to technology, such as permitting limited Nvidia chip exports, and formed an international partnership to counter China’s rare earth dominance. Across Asia, the picture remains mixed. The weaker U.S. dollar alleviates pressure on currency weakness in countries like Indonesia, South Korea, India, and the Philippines. The Bank of Japan have responded to the Fed’s rate cut by raising interest rates by a quarter point in a widely expected decision. In China, the economy continues to be supported by sustained capital inflows and the boom in exports while pivoting away from dependence on U.S. consumers. This was in spite of the property sector slump, missed industrial production expectations, weak retail sales, and unchanging unemployment rates. Measures to drive consumption appear ineffective, and rising trade frictions with countries beyond the U.S are weighing on sentiment. Investors are increasingly watchful for signs of an AI-driven bubble, including circular financing risks inflating valuations, where such dynamics could unwind abruptly. Against this backdrop, investors face a strategic dilemma - rein in AI exposure ahead of a potential bubble popping, or double down to capitalize on game-changing technology breakthroughs. In response, we are positioning portfolios defensively and broadening exposure to other sectors. This includes increasing allocations to commodities such as silver and gold, which can serve as stores of value, and consumer staples, that tends to offer more resilient demand. We continue to maintain a disciplined, bottom-up fundamental approach in portfolio construction.
2025 November Market Outlook: AI Bubble Alert
Mega-cap chip making company Nvidia Corp (“Nvidia”) became the first company to hit $5 trillion market capitalisation, likely due to U.S. President Trump’s comments ahead of the trade talk with Chinese President Xi Jinping at the end of October. The talk resulted in a consensus on cooperation in expanding agricultural trade and pausing the rare-earths licensing regime for a year. Mid-November saw the conclusion of the record U.S. government shutdown, which lasted 43 days, and put an end to unpaid furlough and other government operations. Consequently, the October jobs report was cancelled due to insufficient data. The ambiguity around unemployment rates raised uncertainty about the state of the U.S. economy. Compounding concerns were exacerbated by growing anxieties about stretched valuations of an “AI bubble”, which led to a selloff towards the end of November. Similarly, the Asian equity market, primarily due to technology companies in the AI landscape, slumped after an initial rally in the previous month’s end. In the semiconductor space, South Korean company Samsung Electronics Co., Ltd. reported an 80% surge in profit and SK Hynix Inc. continued to lead in chip memory. In China, different industries continue to diverge as technology companies grow while consumption and property remain a drag. In response, China’s policymakers are evaluating various measures to support the housing market. The MSCI Emerging Markets Index fell sharply, and losses were led by the tech heavy Korean Kospi index where the aforementioned Korean companies posted steep declines. Looking ahead, we remain cautious of the volatility in the markets. Due to concerns about inflated valuations for technology companies, the pullback observed in late November may have been a profit taking move or a price correction. Investors remain watchful for indicators of the widely discussed AI bubble, and signals for a potential burst. Against this landscape, we maintain a disciplined and balanced approach, grounded in bottom-up fundamental analysis in our portfolio construction.
2025 October Market Outlook: Between Tariffs and Growth — Searching for Stability
Towards the end of September, in an effort to protect American jobs, the Trump administration made surprised changes to immigration visa laws that target foreign talent, particularly those working in the U.S. technology sector. Amongst the heaviest users of this targeted immigration visa scheme include Amazon.com Services LLC, Meta Platforms Inc, Apple Inc and Google LLC. Later that month, the U.S. Immigration Service issued guidance that included exceptions, thus stabilising concerns. However, the labour market outlook remains uncertain with the shutdown of the U.S. government, which began on October 1st. Consequently, data reports such as the official U.S. monthly jobs report and the labour-intensive Consumer Price Index report would likely be delayed amidst the impending mass firing and unpaid furlough of certain segments of federal workers. In China, September data showed low domestic demand, a continued property downturn and the weakest economic growth in a year. With the ongoing US-China trade war, Chinese regulators have urged against the use of Nvidia chips completely, stating that domestic chips are adequate in delivering comparable computing power. As such, Chinese domestic chipmakers have benefitted from efforts to become self-sufficient, and this move should serve as a catalyst to grow the technology sector. China tightened exports of rare earth where products that contain certain rare earths or traces of it sourced from China will now require an export license. With a 70% share of global supply, the supply crunch would be felt by the U.S. and Europe. In response, the U.S. imposed a 100% import surtax on Chinese goods effective November 1st, ahead of the 90-day tariff truce that was set to end on November 9th. Despite the trade war uncertainty, Chinese exports rebounded in September from a slump in August, beating estimates and increasing 8.3% year over year while imports grew 7.4%. The sweep of high tariffs from the U.S. have led China to seek imports from other avenues, such as Brazil and Argentina for soybean, which has caused farmers in the U.S. to scramble for buyers. On the other hand, aggressive price competition among manufacturers in China have led to what has been termed ‘Chinese dumping’, where low prices due to Chinese imports are alarming domestic producers in India, Africa and South-east Asia. Looking ahead, we remain cautiously optimistic of the global markets. In the U.S., businesses and households are concerned over trade tariffs, changes to immigration laws and the shutdown of the U.S. government. The structural imbalance in China represented by slow domestic growth and heavy reliance on export further weighs on global financial markets and investor confidence. Despite the uncertainty, there were reports of pockets of positive news. Alternative data in the U.S. such as restaurant bookings and theatre box office receipts reflects resilient consumer activity. The number of seated diners was up 9% from last year and domestic box office grossed 13% more than the previous month.
2025 September Market Outlook: Bullish Trends Meet a Cautious Reality
August began with higher reciprocal tariffs imposed by the U.S. on its trading partners. Notably, a 50% tariff on India that included a 25% penalty for purchasing Russian oil and weapons. Meanwhile, the U.S. and China extended a tariff truce for another 90 days to 10 November. Credit spreads narrowed further in August, indicating continued high investor risk appetite. Equity markets broadly advanced, reinforcing bullish sentiment amid strong earnings from technology driven firms. That said, investors are growing cautious about returns from technology and particularly, AI investments. Economic data indicated a struggling Chinese economy with low factory output, weak retail sales, troubled property sector and high unemployment. This raises the likelihood of policy support in the fourth quarter; economists suggest monetary easing and fiscal expansion. Despite underwhelming economic data, the Chinese stock market stands at a stark contrast to the economy with the Shanghai Composite Index at a 10-year high. Additionally, the government announced their aim to triple chip output in 2026. The reluctance of household spending is evident in the size of savings worth more than 60% of the total value of the Chinese stock markets, leading analysts to believe that the rally is supported by long-term and institutional investors. Key drivers include the strategic deployment of state funds, inflows from global institutional investors—such as major U.S. financial institutions like Goldman Sachs and JPMorgan, as well as large Singapore-based funds—and increased participation by domestic mutual funds and insurers. Looking ahead, we remain cautiously optimistic. While trade frictions, sticky inflation, and geopolitical tensions continue to weigh on sentiment, global activity remains resilient. Primarily driven by technology companies’ robust earnings, U.S. equities performed well, with S&P 500 and Nasdaq reaching record highs in August. Despite an initial pullback, markets have broadly rallied since, buoyed by expectations of two more rate cuts this year, moderating inflation, and resilient corporate earnings. Within Asia, institutional investors looking for diversification beyond U.S. assets are lured by China’s stock market bull run. Against this backdrop, we maintain a disciplined and balanced approach, grounded in bottom-up fundamental analysis in our portfolio construction.