

Insights
Explore the latest news, expert articles, and market outlooks to stay ahead of industry trends.
Newsroom
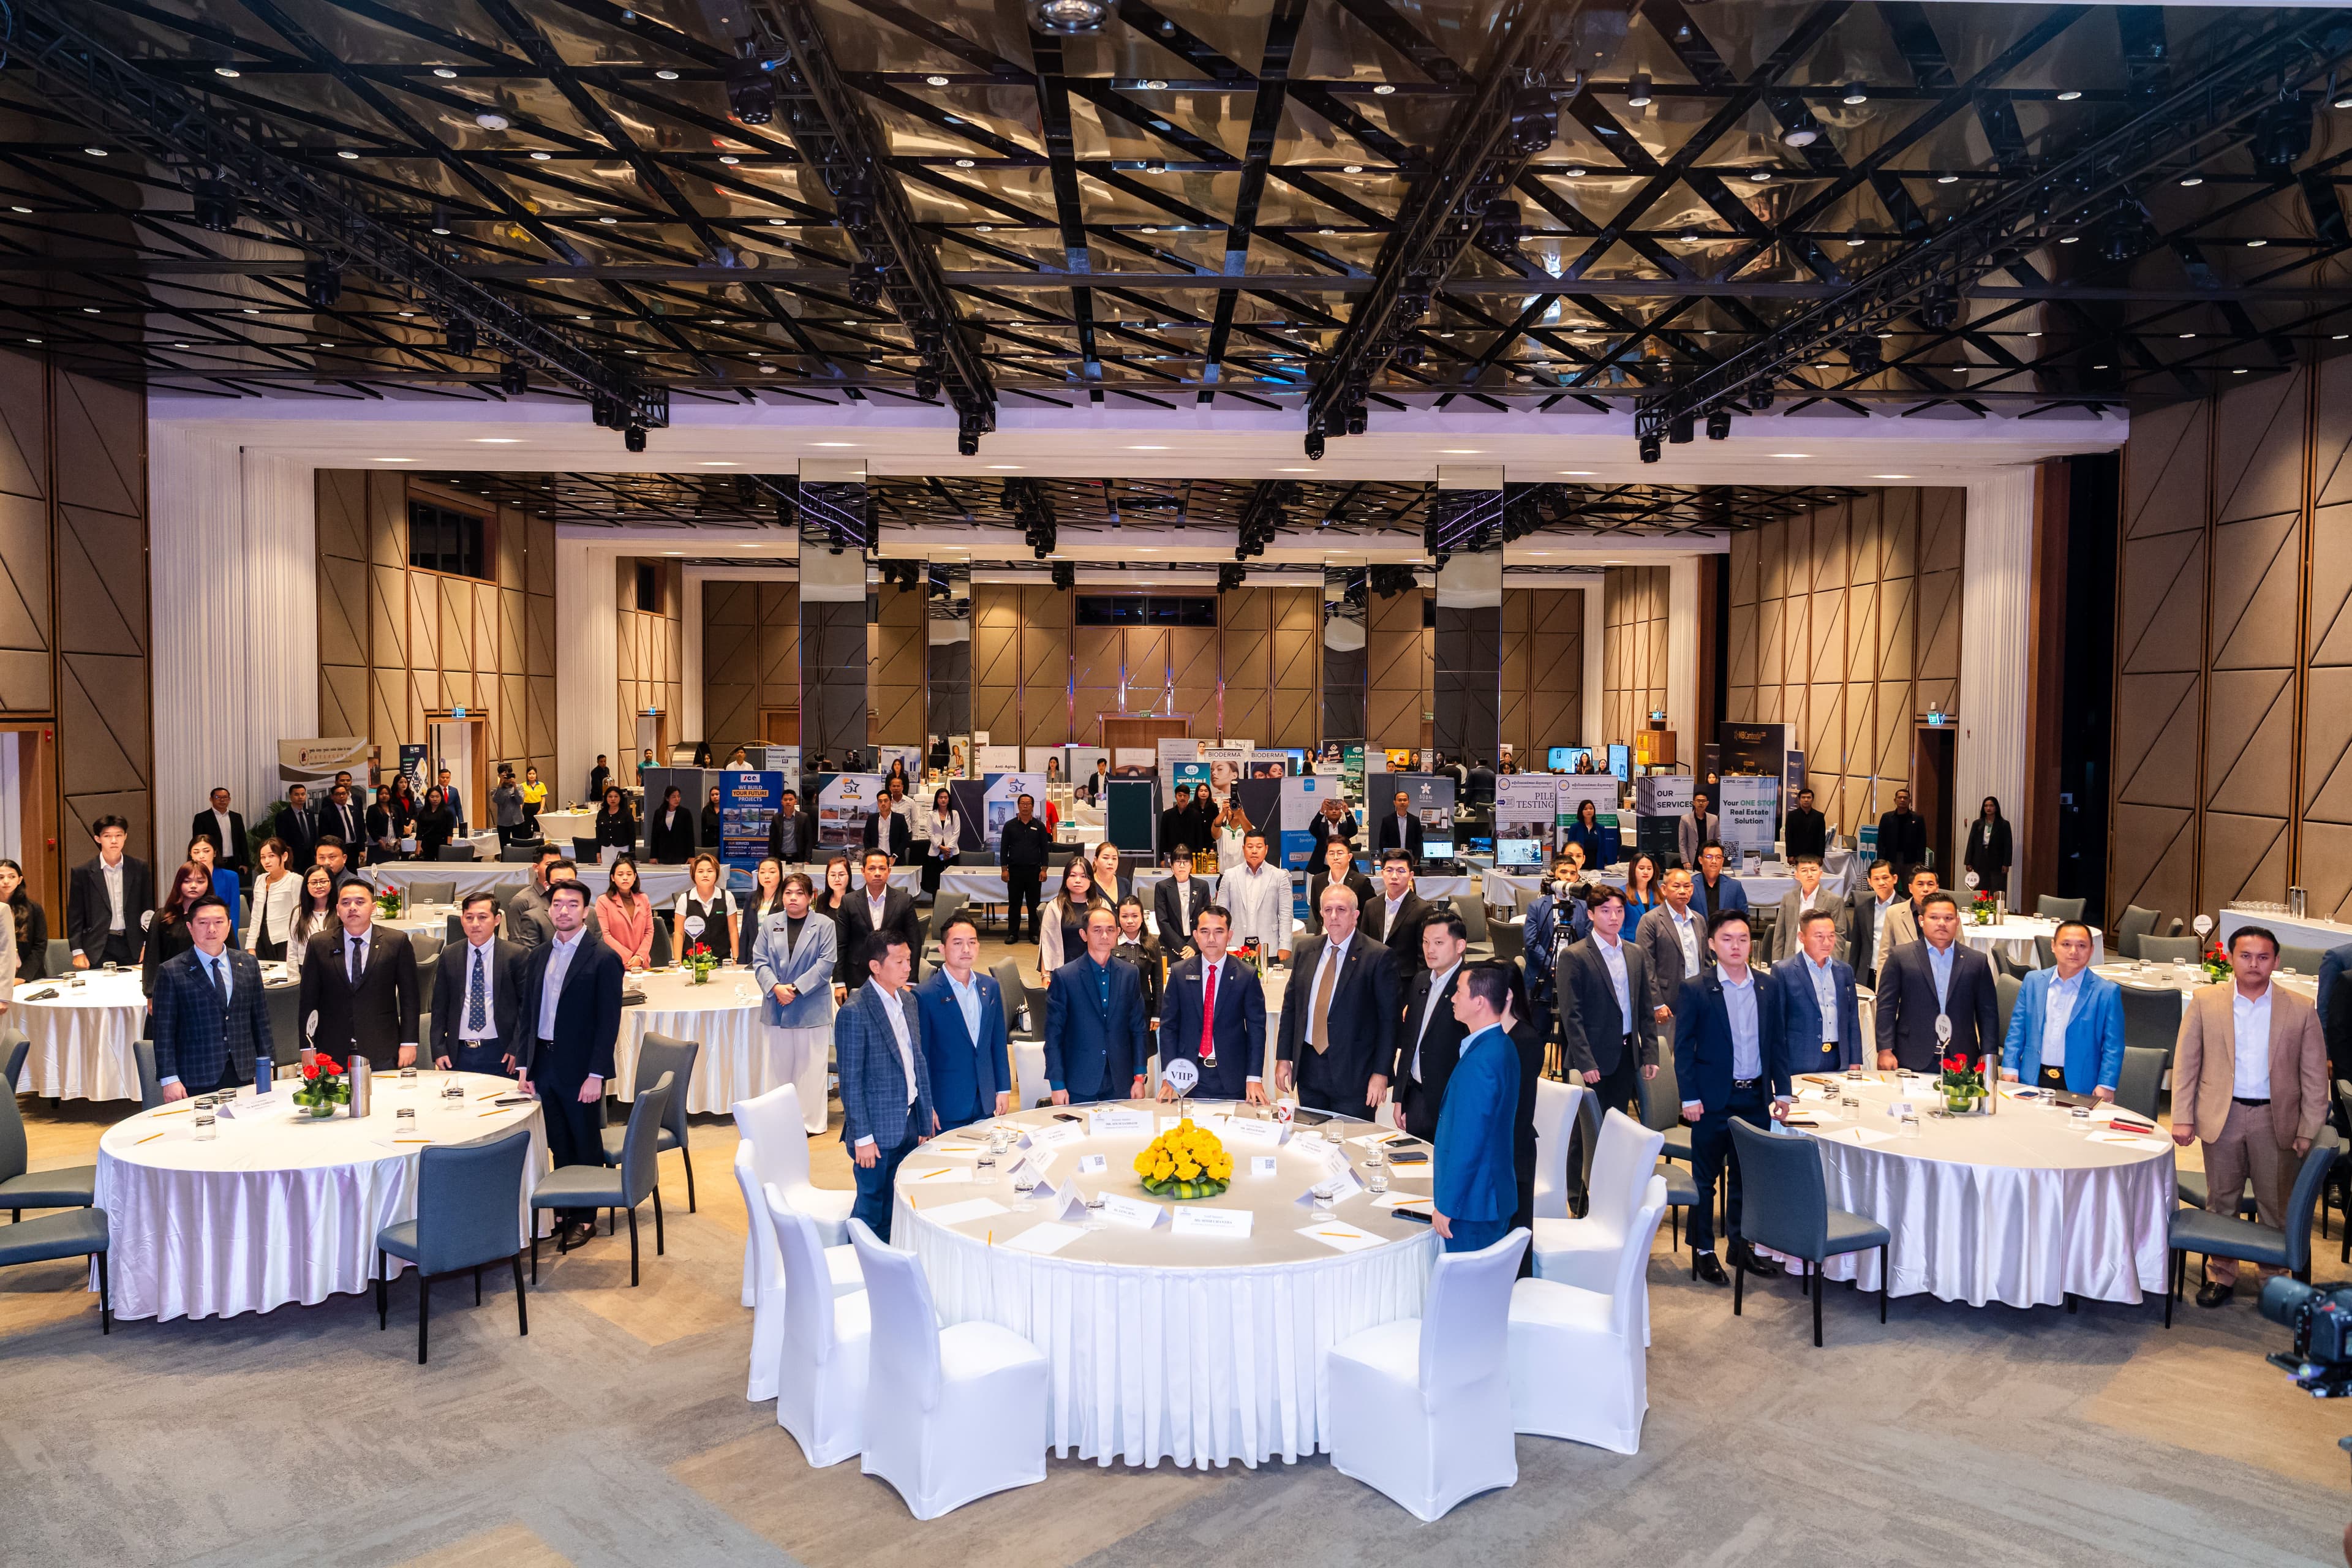
CorporateConnections Cambodia Annual Expo 2025: Construction, Business Services, Food & Beverage and Hospitality
Banjaran Asset Management (Cambodia) Plc. was honored to participate in the “CorporateConnections Cambodia Annual Expo 2025: Construction, Business Services, Food & Beverage and Hospitality” held on 28th November 2025. We were delighted to host our booth and engage with the many attendees who visited and took part in our activities. Your interest and participation truly made our presence at the event meaningful. Stay connected with us for more upcoming opportunities and events!
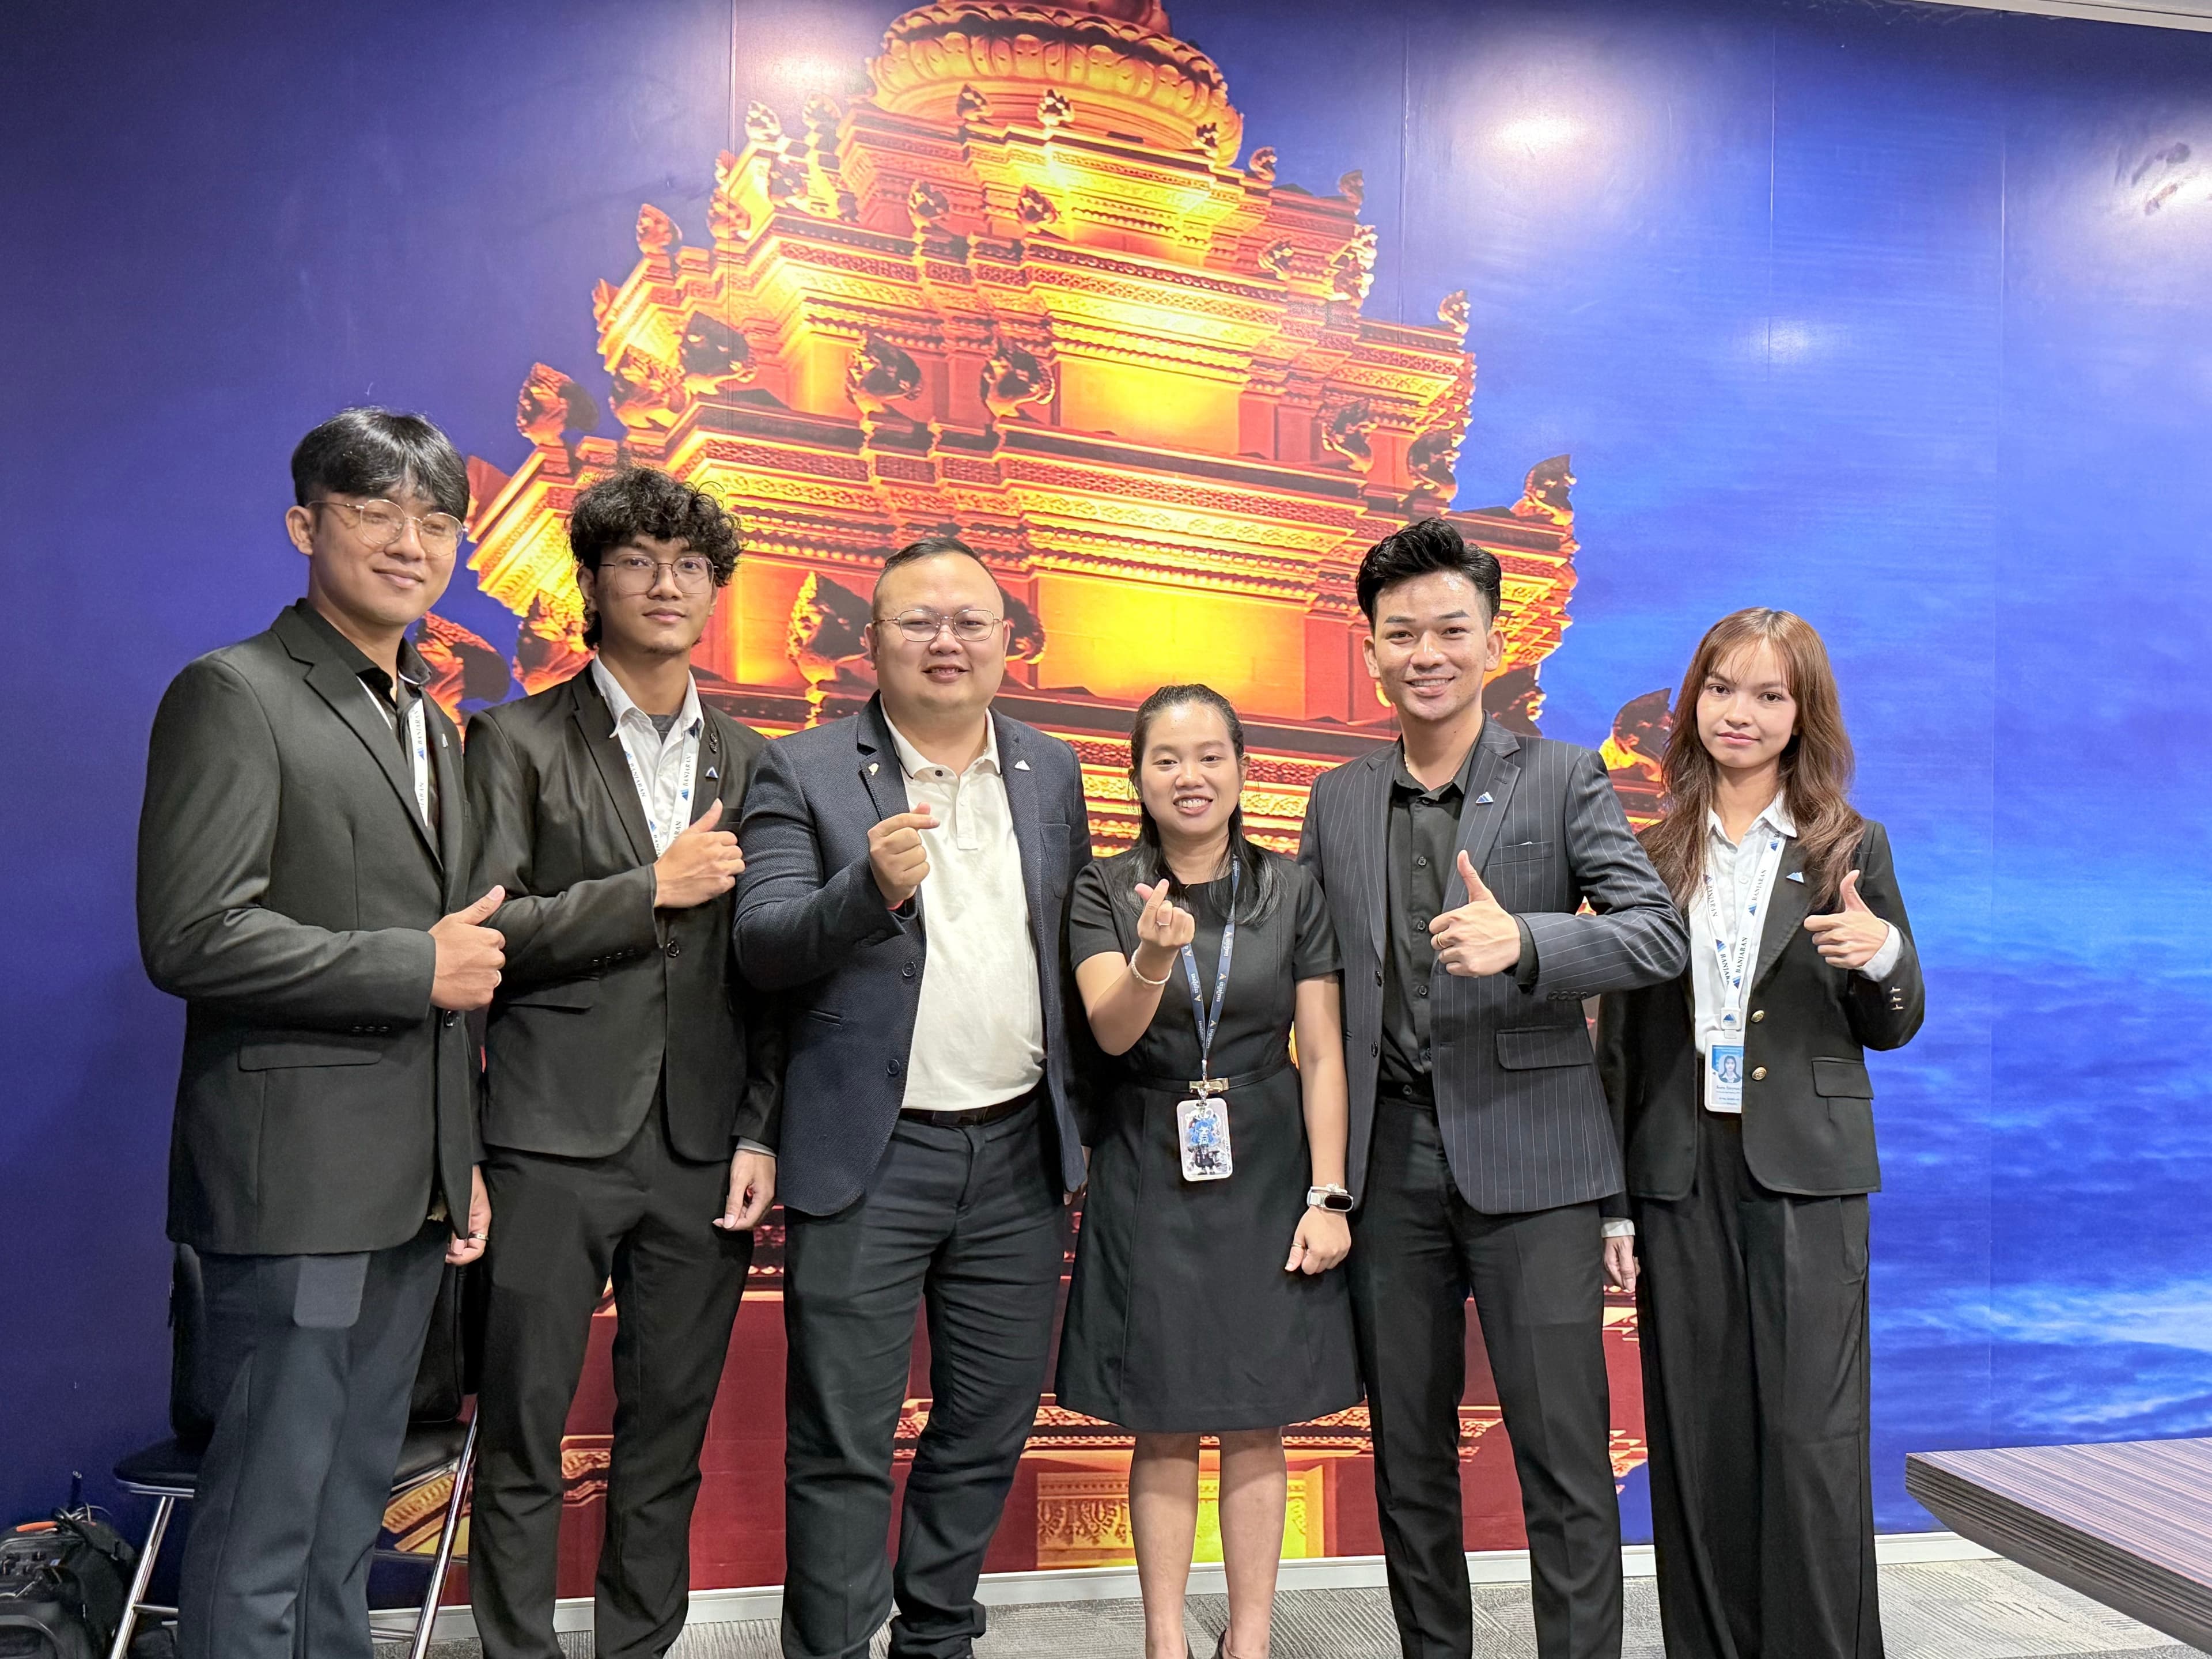
Let’s Talk Investment! Insights on Collective Investment Scheme!
Thank you to everyone who joined us on 21st November 2025 at ACLEDA Securities Plc.. Your questions, enthusiasm, and participation made the discussion on Collective Investment Schemes both engaging and meaningful. We appreciate the opportunity to share practical investment knowledge and help build financial confidence within the community. We’re excited to continue this learning journey with you in our upcoming December session. Stay tuned so you wouldn't miss the next one!
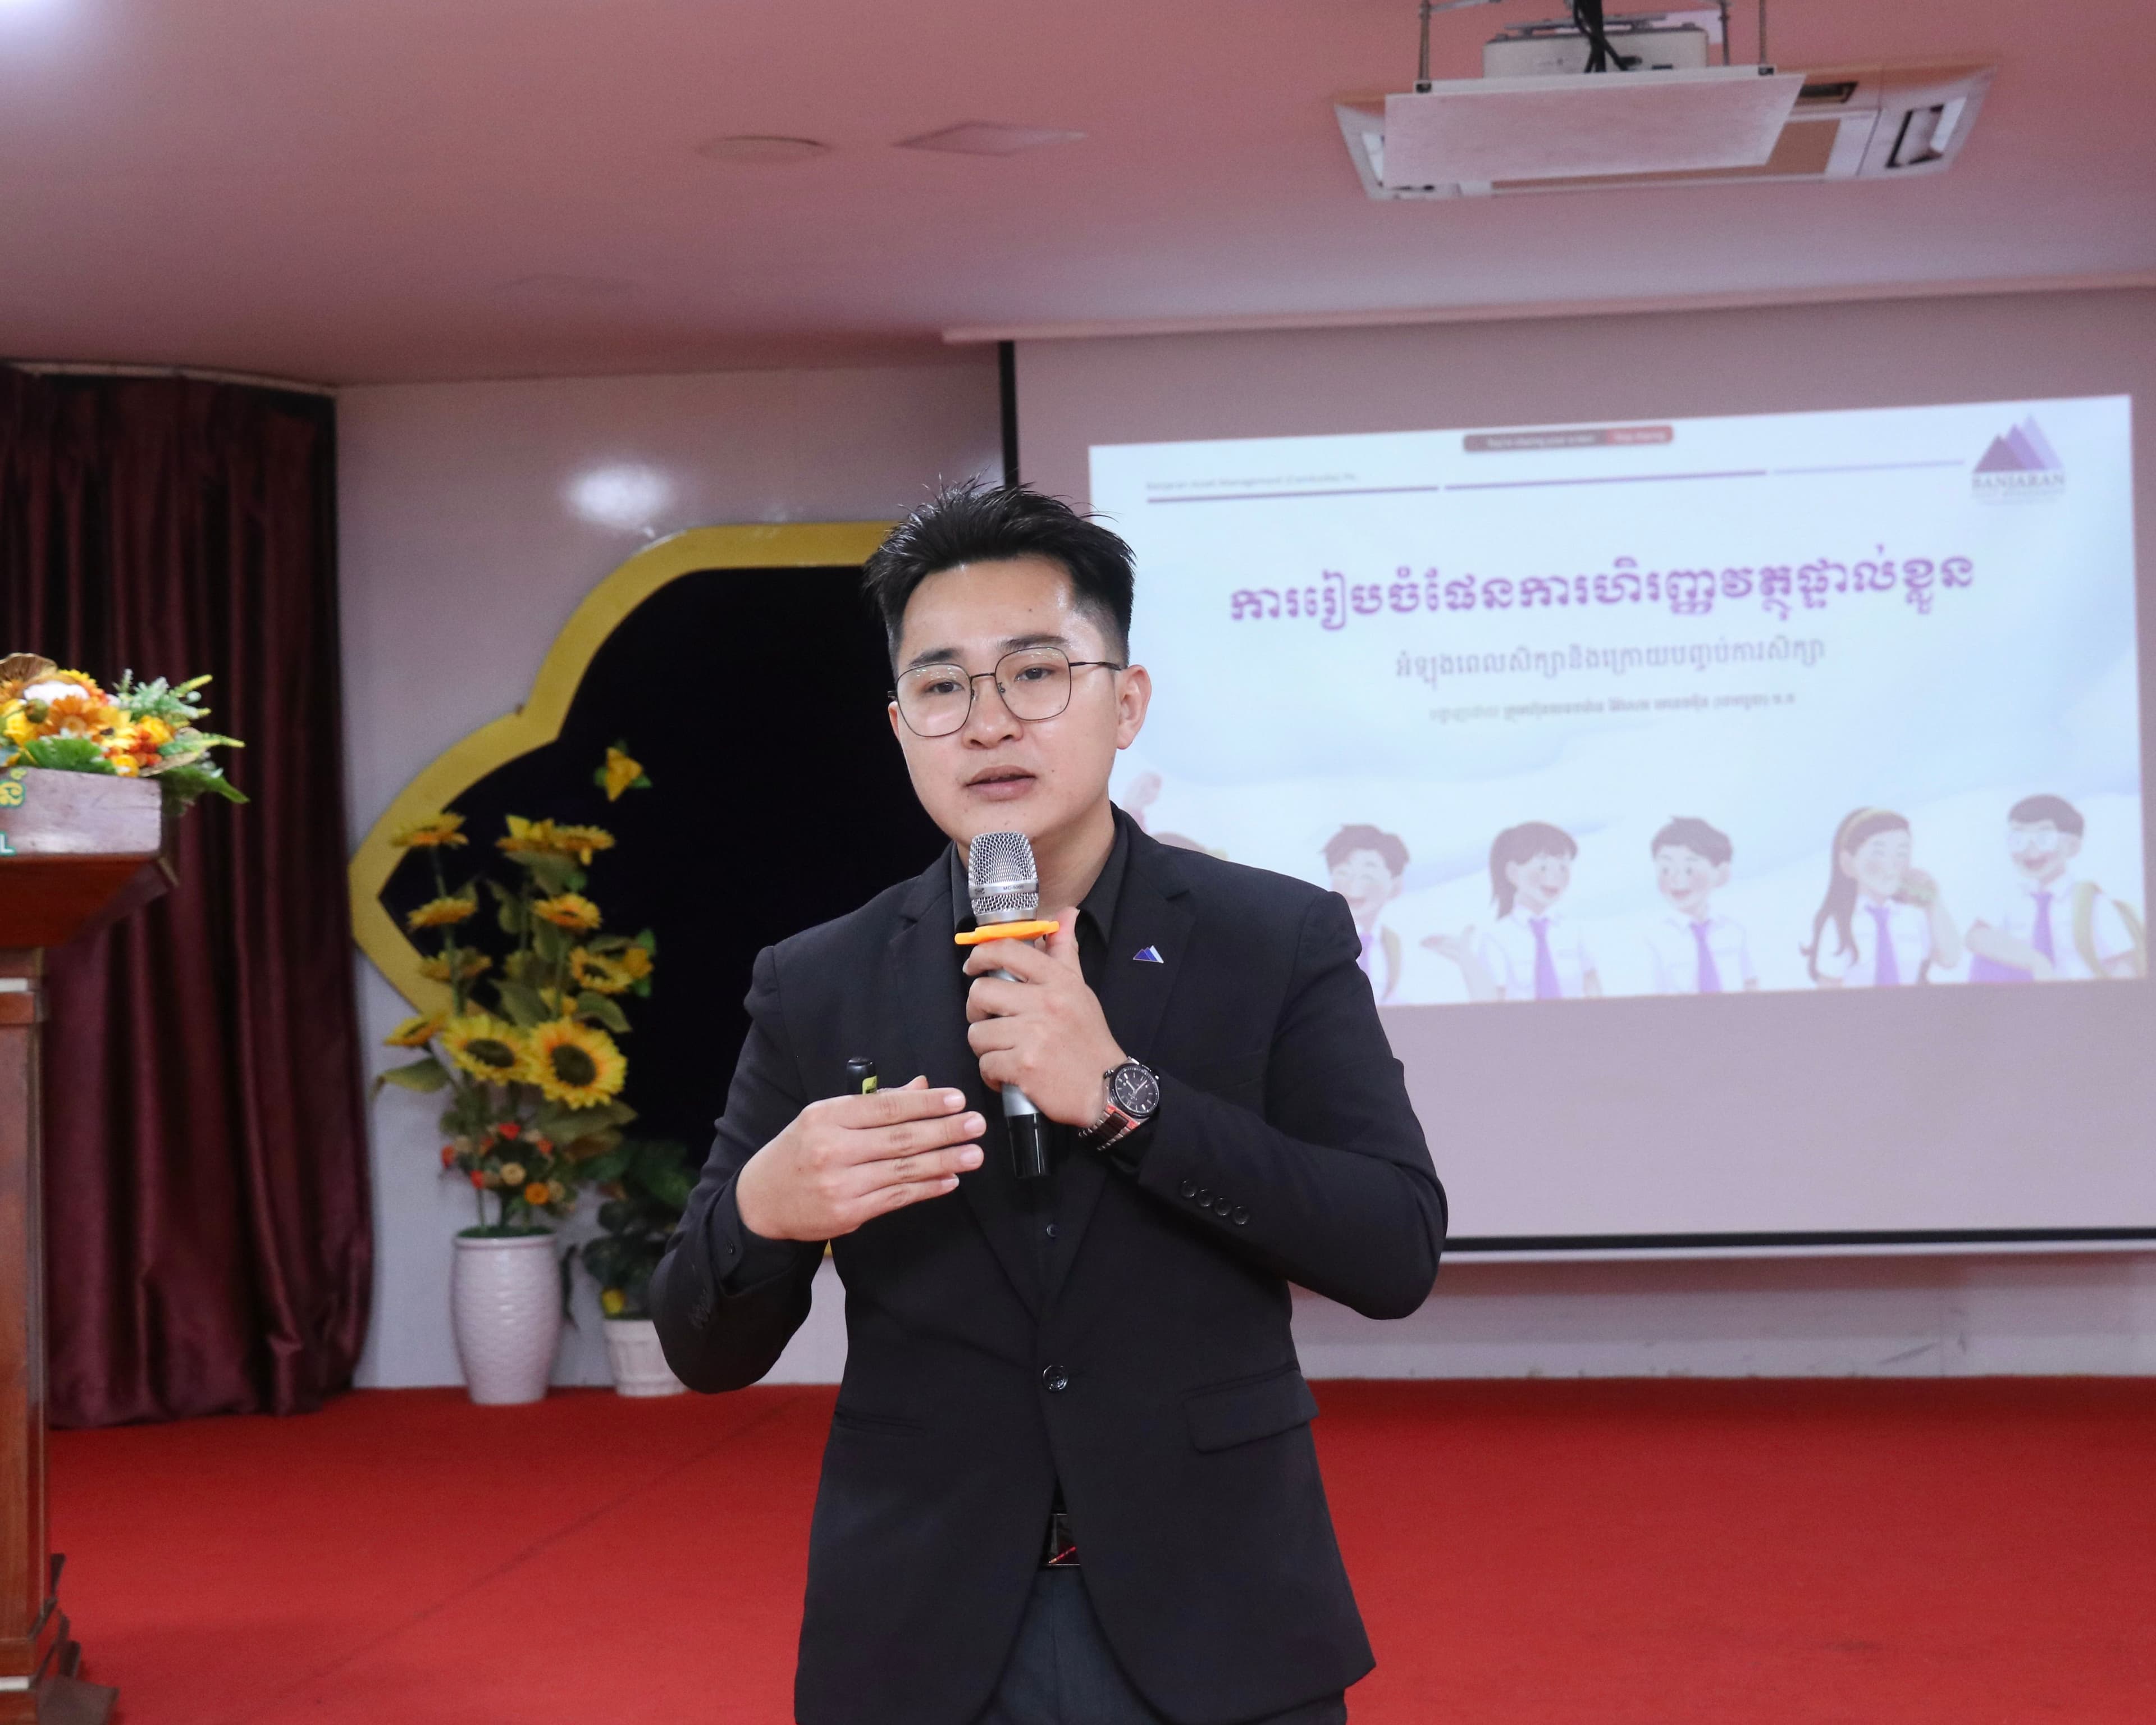
training session on "Promoting Financial Literacy Awareness of the Securities Sector" Part 2
Afternoon of November 12, 2025, representatives from Banjaran Asset Management (Cambodia) Plc. participated in a training session on "Promoting Financial Literacy Awareness of the Securities Sector" organized by the Securities and Exchange Regulator of Cambodia (SERC), in collaboration with The Westline School, (Santhormok Branch). During this training session, with the approval of the management of Banjaran Asset Management (Cambodia) Plc., Mr. Taing Hoy, Legal and Compliance Officer, delivered a presentation on "Personal Financial Planning During and After Graduation" guiding participants on how to effectively manage and plan their long-term financial savings. The training aimed to promote financial literacy among the students, encouraging effective saving habits and smart investment practices to help them plan for long-term financial stability.
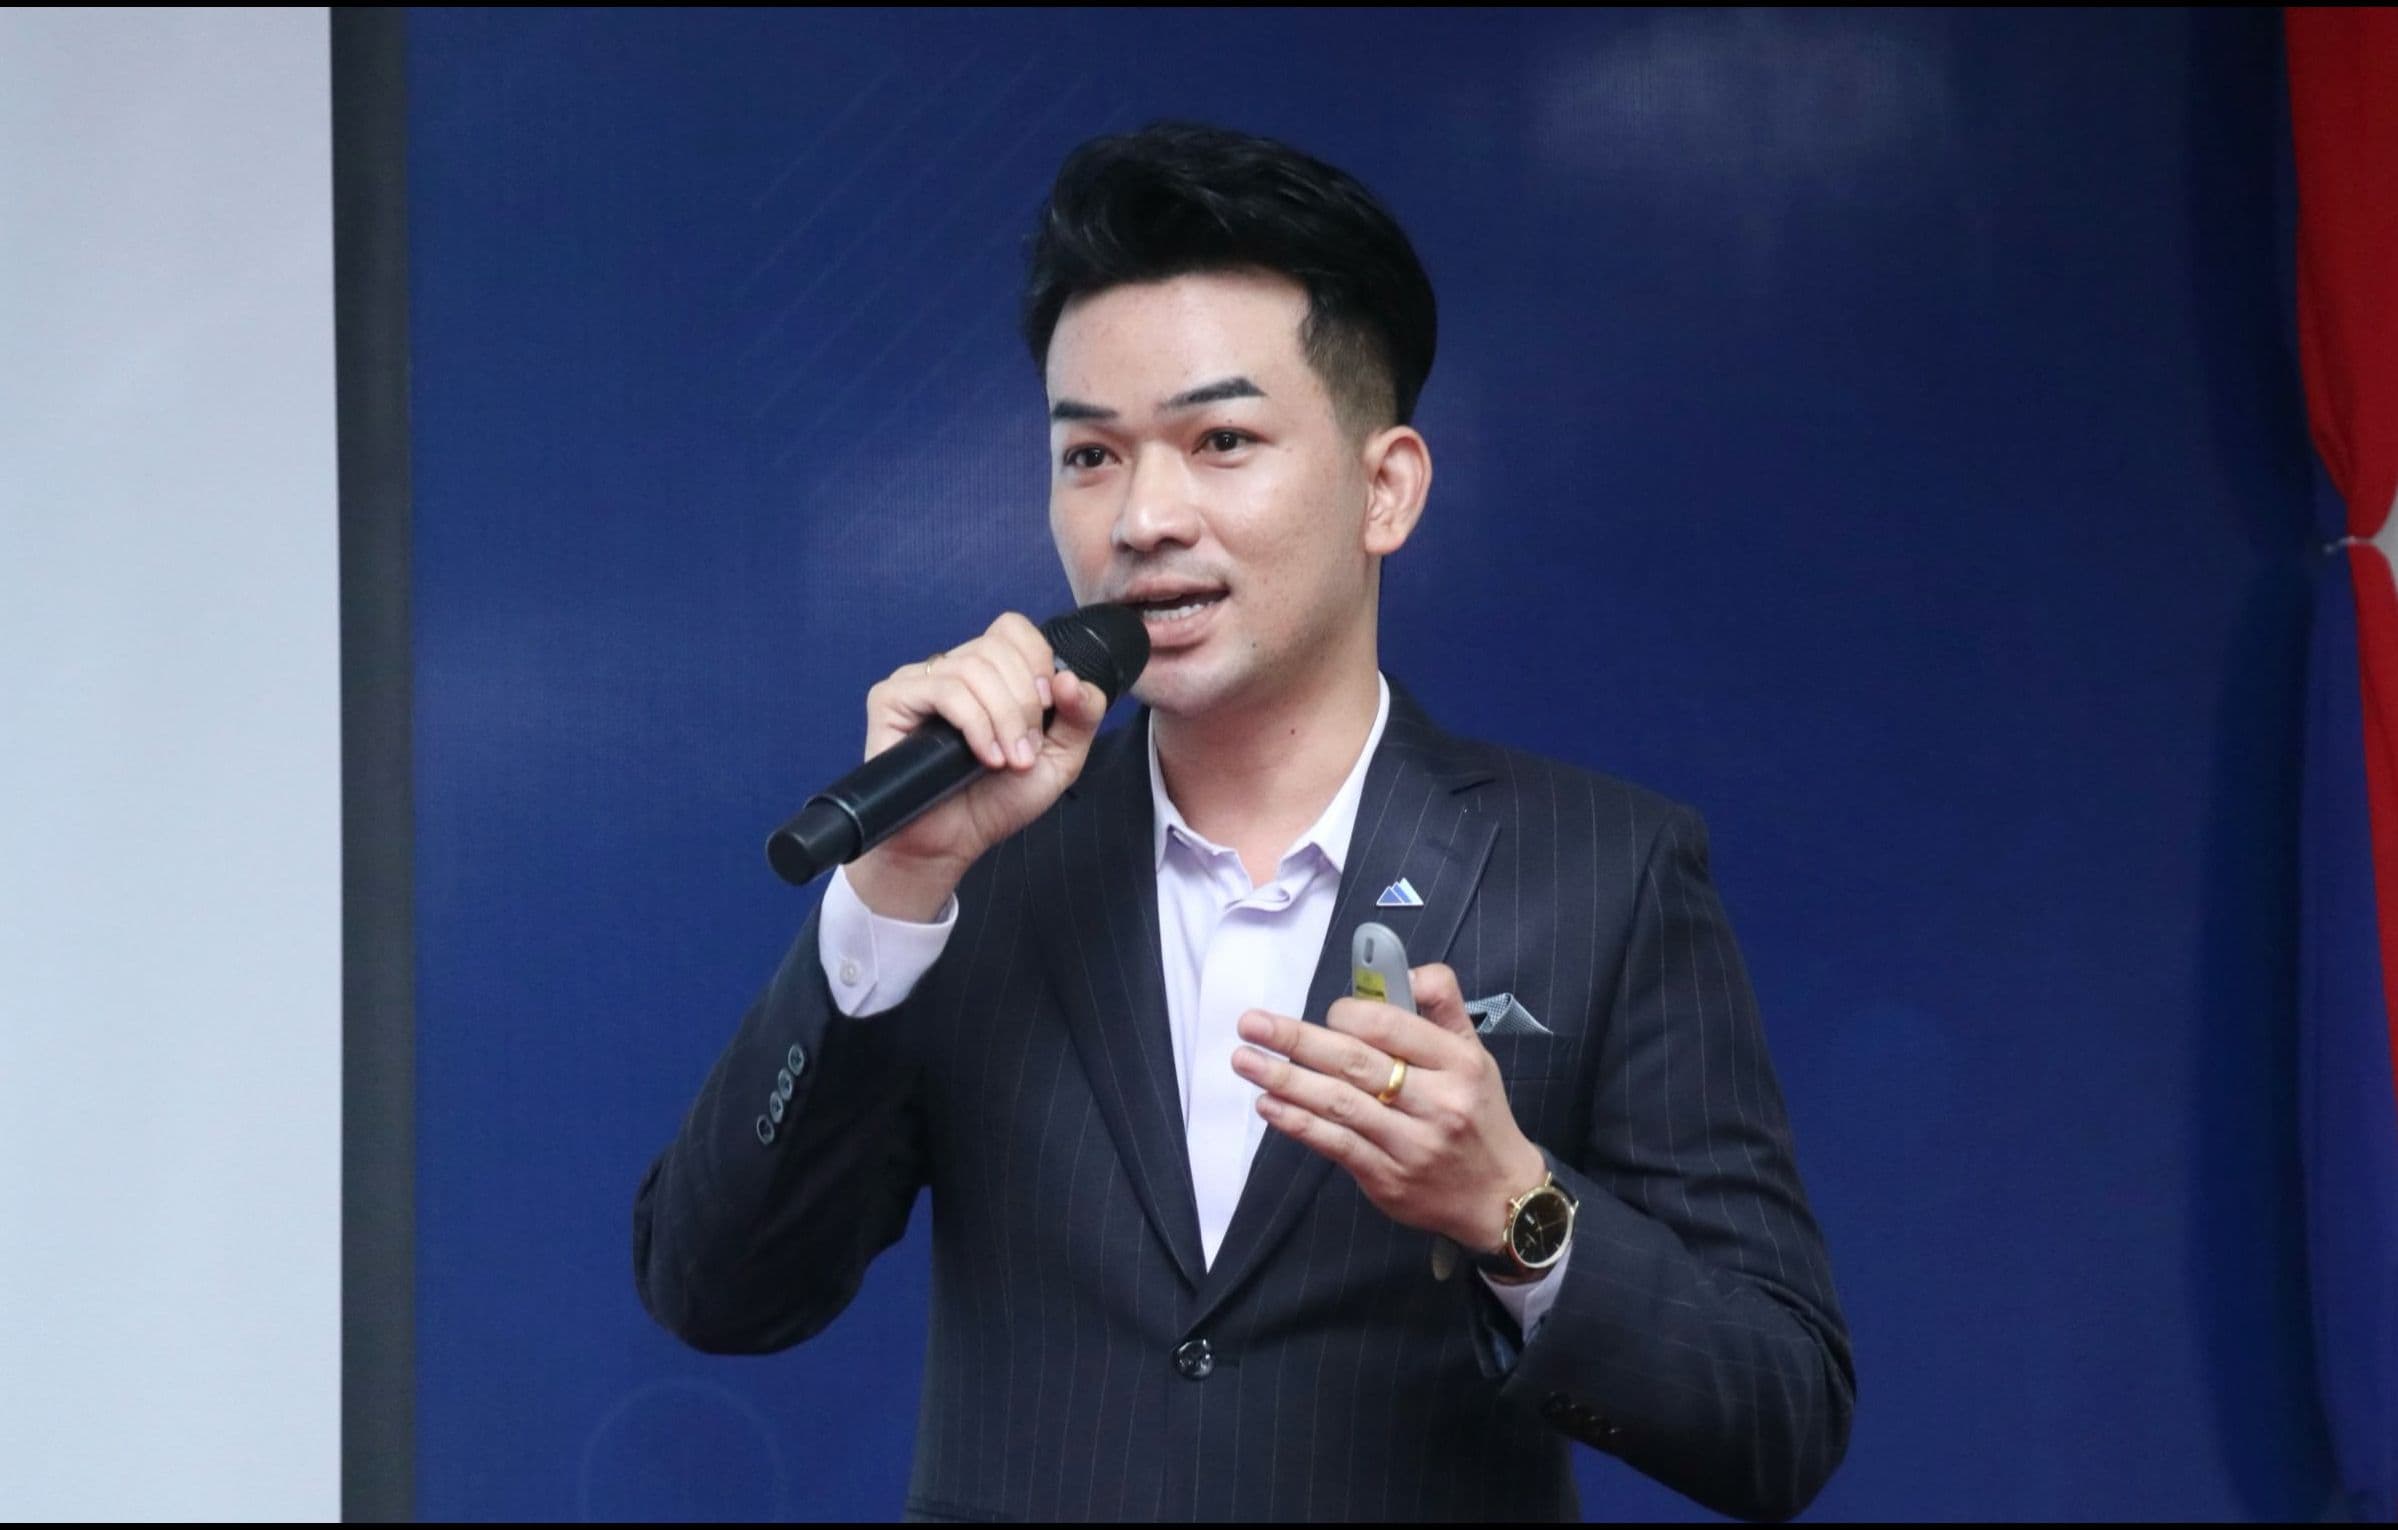
training session on "Promoting Financial Literacy Awareness of the Securities Sector"
Afternoon of November 11, 2025, representatives from Banjaran Asset Management (Cambodia) Plc. participated in a training session on "Promoting Financial Literacy Awareness of the Securities Sector" organized by the Securities and Exchange Regulator of Cambodia (SERC), in collaboration with ACLEDA University of Business (AUB). During this training session, with the approval of the management of Banjaran Asset Management (Cambodia) Plc., Mr. Sok Chantola, Deputy Sales & Marketing Manager, delivered a presentation on "Personal Financial Planning During and After Graduation" guiding participants on how to effectively manage and plan their long-term financial savings. The training aimed to promote financial literacy among university students, encouraging effective saving habits and smart investment practices to help them plan for long-term financial stability.
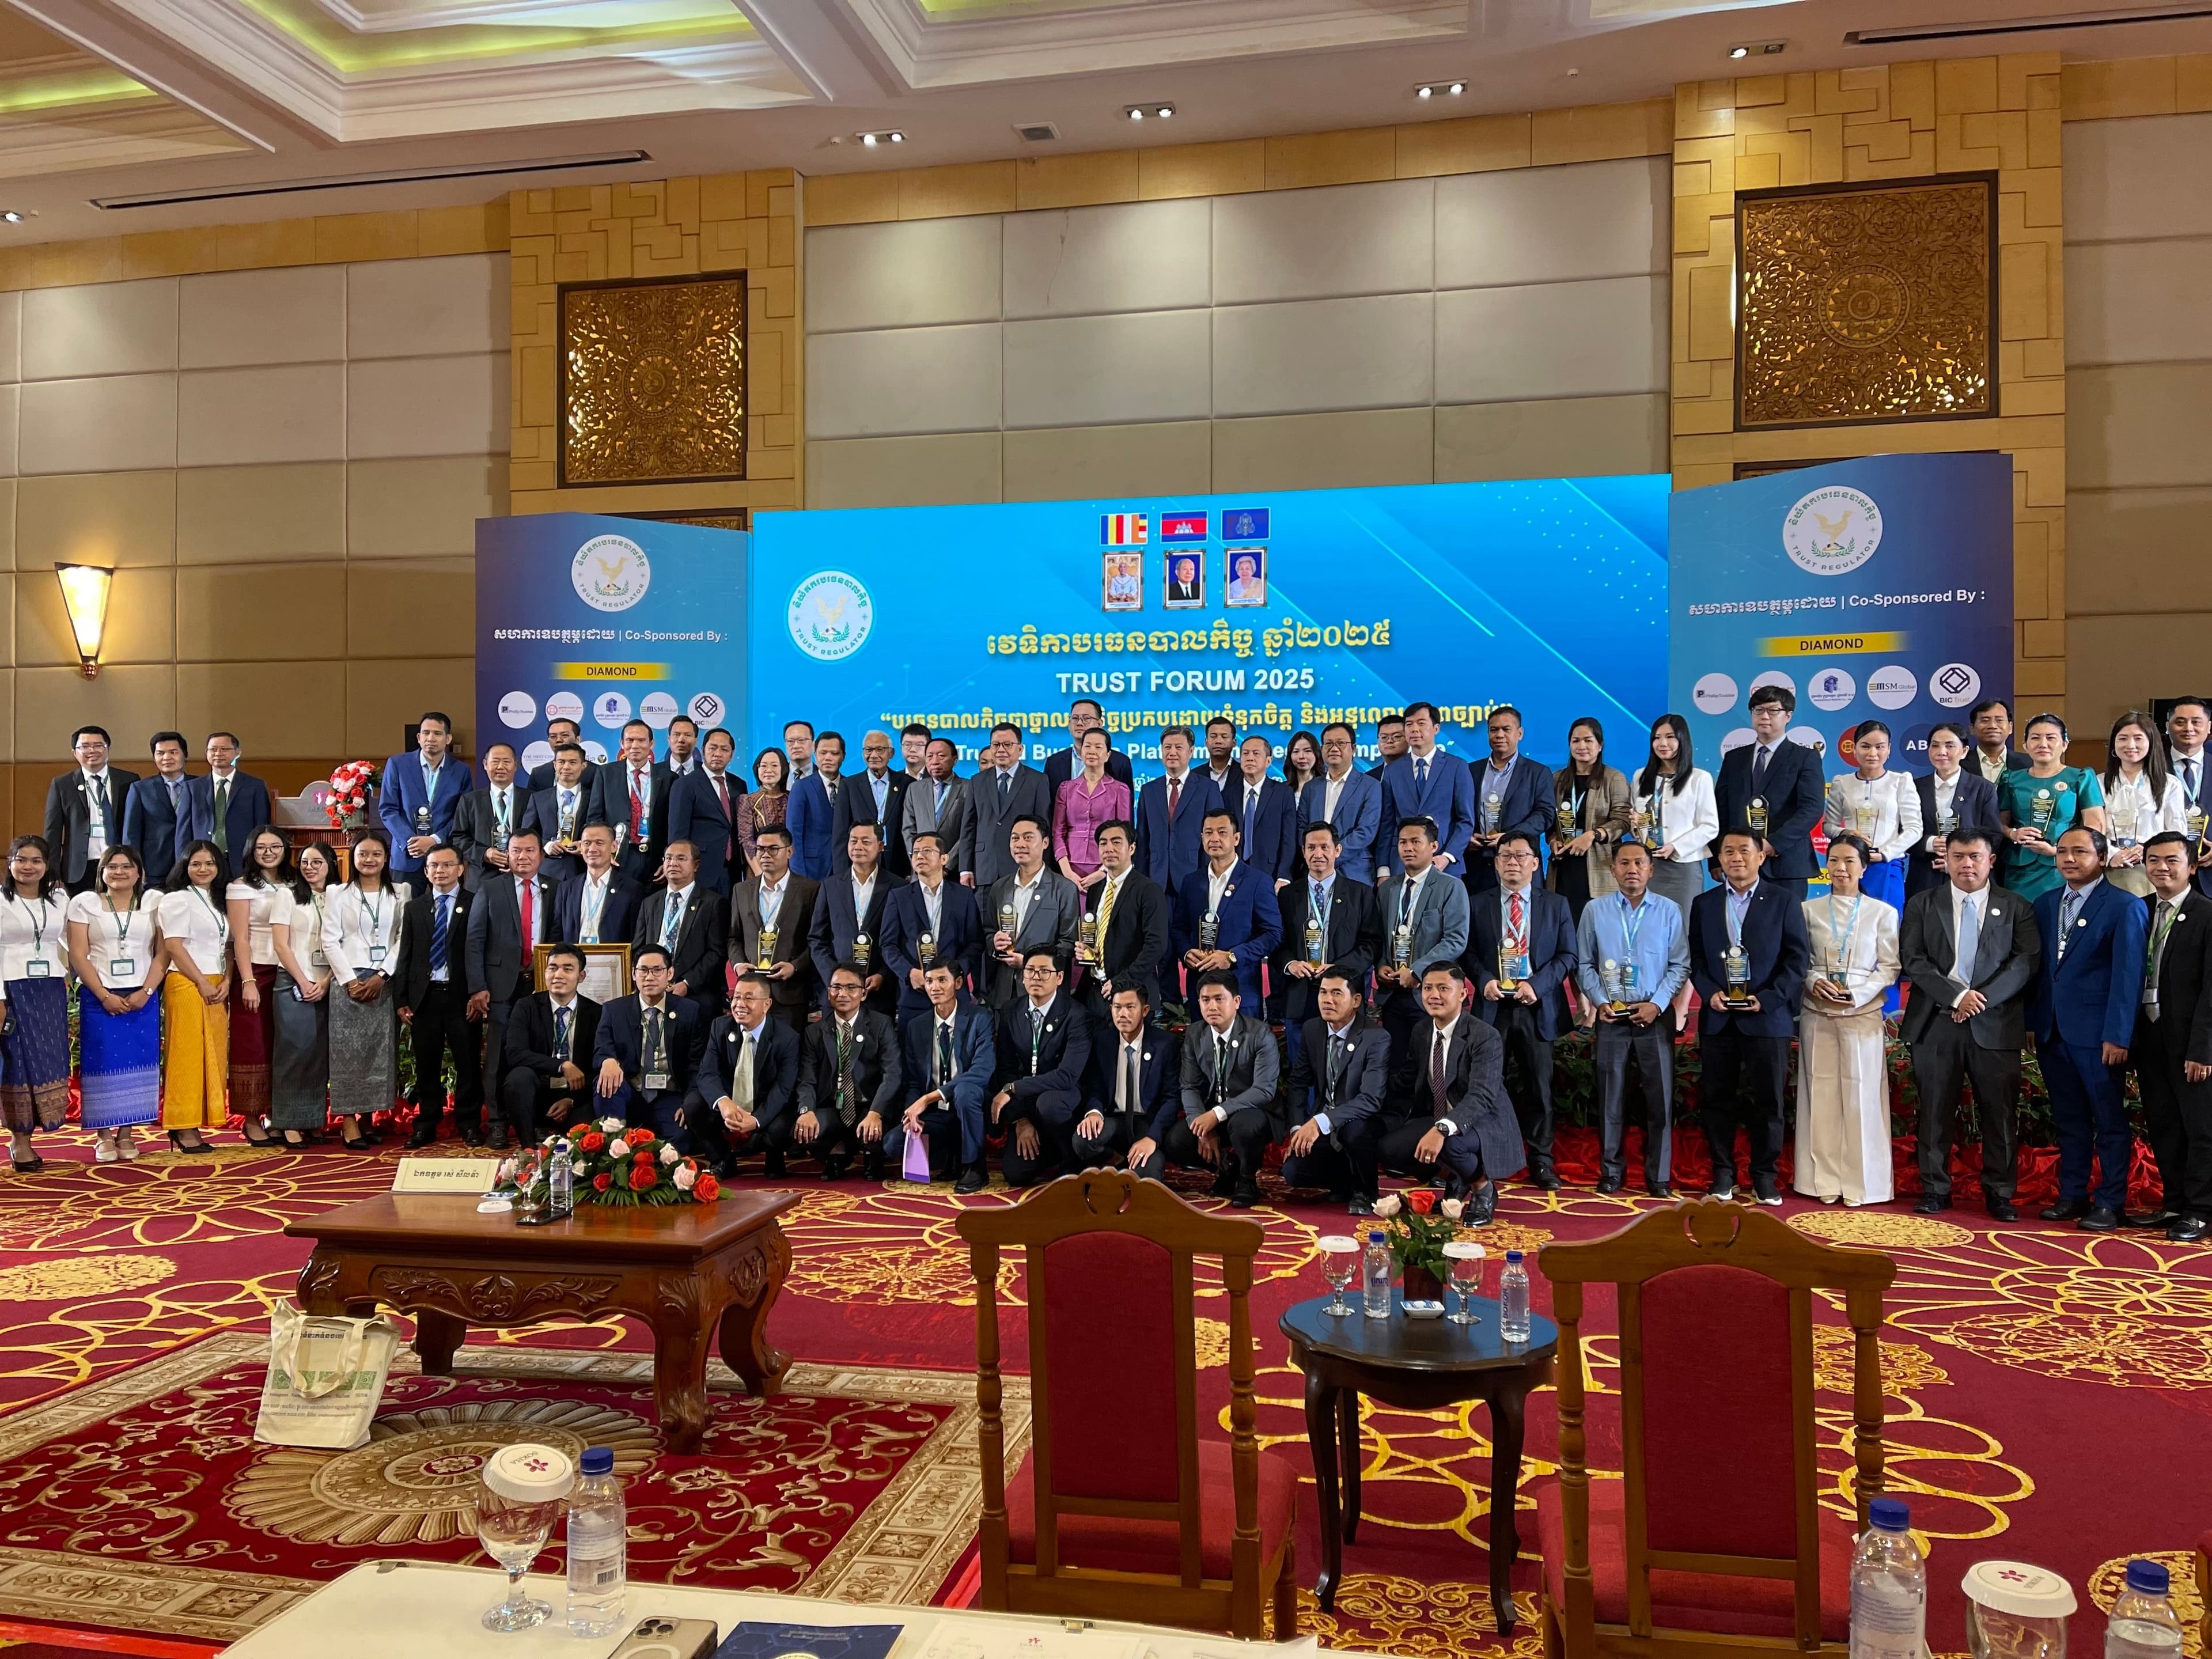
Trust Forum 2025
Mr. Eric Loo, CEO and Executive Director of Banjaran Asset Management (Cambodia) Plc., was honored to participate in the Trust Forum 2025, held on October 31, 2025, at Sokha Phnom Penh Hotel. The event, themed “A Trust Business Platform and Legal Compliance,” provided an important platform for discussions surrounding family trusts, the strategic direction of Cambodia’s trust sector, and efforts to promote a robust and transparent trust business environment. Through his attendance, Mr. Eric expressed his appreciation for the opportunity to engage with key stakeholders and contribute to conversations that support the continued development of Cambodia’s trust industry.
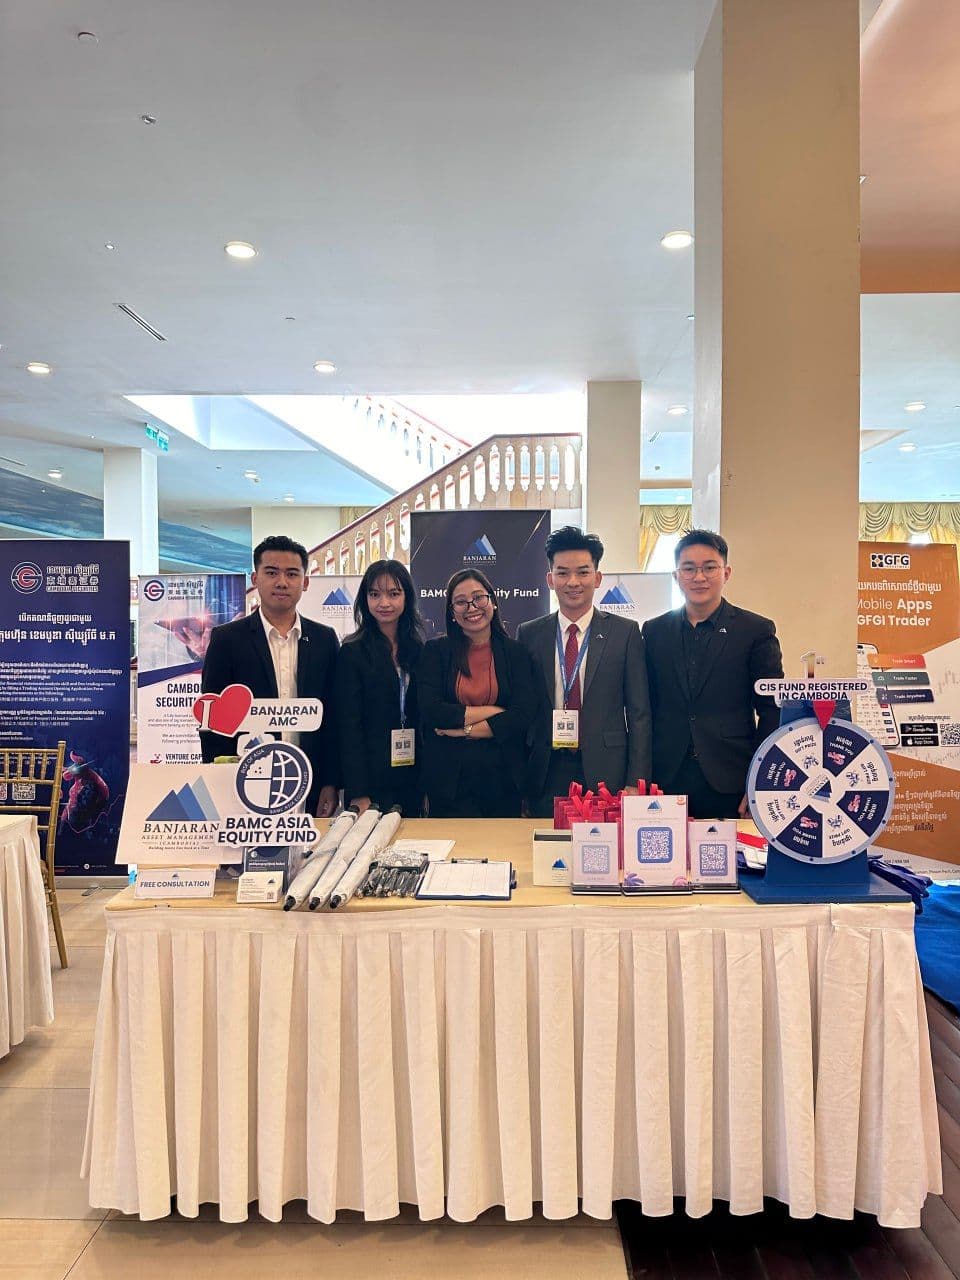
Banjaran AMC Joins the Annual Securities Conference 2025
Banjaran Asset Management (Cambodia) PLC. is honored to participate in the Annual Securities Conference 2025 held on October 7th! We were delighted to engage with participants who visited our booth throughout the event. The event was graced by the presence of H.E. Dr. AUN Pornmoniroth, Deputy Prime Minister, Minister of Economy and Finance, Chairman of the Non-Bank Financial Services Authority, and H.E. Sou Socheat, Delegate of the Royal Government in charge as Director-General of the Securities and Exchange Regulator of Cambodia (SERC).
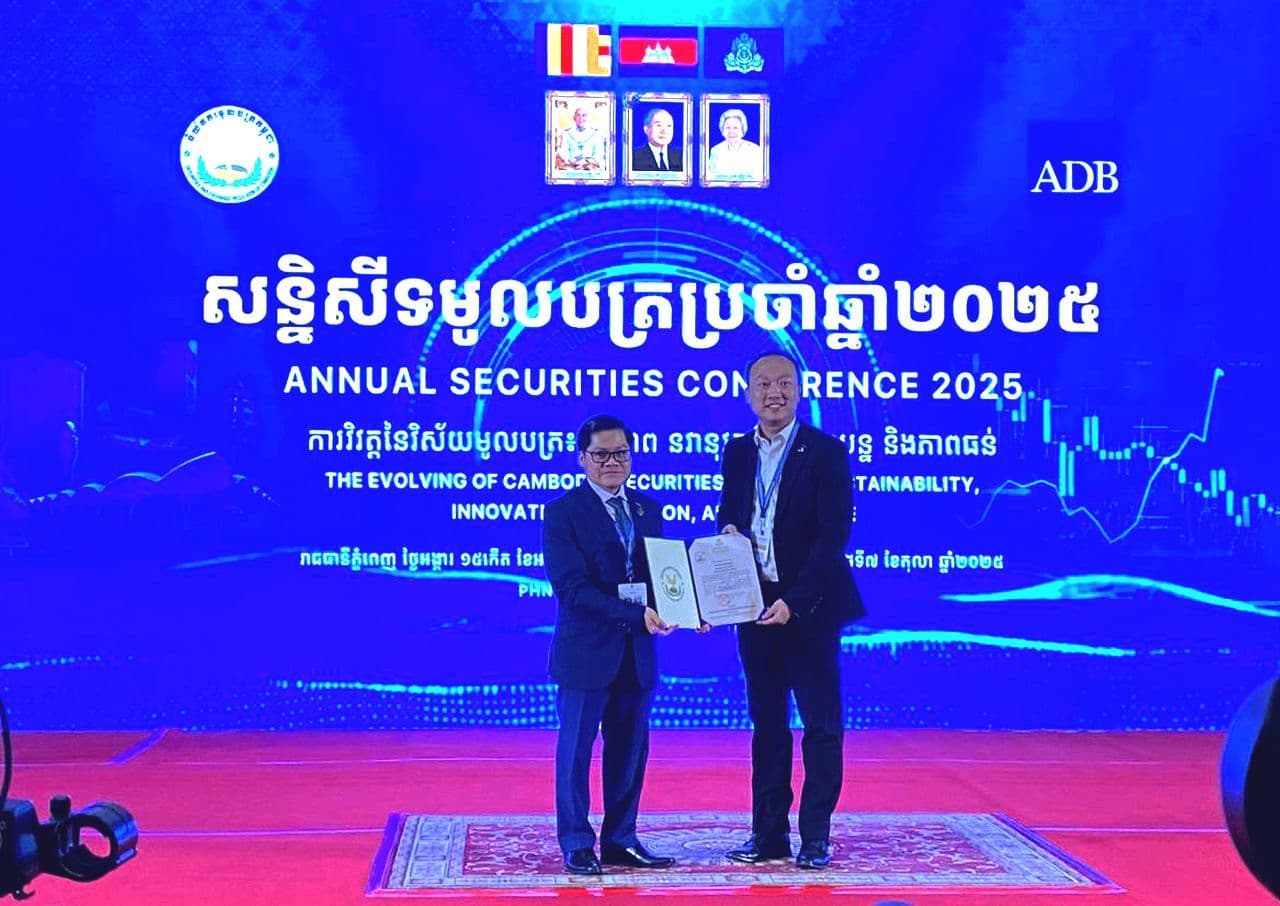
Banjaran Asset Management (Cambodia) Recognized for Its Contribution to Cambodia’s Financial Market
We’re truly honored to be one of the sponsors of the Annual Securities Conference 2025! Held on October 7th, 2025 in the Annual Securities Conference 2025 at Sokha Hotel, Mr. Eric Loo, CEO & Executive Director of Banjaran Asset Management (Cambodia) Plc. received a certificate of recognition from H.E. Sou Socheat, Delegate of the Royal Government in charge as Director General of SERC in this remarkable event—organized by the SERC, brought together leaders and professionals across Cambodia’s securities sector to discuss Sustainability, Innovation, Inclusion, and Resilience. Banjaran Asset Management (Cambodia) PLC. is proud to support the continued growth and innovation of Cambodia’s financial market!
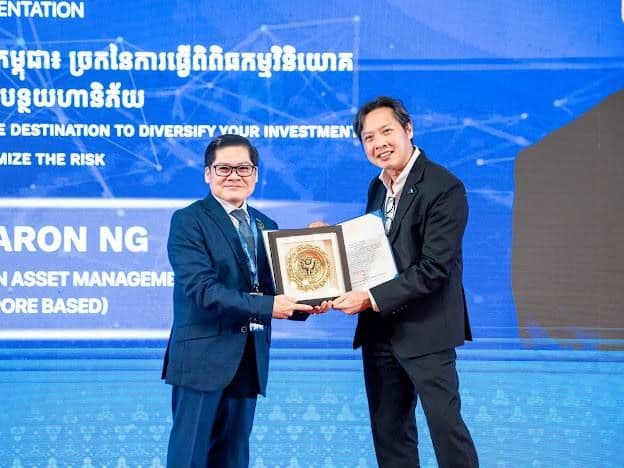
Mr. Aaron Ng Advocates Unit Trust Investment Strategies at the Annual Securities Conference 2025
Mr. Aaron Ng , CEO of Banjaran Asset Management Pte. Ltd. (Singapore), delivered an impactful presentation on “Investing in Unit Trust Funds in Cambodia: Diversity Your Investment And Minimize Your Risks” in the Annual Securities Conference 2025, organized by the Securities and Exchange Regulator of Cambodia (SERC), on October 7th, 2025, Sokha Hotel. Presided over by H.E. Dr. AUN Pornmoniroth , Deputy Prime Minister, Minister of Economy and Finance, and Chairman of the Non-Bank Financial Services Authority. Mr. Aaron session provided valuable perspectives on the growth potential of Cambodia’s capital market and the crucial role of unit trust funds in minimizing risks and diversifying investments
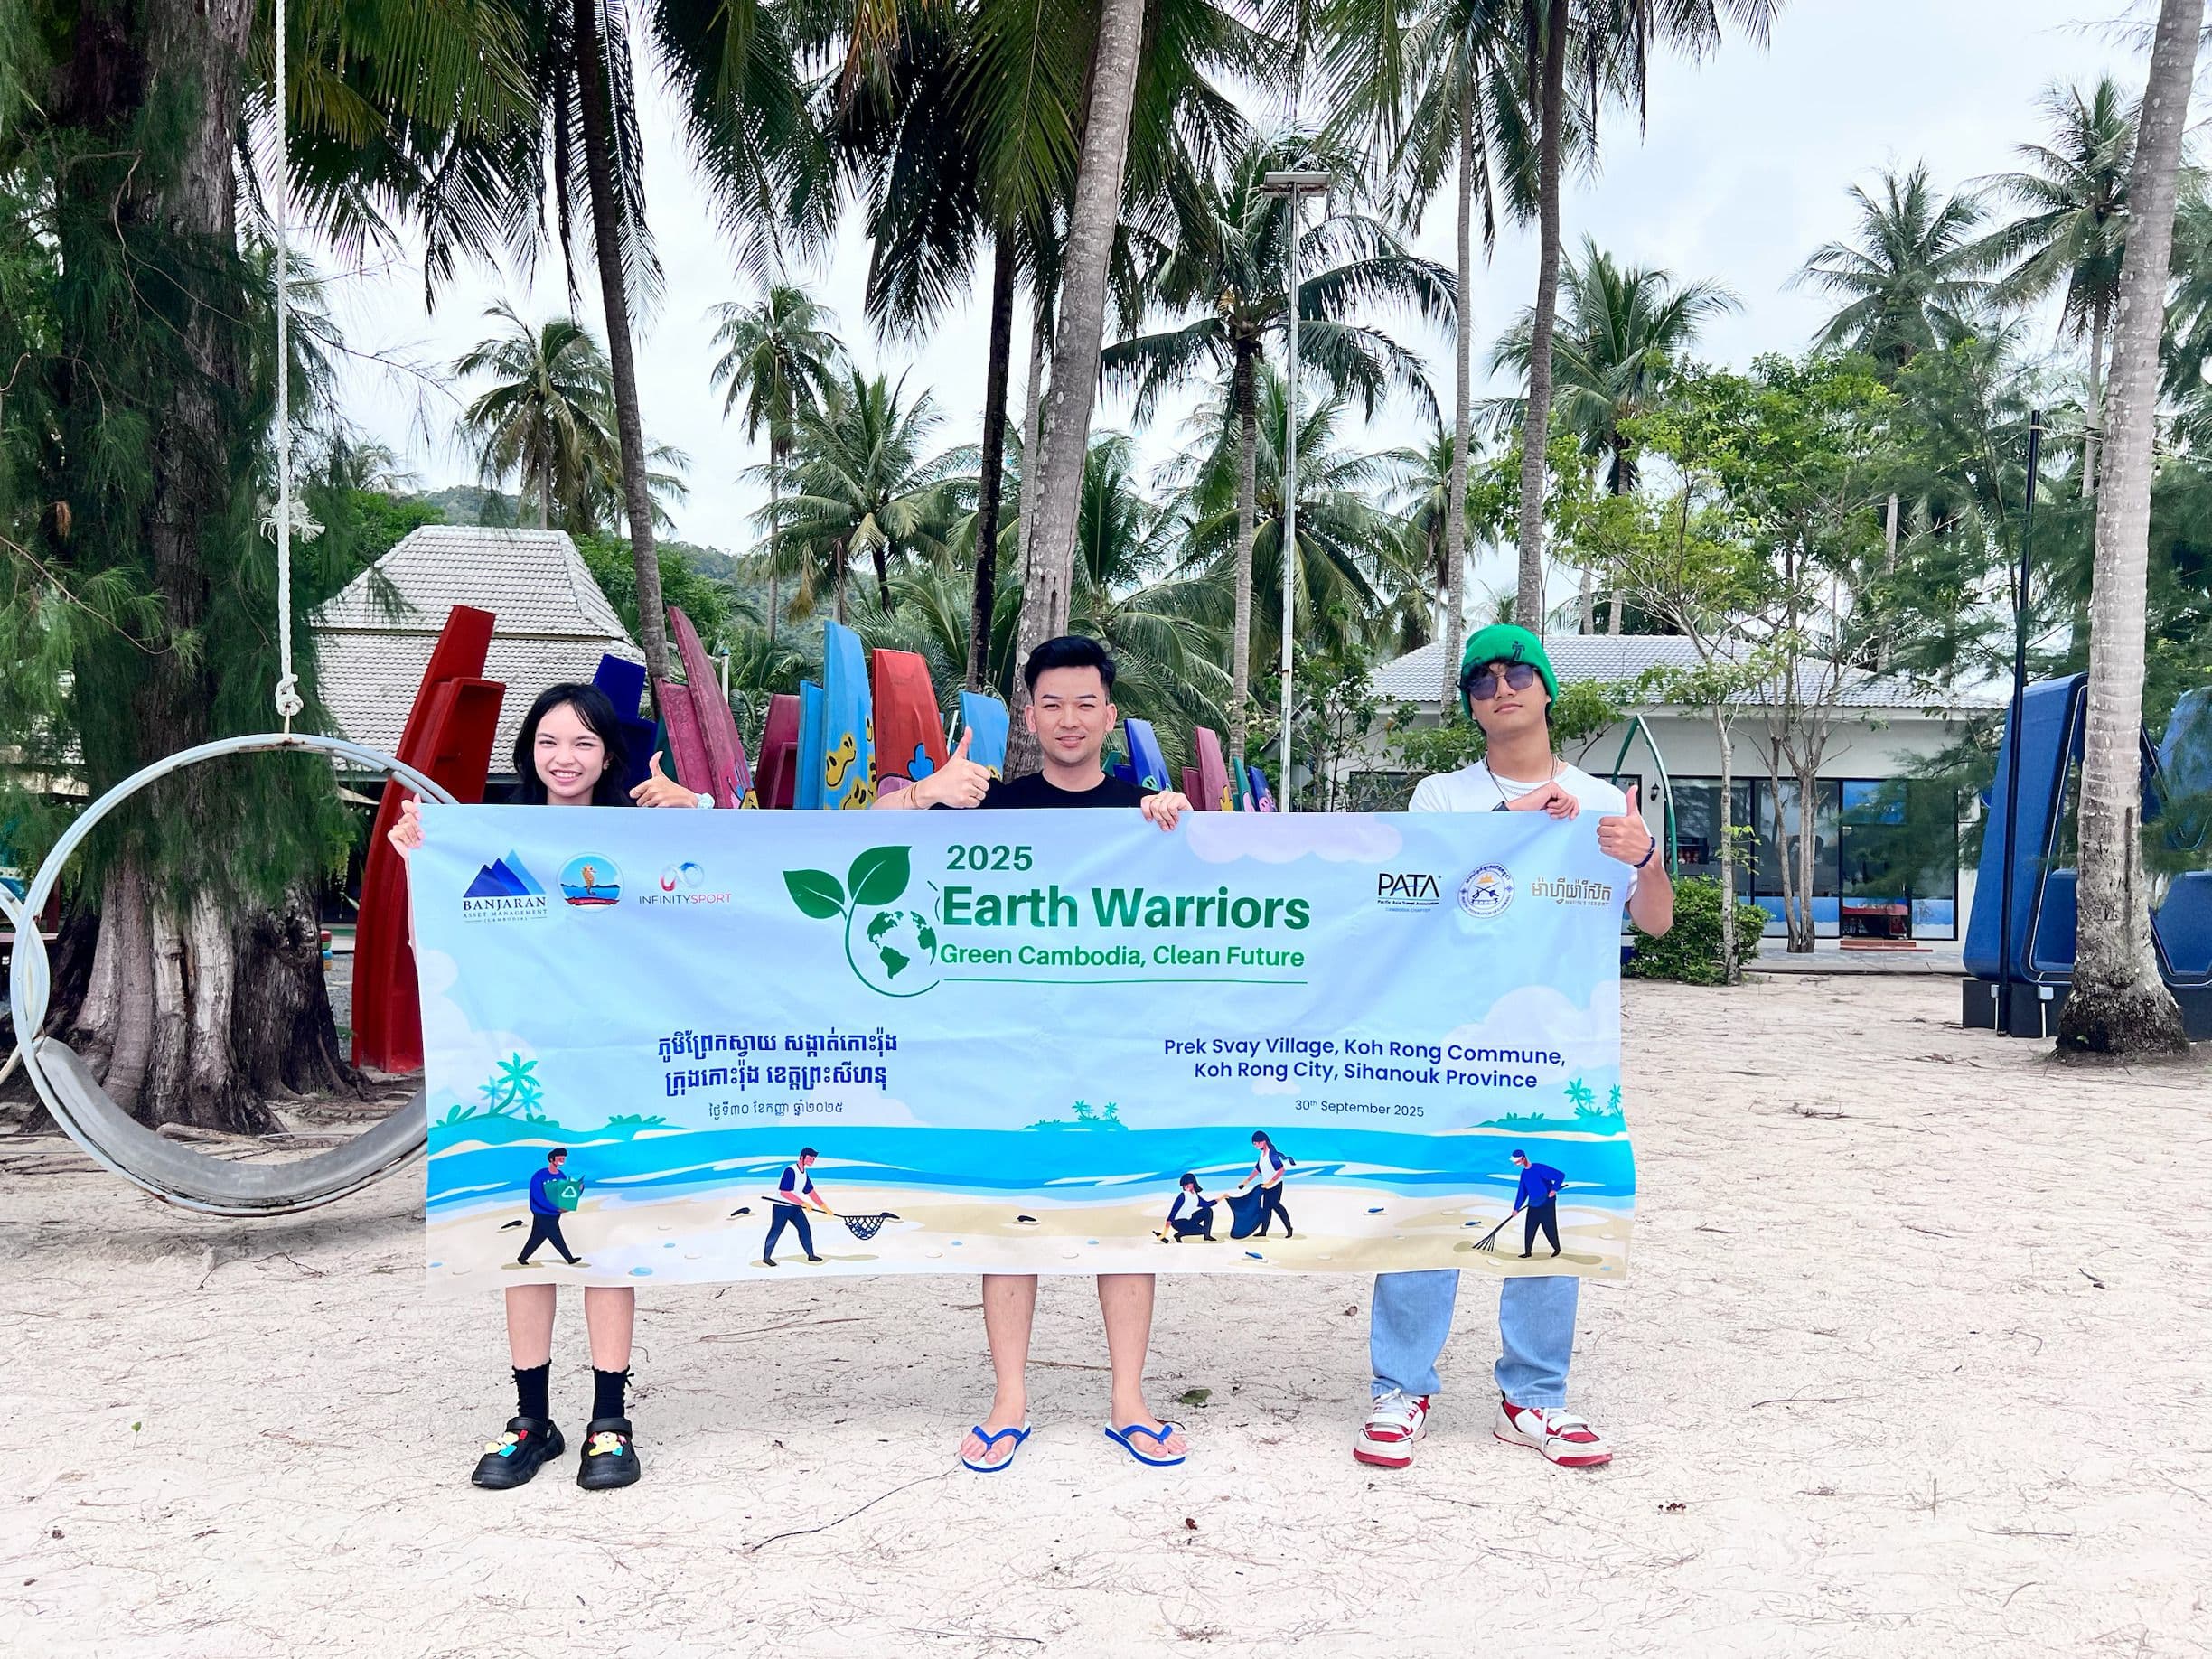
Earth Warriors Day 2025: Green Cambodia, Clean Future
Banjaran Asset Management (Cambodia) Plc. is proud to once again join Earth Warriors Day 2025 on 30th September in Koh Rong City, Sihanouk Province! As a sponsor of this meaningful cause, we are happy to committed to a Clean Cambodia, Clean Future — ensuring it remains a treasure for future generations. Together with fellow Earth Warriors, our team helped collect a total of 200 kg of waste, making a real impact in preserving the island’s natural beauty.
Market Outlook
2024 August Market Outlook: Yen Carry Trade Unwinds, Sparking Global Market Shifts
Early in August, equity markets experienced a sudden spike in volatility, where volatility reached levels unseen since the COVID-19 crash. This was caused by a significant unwinding of the Yen carry trade. The unwinding was triggered after the Bank of Japan (“BOJ”) unexpectedly raised interest rates, where a sharp appreciation in the Japanese Yen followed. Traders who borrowed Yen cheaply then had to sell off their investments to pay back their borrowings. The situation worsened when weaker-than-expected US employment data caused the greenback to depreciate further against the Yen. Shortly after the sharp market decline, the BOJ has given comfort to the public that they will not hike interest rates further while financial markets are unstable. Thus, we are of the opinion that as of now, the carry trade should not cause further volatility. We are cautiously optimistic about the market consolidation. The reason for the caution is due to the still high valuation of the broad US equity market despite increasingly slowing fundamentals and economic data. We will continue to watch near-term trends given that a broad recovery in equity markets normally results in bullish short-term sentiment.
2024 July, Market Outlook: Mixed Signals from China and Cautious Optimism in the US
China’s economic landscape continues to be buoyed by its manufacturing sector, while consumer spending remains notably sluggish. Recent data reveals that retail sales growth has fallen short of expectations, with the latest Q2 Gross Domestic Product (GDP) reading showing a deceleration to just 4.7% year-on-year. However, there are encouraging signs in the property market; easing measures on homebuying has resulted in a significant uptick in secondary property sales in tier-one cities, which jumped by double digits. While this early data is promising, we remain cautious. Our previous observations indicate that any increase in home sales following the significant relaxation of restrictions in 2023 was short-lived. Therefore, we will closely monitor the outcomes of the upcoming Third Plenary Session, which will shed light on the policies that will shape China’s economic future. In the United States, we maintain a cautious stance regarding the medium-term economic outlook. The deceleration in growth and rising unemployment trends have yet to raise alarms among investors, primarily due to the robust inflow of investments related to artificial intelligence. Over the long term, we believe that fiscal dominance will be a critical factor, as the Congressional Budget Office projects that debt-to-GDP ratios could soar from around 120% today to 200% within the next 30 years. This projection raises valid concerns about the sustainability of the US economy. However, we posit that the current status quo could persist longer than anticipated. History shows that attempts to time market peaks often lead to substantial opportunity costs. Thus, we will continue to invest in US firms while remaining vigilant about potential de-dollarization and long-term debt risks. Following recent testimonies from the Federal Reserve regarding their readiness to lower interest rates, combined with market expectations of a potential Donald Trump victory in the upcoming presidential election, we have witnessed a noticeable rotation into smaller-capitalization stocks. These stocks have underperformed the Standard & Poor’s 500 Index since the COVID-19 pandemic heavily impacted their operations. Market sentiment seems to be favoring a "no landing" scenario, where small businesses could benefit more from lower borrowing costs and increased fiscal spending compared to larger firms. However, we approach this sector with caution, particularly concerning smaller companies that have significant debt exposure, given our apprehensions about a global slowdown in demand. In conclusion, while China shows signs of resilience through its manufacturing sector and initial recoveries in property sales, the broader economic outlook remains mixed, requiring careful observation of forthcoming policy changes. Meanwhile, the US market, bolstered by AI investments and potential shifts in fiscal policy, is experiencing volatility as investors reassess their strategies in light of evolving economic indicators. As we navigate these complexities, our focus remains on identifying solid investment opportunities while balancing risks in an uncertain environment.
2024 June, Market Outlook: Semiconductor Surge, Fed Caution, and AI's Future Potential
The equity markets have continued to reach new highs, largely driven by the exceptional outperformance of semiconductor stocks. This concentrated movement suggests that investors are placing heavy bets on a few sectors, which may indicate underlying caution about the broader economy. While the semiconductor sector's growth has been impressive, this narrow market rally could be vulnerable to shifts in sentiment, making it essential for investors to stay vigilant. On the macroeconomic front, the US Federal Reserve has remained cautious, withholding any strong indication of interest rate cuts in the near term. Citing robust employment numbers and persistently high inflation, the Fed has expressed that it needs to see more data before making any moves. As businesses and consumers have so far shown resilience, many market analysts have pushed back their expectations of a potential recession. However, there are signs of softening in the labor market, with the US unemployment rate gradually climbing to 4%, up from a low of 3.4% in 2023. This could be a precursor to broader economic weakness, aligning with our view that the Fed may have room for at least one interest rate cut later this year. China’s market performance, by contrast, has started to lag after the initial wave of optimism following the government’s policy interventions aimed at stabilizing the property market. Profit-taking has emerged as a natural response to the sharp upward momentum in Chinese equities earlier in the year. While market participants are now in a holding pattern, awaiting further updates on the property industry, we maintain the view that China’s real estate challenges are unlikely to result in systemic risk. The Chinese government has shown a clear commitment to managing the situation and is expected to introduce further targeted measures as needed. In the technology sector, we are particularly optimistic about the long-term productivity gains that could arise from AI applications. For example, a recent study found that software developers using Microsoft's GitHub CoPilot—an AI-powered coding assistant—completed tasks up to 56% faster than those without the tool. This significant efficiency boost highlights the transformative potential of AI in the workplace. Expectations for AI are sky-high, with investment in hyperscalers projected to grow at an annual rate of at least 20% through 2030. While AI-driven automation in areas such as customer service, email summarization, and image generation is expected to yield cost savings, we believe the next major economic leap will come from advancements toward Artificial General Intelligence (AGI). Current generative AI models have made substantial progress in recent years but are still limited by their inability to adapt effectively when faced with queries outside their training data. The evolution toward AGI would address this limitation, enabling AI to perform a broader range of tasks with greater accuracy and versatility. Additionally, consumer applications of AI are somewhat constrained at present, as mobile hardware lacks the processing power needed to run AI-driven tasks efficiently. However, the sustained investment in AI technologies is already leading to rapid improvements, and we continue to monitor developments for potential investment opportunities as companies push the boundaries of innovation and find new ways to monetize AI advancements. In summary, while semiconductor stocks have driven much of the equity market gains in 2024, a cautious stance is warranted due to the concentration of market activity. The Fed's hesitance to cut rates amid a weakening labor market adds another layer of complexity. Meanwhile, China's property market stabilization efforts are ongoing, and AI’s long-term promise continues to excite, but its full potential may take years to materialize. As we navigate these shifting dynamics, we remain focused on identifying selective opportunities across sectors and regions.
2024 May, Market Outlook: Navigating Global Volatility and Strategic Opportunities
Global equity markets have staged a strong recovery from April's decline, buoyed by cooling US economic data and a wave of significant share buyback programs. We anticipate that this erratic market behavior will persist until there's more certainty regarding the timing of interest rate cuts, as investors eagerly respond to any hints of monetary easing. With the US elections approaching, we also expect heightened volatility as uncertainty around future government policies grows. In China, the government has taken direct action to restore confidence in the property sector. Restrictions on home-buying have been fully lifted in major cities like Xi’an, Hangzhou, and Chengdu, with further easing measures introduced elsewhere. More notably, the administration has launched a 300 billion RMB facility for local governments to acquire excess property inventory and convert it into affordable housing. This initiative has been well-received by market participants, leading to sharp price appreciation in China’s equity markets. However, we believe that for the facility to have a meaningful impact on the broader property sector, it will likely need to be expanded further. If these efforts are scaled up, property prices could stabilize, and consumer confidence may return. In addition, the Chinese government’s push for large-scale equipment renewals and trade-ins of durable consumer goods is aimed at boosting private consumption growth over the next few years. Other recent measures, such as removing mortgage rate floors and lowering downpayment rates, further signal China's commitment to supporting its economy. As Q1 earnings season concludes, we’ve observed mixed results from major US corporations. Consumer discretionary firms report slowing spending and a more selective consumer base, while companies with international exposure have commented on a slower-than-expected recovery from Chinese consumers. In contrast, US technology firms have maintained robust growth, particularly those benefiting from AI adoption. In China, a similar trend emerges: technology firms are expanding, while consumer spending remains tepid in most sectors. However, China's consumer base is on an upward trajectory, whereas the US is seeing a slowdown. Given the potential turning points in major global economies, we plan to be highly selective in both US and Chinese markets based on our current exposures. While economic data in Japan remains weak, we remain optimistic about the ongoing corporate governance reforms, which we believe will drive improved shareholder returns over the long term. Looking ahead, we remain focused on navigating these uncertainties and positioning ourselves to take advantage of selective opportunities in the evolving market landscape.
2024 April, Market Outlook: Navigating Volatility Amidst Inflation, Interest Rates, and Geopolitical Risks
Recently, both the bond and stock markets have experienced heightened volatility, driven by inflation and retail sales in the US consistently exceeding expectations. In response, the Federal Reserve once again opted to hold off on lowering interest rates, waiting for more comprehensive data before making further policy decisions. This cautious approach led investors to adjust their interest rate forecasts aggressively, which directly impacted equity markets. We believe these concerns are justified, especially as commodity prices have surged, potentially contributing to higher inflation in the months ahead. At present, we assess that the recent equity price movements may be a short-term reaction to rising bond yields, and we will continue to monitor these trends closely. In China, the government's initiative to support "whitelist" property projects has made significant progress, with funds raised reaching RMB 469 billion by the end of March—more than double the RMB 200 billion previously reported. Given the size of China’s residential property sector, we anticipate further substantial disbursements. Additionally, there is an expectation that the People’s Bank of China will gradually increase government bond trading through its open market operations, signaling a form of monetary policy easing. These developments, along with China's Q1 GDP growth and improved PMI numbers, offer positive signals for the economy. However, we recognize initial signs of a slowdown in key economic indicators, such as retail sales and industrial production, reflecting lingering sluggishness in the domestic economy. We will continue to track these factors in the coming months. On the geopolitical front, tensions between Iran and Israel are escalating, with Israel considering its response to recent drone strikes by Iran. This situation could significantly impact crude oil prices, introducing further inflationary risks in the near term. Meanwhile, the ongoing US-China tensions remain a long-term issue. Recently, US lawmakers introduced a bill that would bar mutual funds from investing in indices that include Chinese stocks. This follows a broader trend of global portfolio allocations shifting away from China over the past year. As a result, we have observed a substantial valuation premium in the US market relative to China, far exceeding historical norms. We believe that once the Chinese economy stabilizes and returns to sustainable growth, this valuation gap may narrow. In the near term, inflationary risks in the US and uncertainty in China could present challenges for equity markets. However, our analysis of current data suggests that this may be a temporary correction, largely driven by high valuations in developed markets. We remain focused on identifying attractive opportunities as they emerge in the evolving market landscape.
2024 March, Market Outlook: Navigating Elevated Interest Rates, China’s Economic Measures, and Corporate Earnings
Throughout the month, the Federal Reserve reinforced its stance that there is no urgency to lower interest rates during the first half of 2024. Notably, the Fed addressed growing concerns within the commercial real estate sector, acknowledging that while the situation remains manageable for now, it may lead to further banking failures. This dovetails with our cautious outlook on the potential consequences of keeping interest rates elevated for too long, especially if policy missteps occur. High rates for an extended period could stress certain sectors, particularly real estate, heightening risks within financial markets. In China, the government has begun to take action to support previously announced “whitelist” property projects. Major commercial banks have approved over RMB 200 billion in loans to facilitate the completion of these projects. While this is a positive step, further financing will likely be necessary to ensure sufficient liquidity for the real estate sector's recovery. We will continue to monitor further policy announcements and their impact on property sales and prices in the coming months. The recently concluded "Two Sessions" meeting of the Chinese Communist Party revealed economic targets similar to those set last year. The 5.0% GDP growth target for 2024 appears ambitious, especially in light of the modest 3.0% deficit target and the conservative spending habits of Chinese consumers. However, we believe this growth target is achievable, given the gradual shift in consumer behavior towards increased spending. Furthermore, growth outside of the real estate sector remains robust, offering a positive outlook for broader economic recovery. In the corporate world, recent earnings reports from leading companies have generally shown strong growth for Q4 2023, with some projecting modest top-line expansion in 2024. However, US stocks that missed earnings expectations and guidance experienced sharp declines, a consequence of their elevated valuations. Given the uncertain economic outlook, we will closely monitor both economic and industry-specific data to inform our next portfolio decisions. Despite these short-term uncertainties, we remain positive about the long-term potential of our holdings. In conclusion, as central banks maintain a cautious stance on interest rates and China accelerates its economic support, global markets face a delicate balancing act in 2024. Careful navigation through these challenges will be key for investors seeking sustainable growth opportunities.