

Insights
Explore the latest news, expert articles, and market outlooks to stay ahead of industry trends.
Newsroom
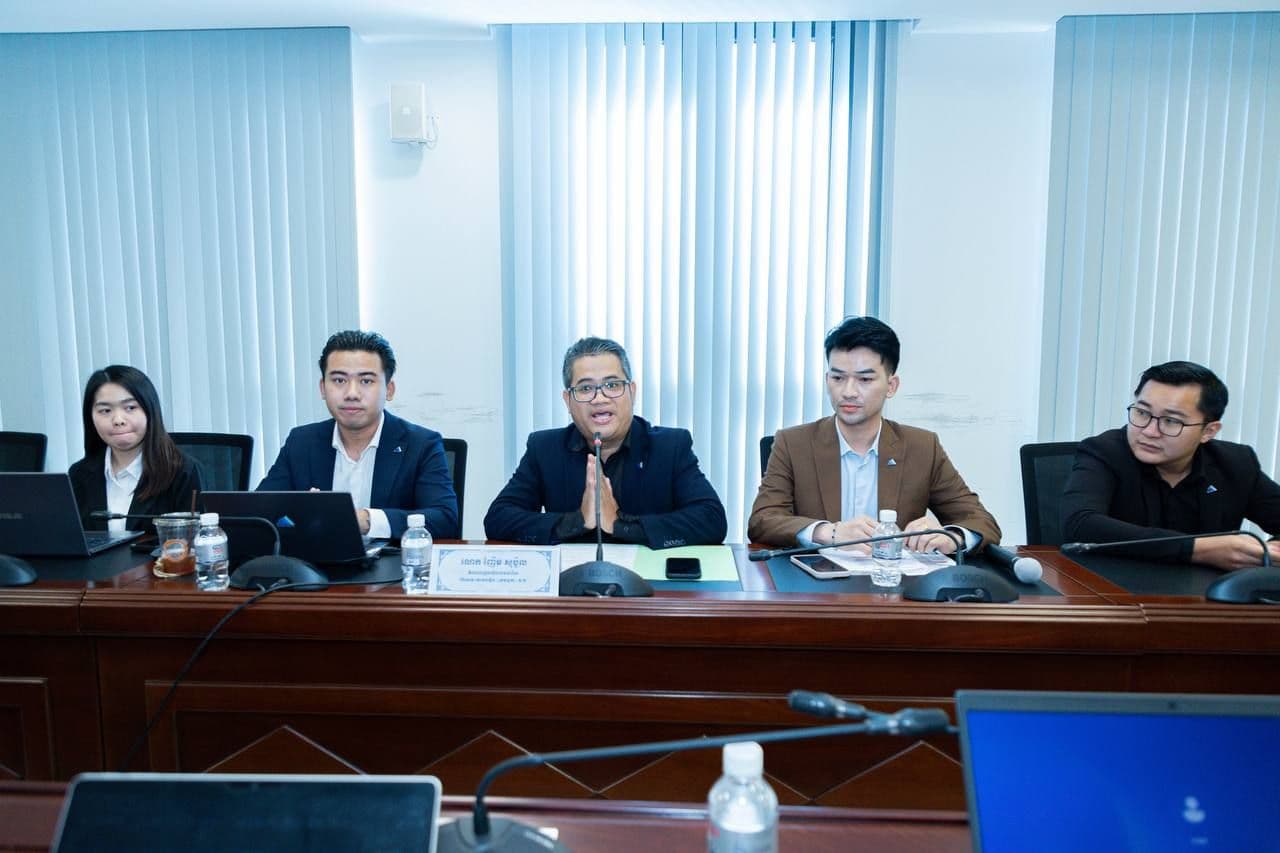
Banjaran AMC Conducts Second CIS Training Session for NSSF Officers and Staff
On the afternoon of 6 November 2026, under the direction of the management of Banjaran Asset Management (Cambodia) Plc., Mr. Nhem Sopaul, Head of Corporate Affairs, led a team from the Company in conducting the second training session on “Collective Investment Schemes (CIS)” for the officers and staff of the National Social Security Fund (NSSF) on 6 November 2026. During the training session, Mr. Sok Chantola, Sales & Marketing Deputy Manager; Mr. Taing Hoy, Internal Audit Senior Executive; and Mr. Veasna Monireach, Operation Senior Executive, delivered presentations on “Introduction to Banjaran AMC & CIS Landscape”, “BAMC Asia Equity Fund (BAEF)”, and “Investment Strategy & Key Value of Banjaran AMC”. The presentations provided participants with a better understanding of collective investment schemes, the Fund's investment approach, and the key values of Banjaran AMC. The training was organized to enhance participants' understanding of CIS, introduce the investment opportunities offered through BAEF, and raise awareness of investment funds and the development of Cambodia's capital market. Banjaran Asset Management (Cambodia) Plc. remains committed to promoting financial literacy, sharing investment knowledge, and contributing to the development of Cambodia's capital market through educational initiatives and knowledge-sharing activities.
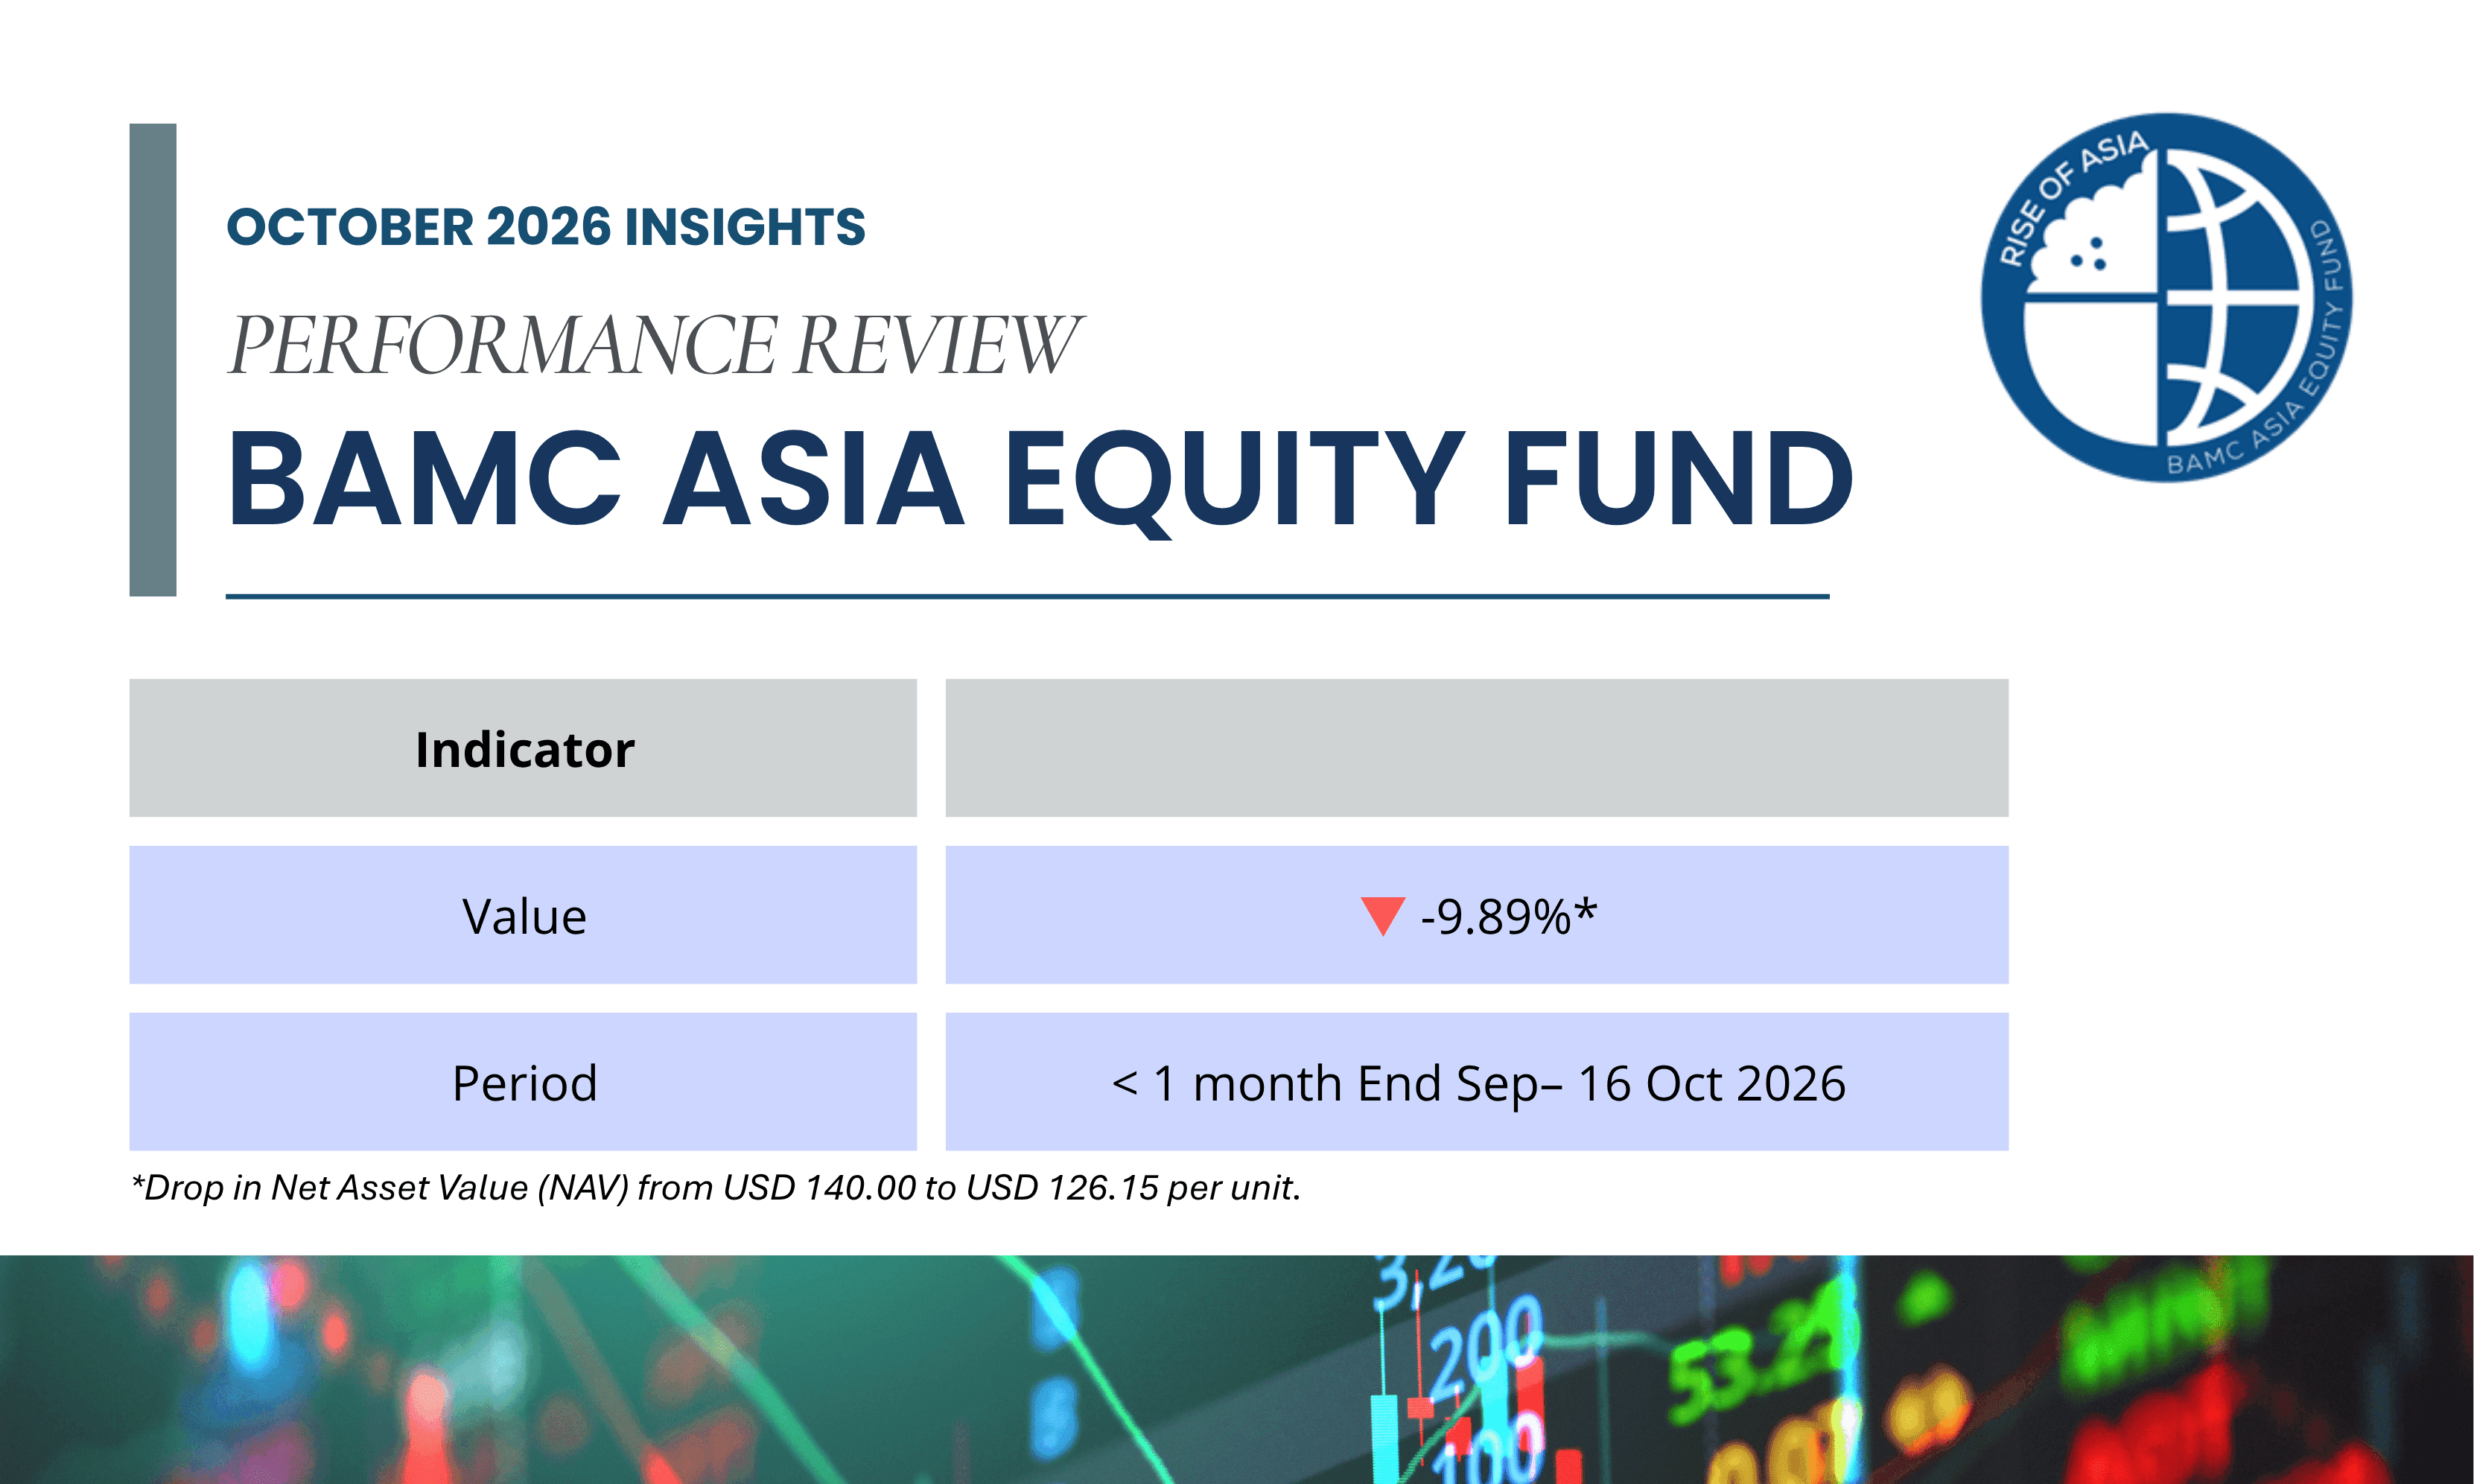
BAMC Asia Equity Fund (BAEF) Performance as of 16 October 2026
Markets in October Since end September, global equities have faced pressure from higher borrowing costs and growing scrutiny of the returns from AI related spending. Stronger than expected US inflation reinforced expectations of further Federal Reserve tightening, weighing particularly on technology and semiconductor valuations. Elevated oil prices added further pressure on inflation concerns. Overall, technology-heavy Asian markets bore a greater share of the selling in October’s global tech weakness. Our exposure to Asian equities reflects our focus on the region’s long-term growth opportunities. Short-term volatility is an inherent risk of this approach, but our investment decisions remain anchored in companies’ fundamentals and their potential to generate sustainable returns over time. Portfolio underperformance Against this backdrop, BAEF’s main drag was its concentration in Korean and Taiwanese equities and semiconductor related holdings, which together accounted for 32.3% of the portfolio and approximately 4% of the calculated drag. The Korea ETF and Samsung alone contributed roughly 2%. Korea was particularly affected by the unwinding of AI-related positions. On 15 October, its benchmark equity index fell approximately 8%. Samsung’s weakness came despite guidance for a substantial increase in third-quarter operating profit, suggesting that concerns over valuations, financing conditions and competition outweighed the near-term earnings improvement. The drop was compounded by sharp falls in several Singapore small caps and financials. Addvalue fell 22.9%, UOB Kay-Hian 25.2%, OCBC 10.3%. OCBC faced a specific catalyst when Citi downgraded the stock from “neutral” to “sell”, citing risks to third-quarter earnings, pressure on net interest margins from higher deposit costs, and the potential normalisation of exceptionally strong first-half wealth-related income. Addvalue’s share price weakness is due to profit-taking after a strong run. Singapore’s semiconductor-related suppliers to chipmakers fell harder than the larger chipmakers; Frencken fell 14.9%, UMS 14.8% and AEM 9.9%. Together, these holdings constituted approximately 14% of the portfolio and implied another 2.3% of drag. Like the global technology sell-off, broader concerns over the AI investment cycle were weighing on sentiment beyond individual companies’ reported performance. There were few meaningful offsets in the portfolio as gains elsewhere were insufficient to counter the losses. Why we still hold these stocks Despite the recent weakness, we retain these holdings because the underlying earnings drivers remain relevant to our investment horizon. The sell-off has weakened share prices more than the underlying medium- to long-term investment case. In semiconductors, the correction has coincided with continued growth in demand for AI compute. TSMC’s latest results and guidance pointed to sustained demand for advanced chips, while Samsung’s earnings guidance reflected stronger memory sales and pricing. These developments support maintaining exposure to the sector, although we recognise that strong operating performance does not eliminate valuation risk or the possibility of further share price volatility. Our Singapore semiconductor holdings provide exposure to different parts of this investment cycle. UMS benefits from equipment demand and increasing exposure to advanced packaging, AEM offers participation in increasingly complex semiconductor testing, and Frencken provides a more diversified manufacturing exposure. The rationale for retaining these positions rests on their prospective earnings as customers invest in additional capacity and advanced chip architectures, rather than an expectation that all semiconductor-related stocks will recover together. For the financial holdings, recent operating results provide a basis for distinguishing share price weakness from deterioration in the businesses. OCBC’s wealth-management and other non-interest income have helped offset pressure on lending margins, while its capital position continues to support business growth and distributions. UOB Kay Hian reported substantially higher first-half earnings, supported by stronger trading activity, commission income and interest income. We retain exposure to these earnings streams, while recognising that wealth related revenue and brokerage activity are market sensitive and that recent growth rates may not persist. We retain exposure to Addvalue to the long-term growth in satellite connectivity and space infrastructure. Recent share-price weakness appears to reflect, in part, profit-taking following a strong rally, while continued orders support the underlying growth outlook. In september, Addvalue announced US$15 million of new orders across its space connectivity and advanced digital radio business, bringing its order book to US$20.2 million. Converting these orders into earnings and cash flow remains central to our investment case. Overall, we remain selective and view the decline as a potential opportunity to top up positions rather as a reason to hold every position unchanged. Continued ownership must be supported by company fundamentals, an acceptable valuation, and grounded in earnings growth. Moving forward Looking ahead, we intend to increase exposure to quality large-cap and blue-chip companies to strengthen portfolio resilience amid continued volatility. We will prioritise businesses with sound balance sheets, sustainable earnings and cash flows, and durable competitive advantages. Further market weakness could provide opportunities to build positions at more attractive entry prices, while maintaining a disciplined approach to valuation. Disclaimer : This Document is issued for information and investor awareness purposes only to explain the factors contributing to the changes in BAEF’s NAV. It does not constitute investment advice, an investment recommendation, an offer, or a solicitation to buy, sell, or hold units of BAEF. The information provided herein should not be relied upon as the sole basis for any investment decision and does not guarantee future performance. Investors should refer to the Fund’s official offering documents and disclosures and carefully assess their own investment objectives and risk tolerance before making any investment decision.
Banjaran AMC and ACLEDA Securities Host Golden Securities Investment Workshop in Chbar Ampov
Banjaran Asset Management (Cambodia) Plc. in collaboration with ACLEDA Securities Plc. and the ACLEDA Bank Plc. Local Branch (Khan Chbar Ampov – Sangkat Chbar Ampov Ti Muoy), successfully hosted the Workshop on “Golden Securities Investment Opportunities” as part of the 3rd Round Roadshow. The workshop was held at the meeting hall of ACLEDA Bank Plc. Local Branch (Khan Chbar Ampov – Sangkat Chbar Ampov Ti Muoy) on the morning of 12 September 2026. The workshop aimed to enhance public understanding of capital market investments and the BAMC Asia Equity Fund (BAEF), a Collective Investment Scheme (CIS). We sincerely appreciate the support of our partners and the active participation of all attendees. Special thanks to Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc. on the topic “BAMC Asia Equity Fund (BAEF)”. We look forward to welcoming you to our upcoming events. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial
Banjaran AMC Brings BAEF Investment Opportunities to Investors in Phnom Penh Through 3rd Round Roadshow
Banjaran Asset Management (Cambodia) Plc. in collaboration with ACLEDA Securities Plc. and ACLEDA Bank Plc. Local Branch, (Khan Mean Chey, Sangkat Boeng Tumpun 01), successfully hosted the Workshop on “Golden Securities Investment by Opportunities” as part of the 3rd Round Roadshow. The workshop was held at the meeting hall of ACLEDA Bank Plc. Local Branch, (Khan Mean Chey, Sangkat Boeng Tumpun 01) on the morning of 05 September 2026. The workshop aimed to enhance public understanding of capital market investments and the BAMC Asia Equity Fund (BAEF), a Collective Investment Scheme (CIS). We sincerely appreciate the support of our partners and the active participation of all attendees. Special thanks to Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc. on the topic “BAMC Asia Equity Fund (BAEF)”. We look forward to welcoming you to our upcoming events. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial
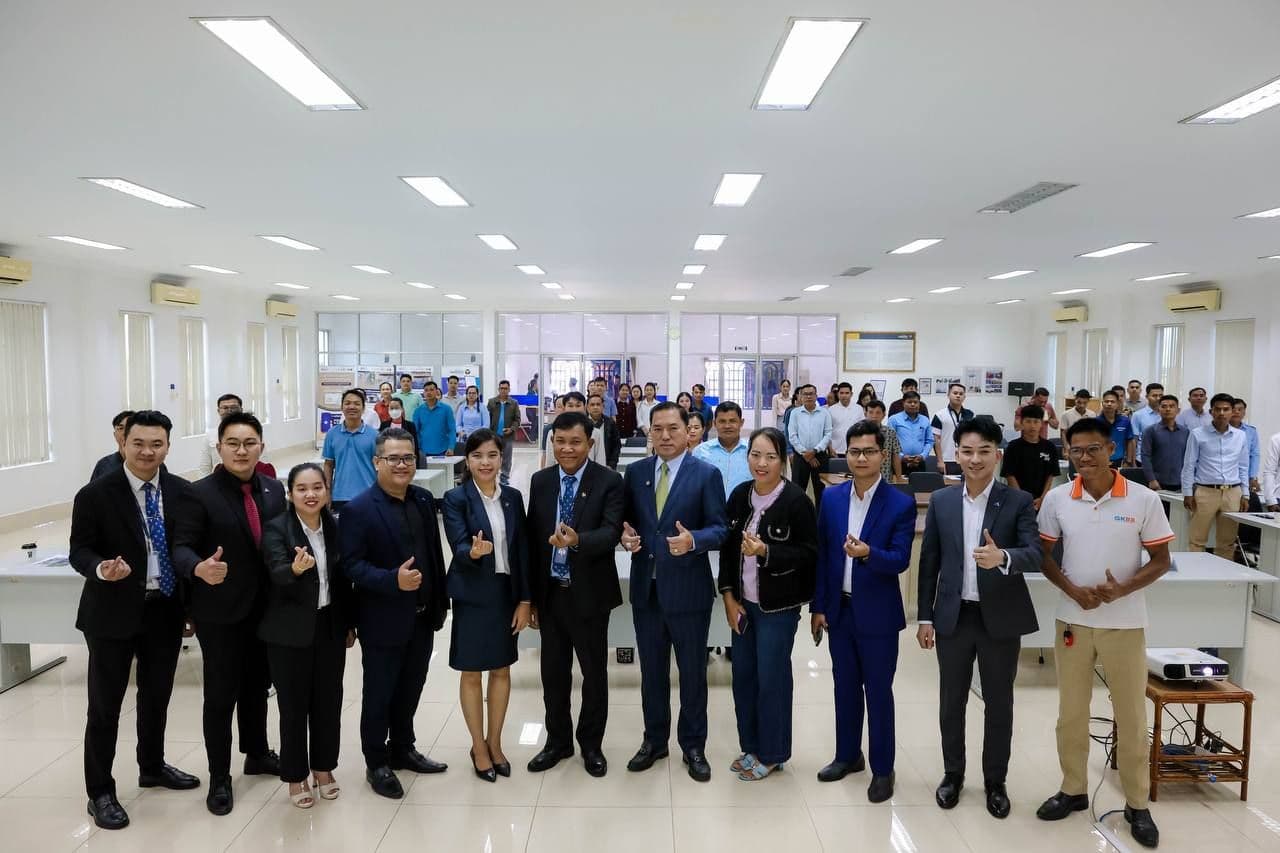
Banjaran AMC Expands Securities Investment Awareness Through 3rd Round Roadshow in Svay Rieng
Banjaran Asset Management (Cambodia) Plc., in collaboration with ACLEDA Securities Plc., and ACLEDA Bank Plc. Local Branch (Svay Rieng Province), successfully hosted the Workshop on “Golden Securities Investment by Opportunities” as part of the 3rd Round Roadshow. The workshop was held at the meeting hall of ACLEDA Bank Plc. Local Branch (Svay Rieng Province) on the morning of 22 August 2026. The workshop aimed to enhance public understanding of capital market investments and the BAMC Asia Equity Fund (BAEF), a Collective Investment Scheme (CIS). We sincerely appreciate the support of our partners and the active participation of all attendees. Special thanks to Mr. Taing Hoy, Legal and Compliance Officer of Banjaran Asset Management (Cambodia) Plc., on the topic “Investment Value and Benefits of the BAMC Asia Equity Fund (BAEF)”. We look forward to welcoming you to our upcoming events. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial
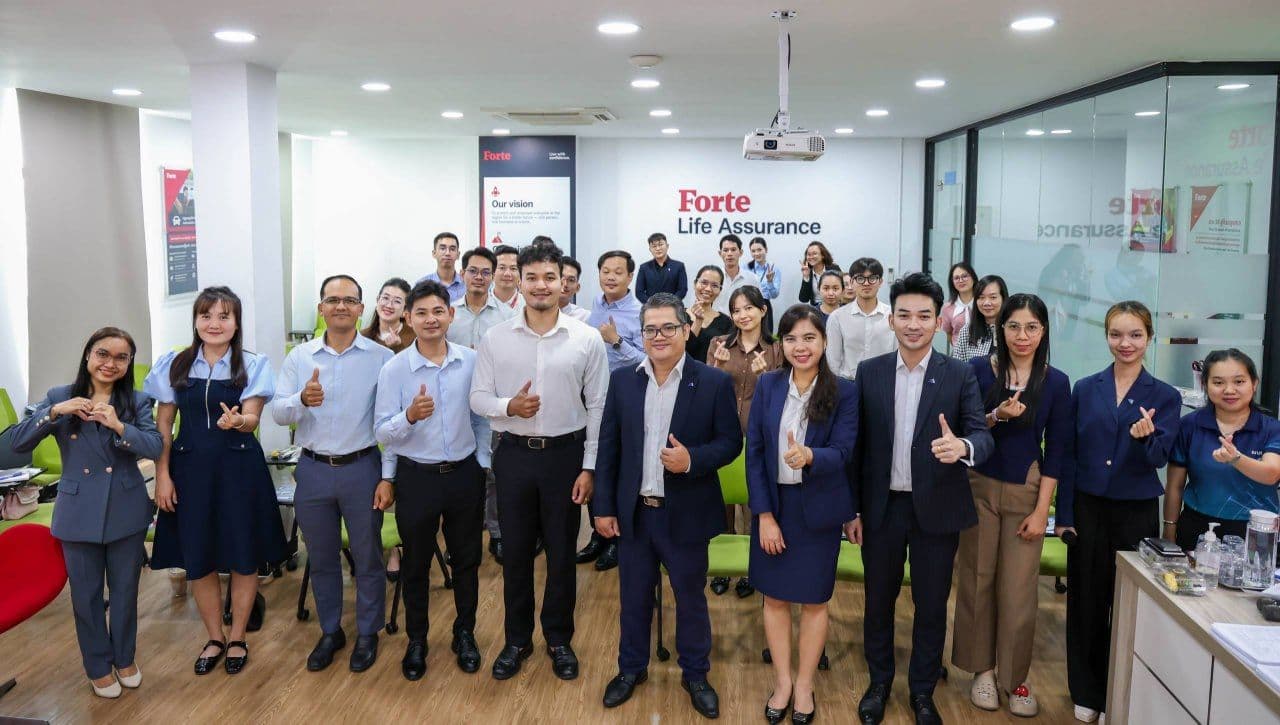
Banjaran AMC Strengthens Strategic Partnership with Forte Through BAEF Investment Workshop
Banjaran Asset Management (Cambodia) Plc., in collaboration with ACLEDA Securities Plc., successfully organized a workshop on “Golden Investment Opportunities in Securities Sector” for the Management team and staff of Forte General Insurance Plc., and Forte Life Assurance Plc., on 19 August 2026 at Forte Office, One Park Tower. The workshop provided participants with valuable insights into the BAMC Asia Equity Fund (BAEF), including its key features, investment strategy, and the opportunities available through investing in a professionally managed fund licensed by the Securities and Exchange Regulator of Cambodia (SERC). During the session, Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc., delivered a presentation on “Investment Value and Benefits of the BAMC Asia Equity Fund (BAEF)”, sharing knowledge on investment opportunities and the benefits of BAEF as part of Cambodia’s growing securities sector. This workshop marks another important milestone under the Strategic Partnership between Banjaran Asset Management (Cambodia) Plc., ACLEDA Securities Plc., Forte General Insurance Plc., and Forte Life Assurance Plc., with the aim of enhancing investment awareness, strengthening collaboration, and creating opportunities for future business growth. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial
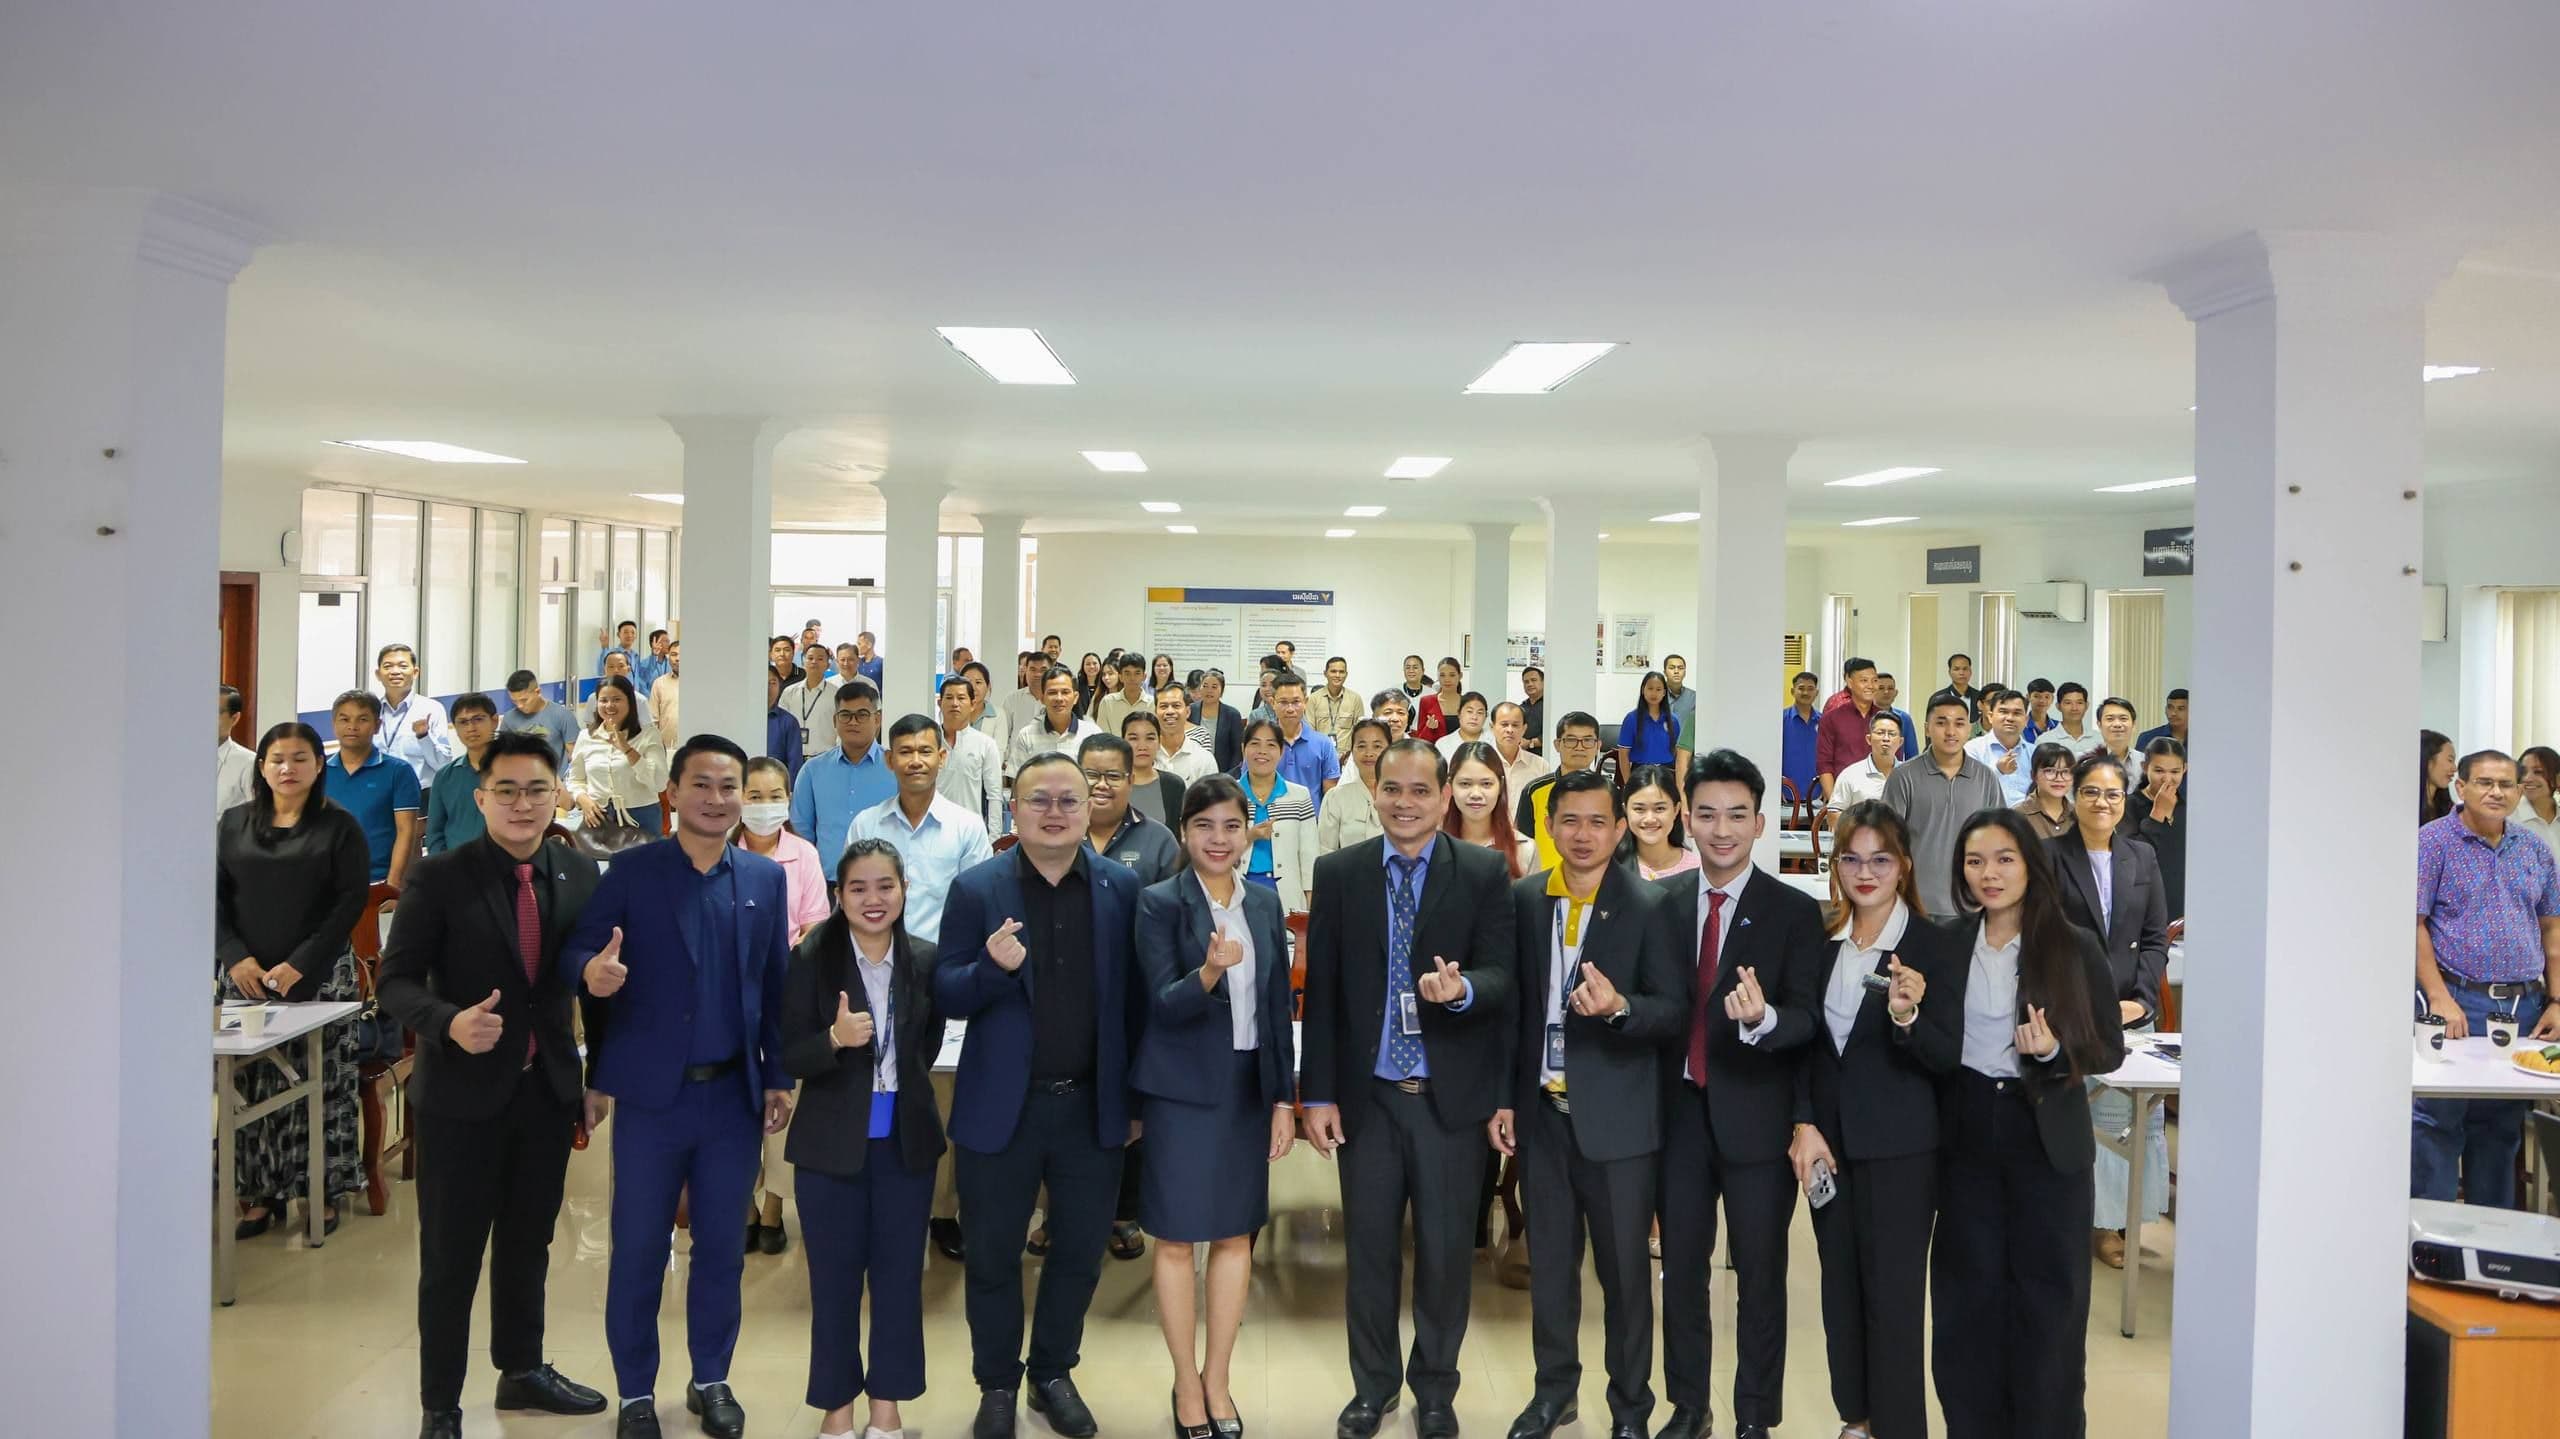
Banjaran AMC Advances BAEF Investment Awareness Through 3rd Round Roadshow in Siem Reap
Banjaran Asset Management (Cambodia) Plc., in collaboration with ACLEDA Securities Plc., ACLEDA Bank Plc. Local Branch (Krong Siem Reap, Sangkat Sla Kram), and ACLEDA Bank Plc. Local Branch (Krong Siem Reap, Sangkat Svay Dankum), successfully hosted the Workshop on “Golden Securities Investment by Opportunities” as part of the 3rd Round Roadshow. The workshop was held at the meeting hall of ACLEDA Bank Plc. Local Branch (Krong Siem Reap, Sangkat Sla Kram) on the morning of 15 August 2026. The workshop aimed to enhance public understanding of capital market investments and the BAMC Asia Equity Fund (BAEF), a Collective Investment Scheme (CIS). We sincerely appreciate the support of our partners and the active participation of all attendees. Special thanks to Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc., on the topic “Investment Value and Benefits of the BAMC Asia Equity Fund (BAEF)”. We look forward to welcoming you to our upcoming events. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial
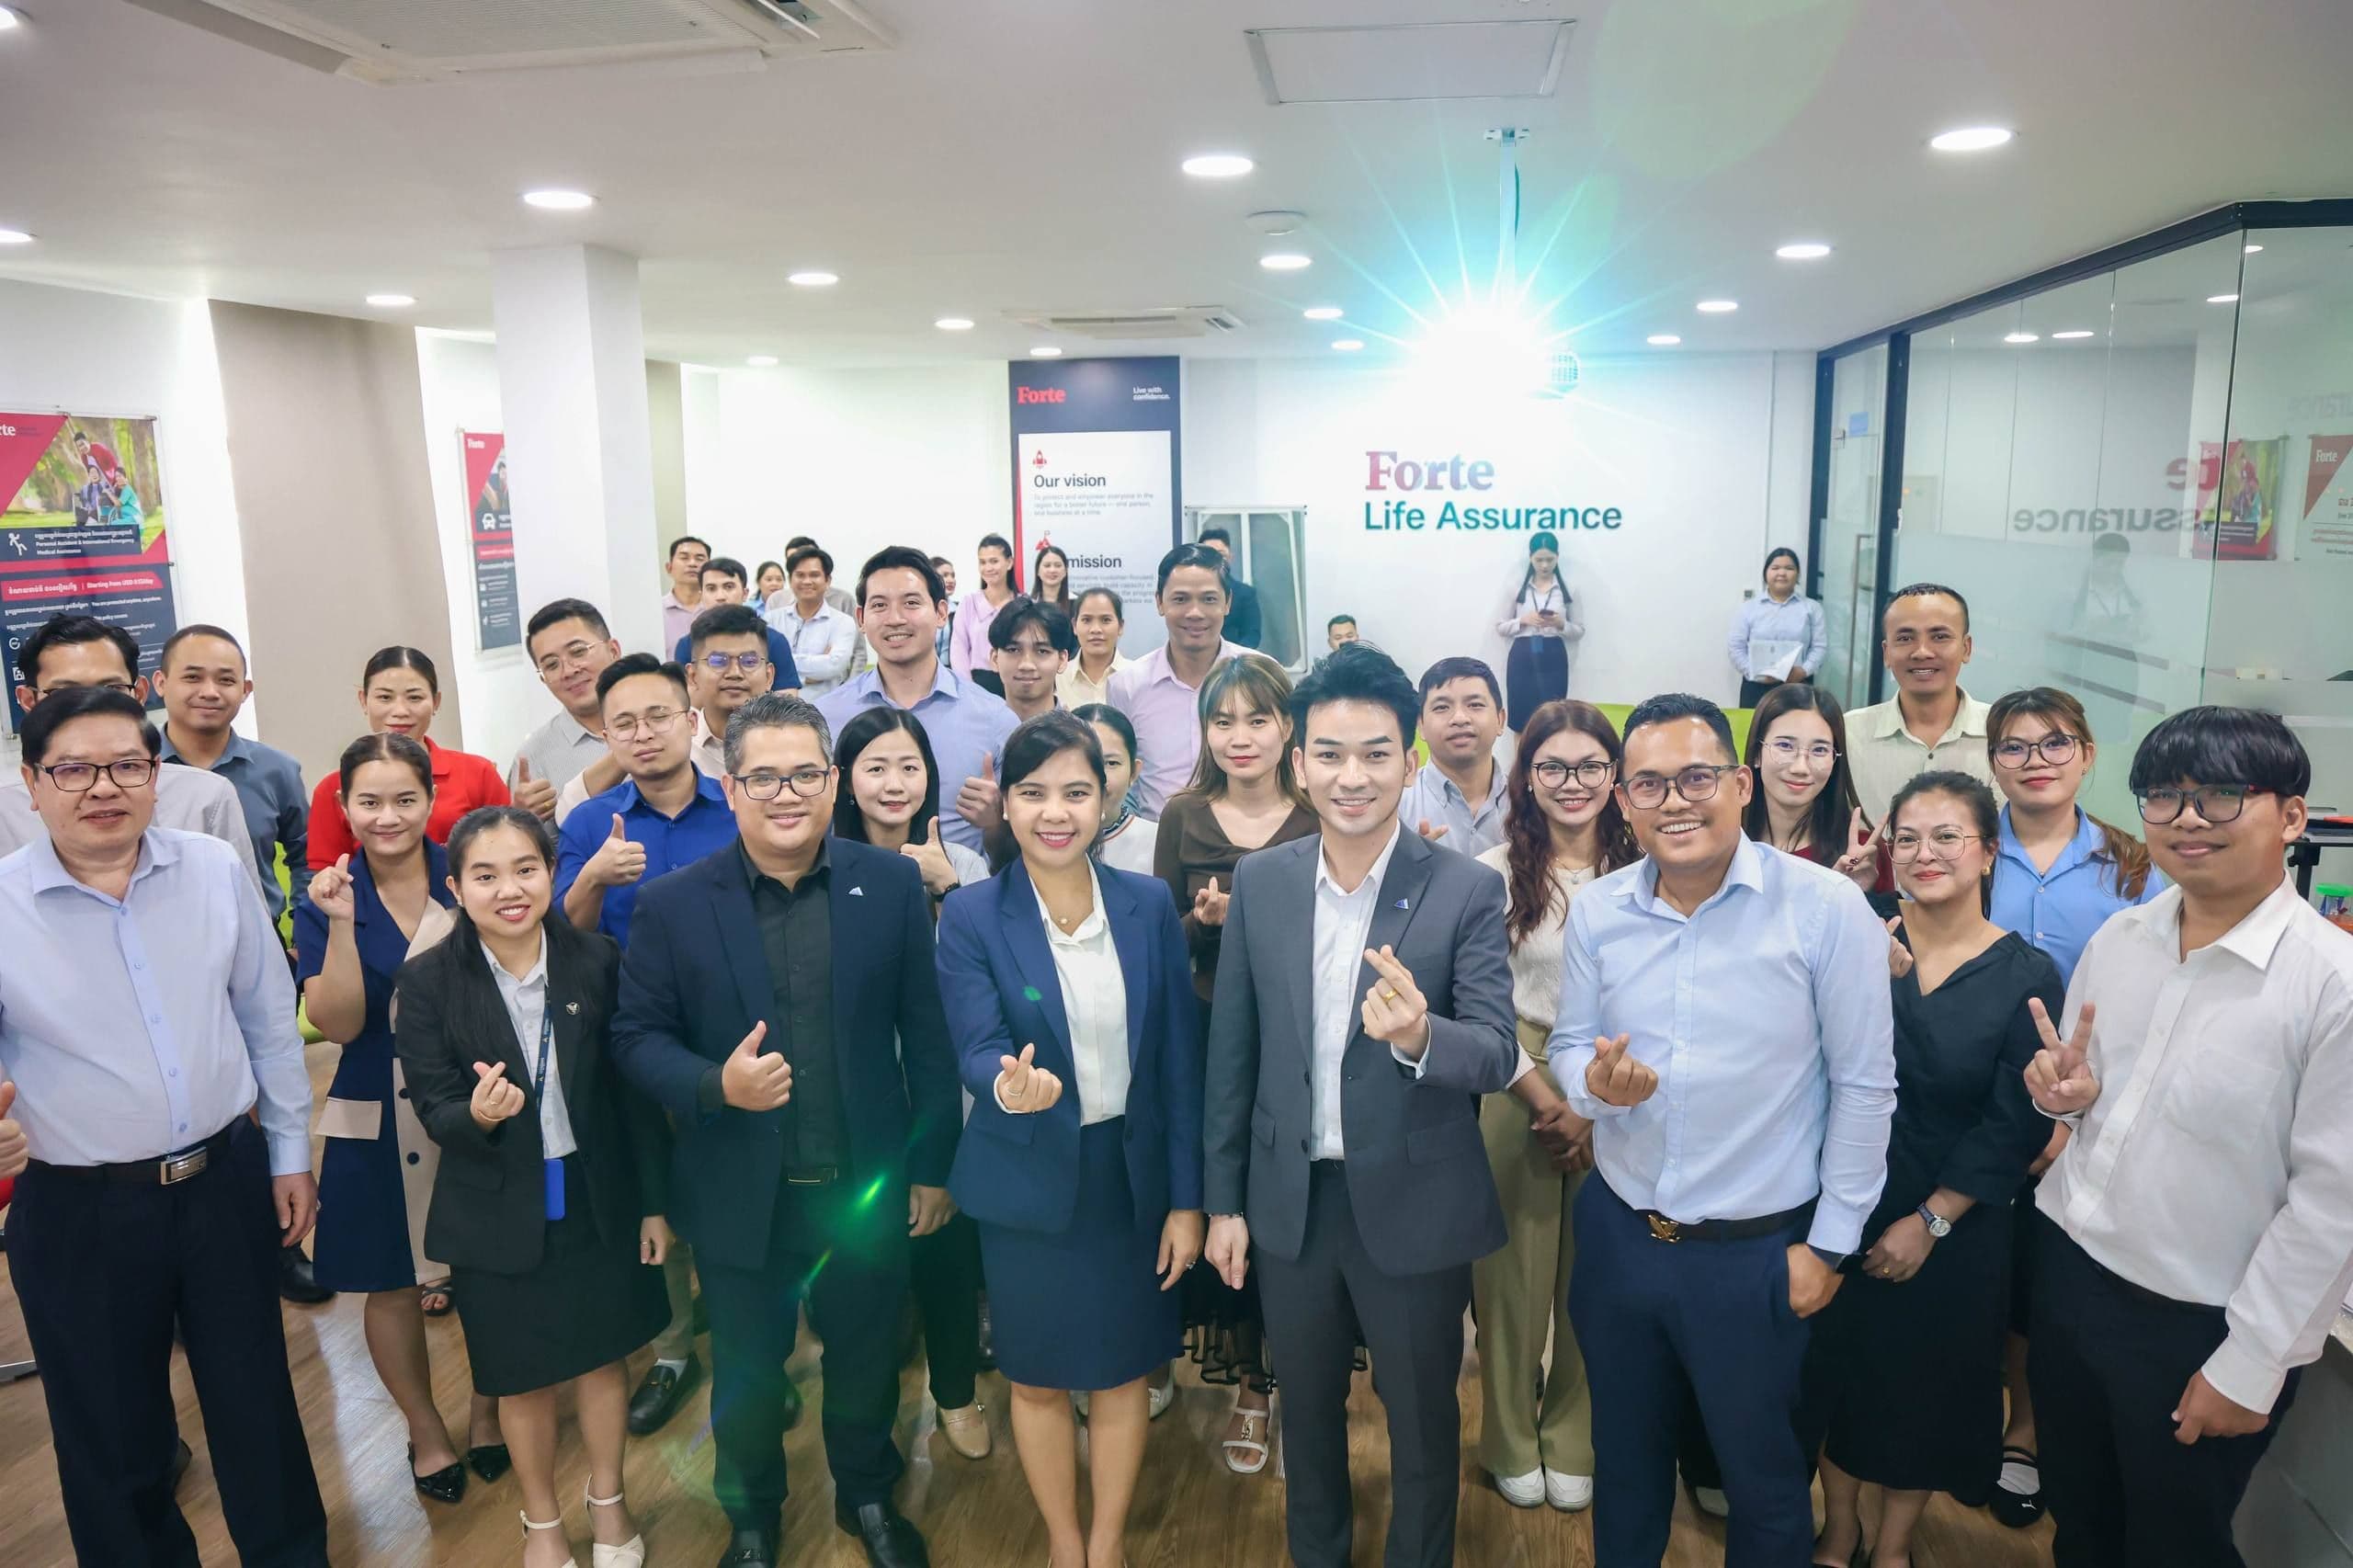
Banjaran AMC Promotes BAEF Investment Opportunities to Forte Group
Banjaran Asset Management (Cambodia) Plc., in collaboration with ACLEDA Securities Plc., successfully organized a workshop on “Golden Investment Opportunities in Securities Sector” for the Management team and staff of Forte General Insurance Plc., and Forte Life Assurance Plc., on 12 August 2026 at Forte Office, One Park Tower. The workshop provided participants with valuable insights into the BAMC Asia Equity Fund (BAEF), including its key features, investment strategy, and the opportunities available through investing in a professionally managed fund licensed by the Securities and Exchange Regulator of Cambodia (SERC). During the session, Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc., delivered a presentation on “Investment Value and Benefits of the BAMC Asia Equity Fund (BAEF)”, sharing knowledge on investment opportunities and the benefits of BAEF as part of Cambodia’s growing securities sector. This workshop marks another important milestone under the Strategic Partnership between Banjaran Asset Management (Cambodia) Plc., ACLEDA Securities Plc., Forte General Insurance Plc., and Forte Life Assurance Plc., with the aim of enhancing investment awareness, strengthening collaboration, and creating opportunities for future business growth. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial
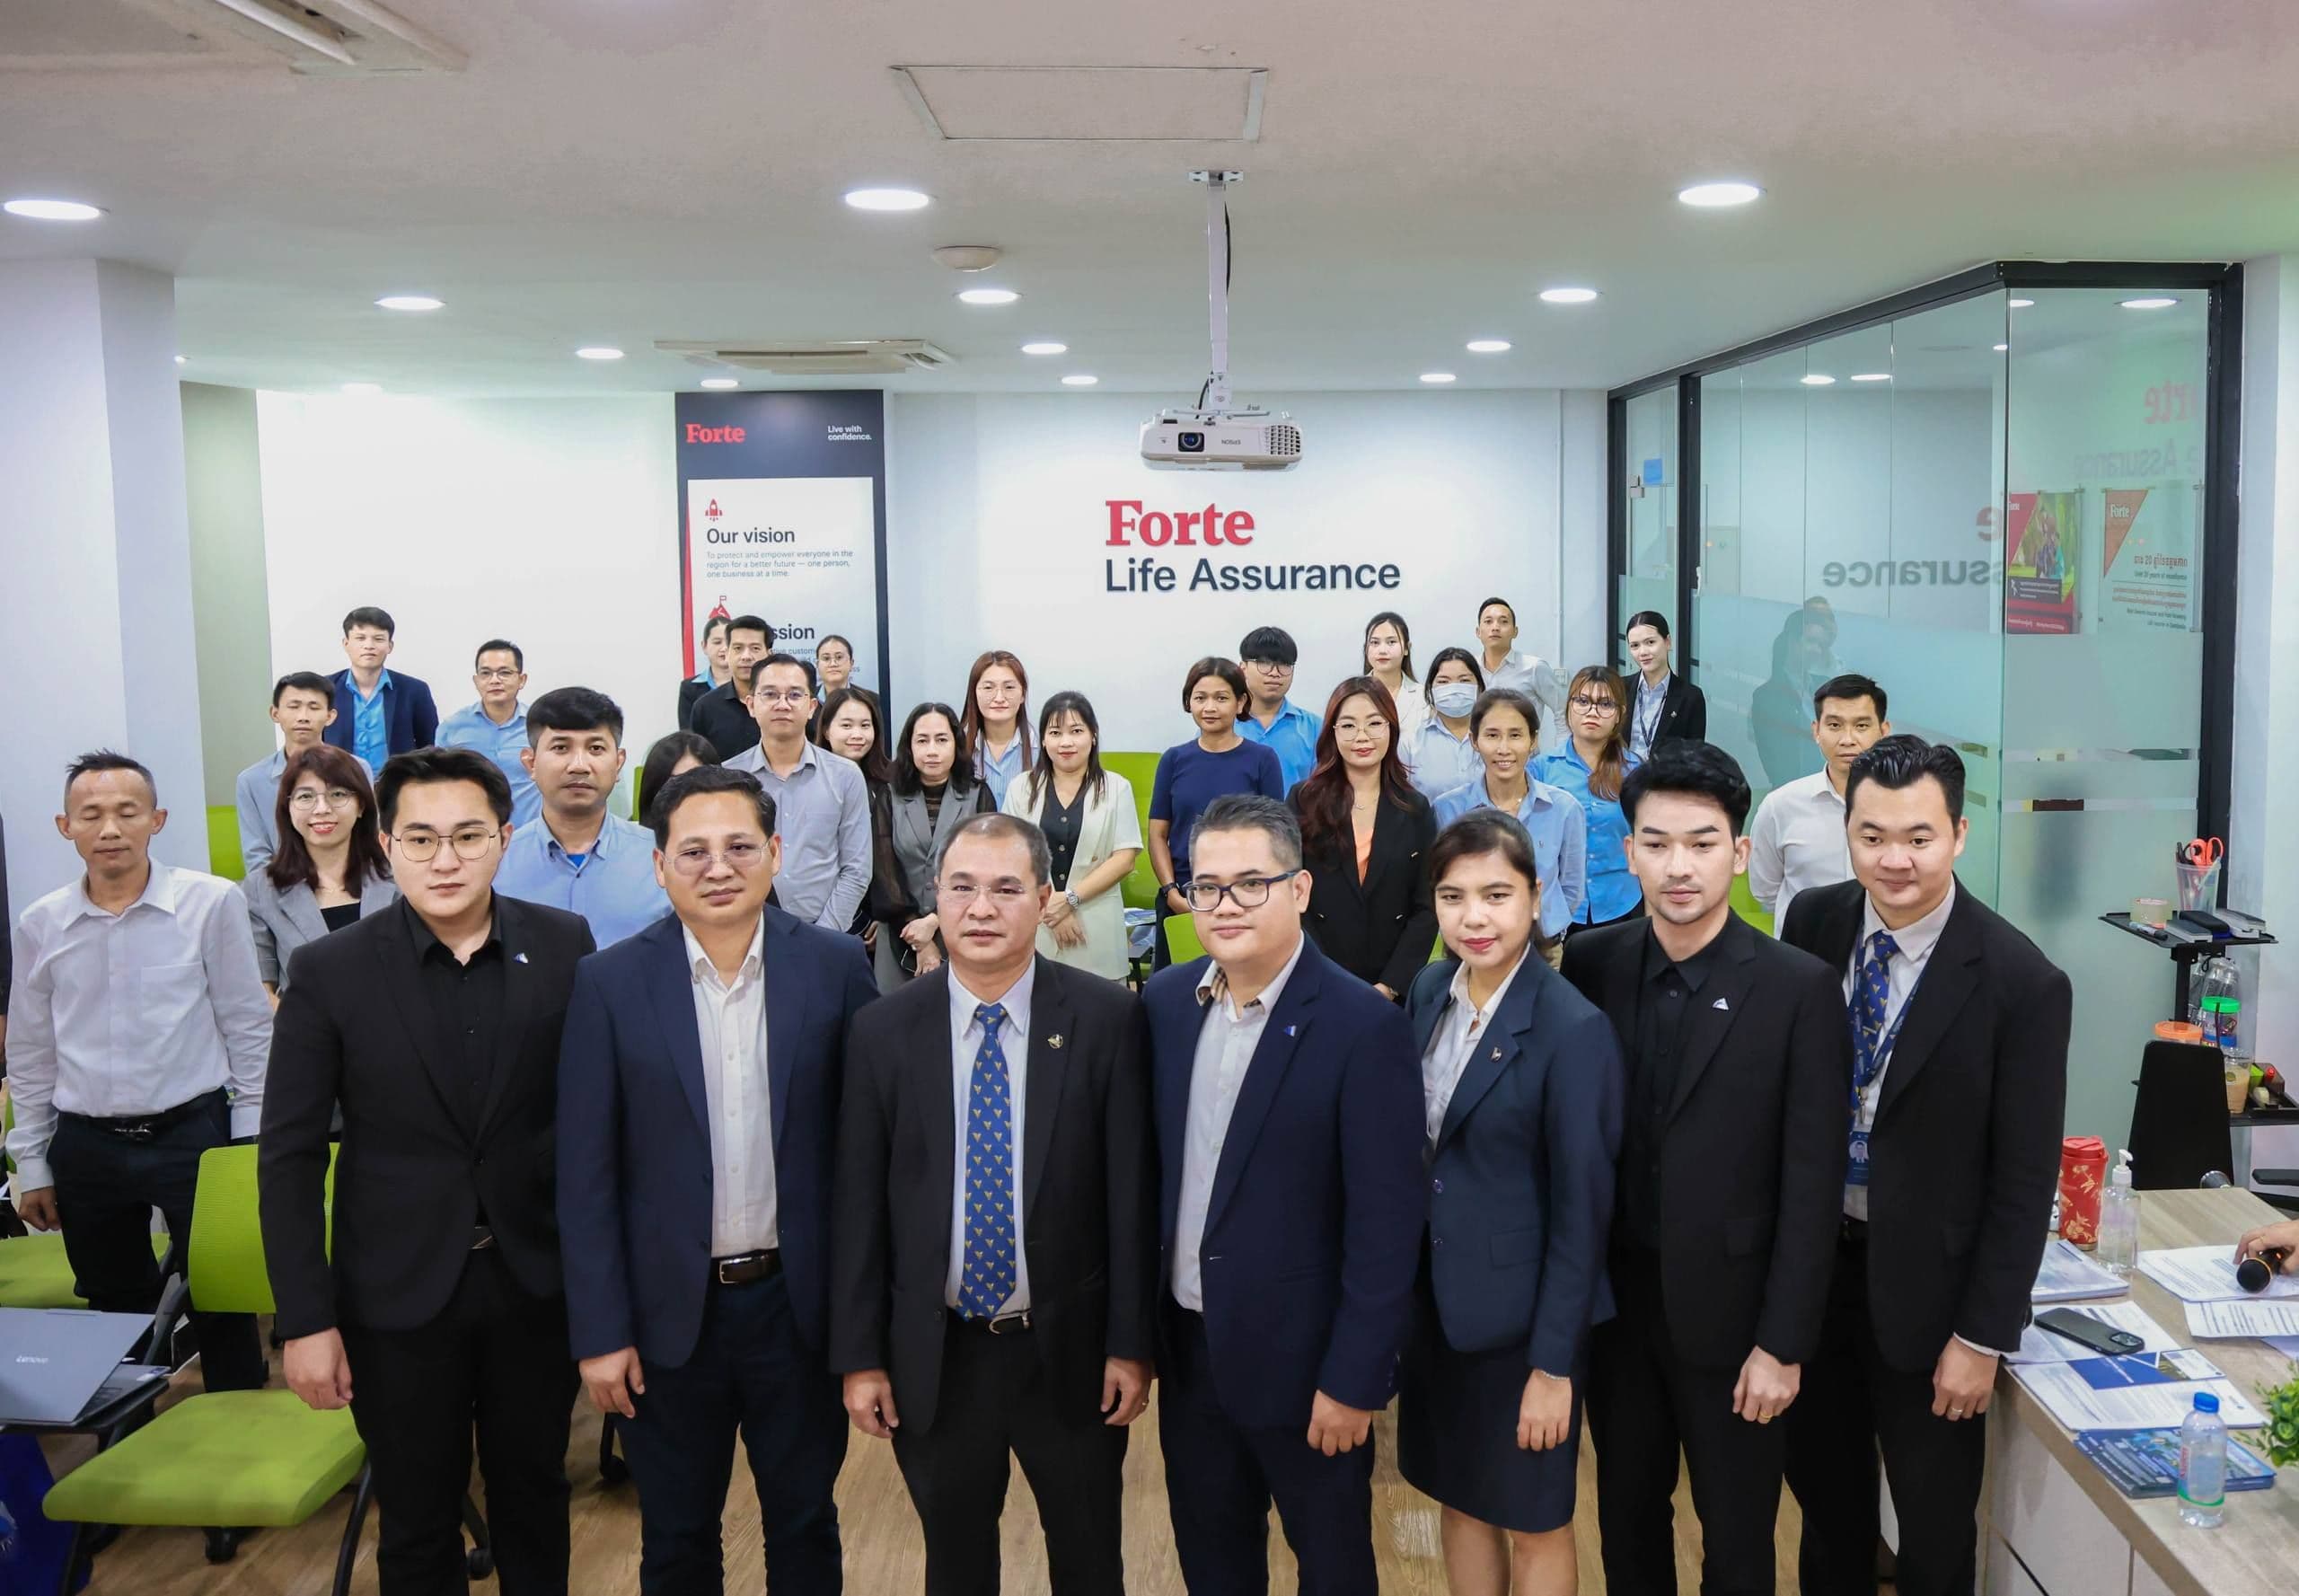
Banjaran AMC and ACLEDA Securities Host Investment Workshop for Forte
Banjaran Asset Management (Cambodia) Plc., in collaboration with ACLEDA Securities Plc., successfully organized a workshop on “Golden Investment Opportunities in Securities Sector” for the Management team and staff of Forte General Insurance Plc., and Forte Life Assurance Plc., on 06 August 2026 at Forte Office, One Park Tower. The workshop provided participants with valuable insights into the BAMC Asia Equity Fund (BAEF), including its key features, investment strategy, and the opportunities available through investing in a professionally managed fund licensed by the Securities and Exchange Regulator of Cambodia (SERC). During the session, Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc., delivered a presentation on “Investment Value and Benefits of the BAMC Asia Equity Fund (BAEF)”, sharing knowledge on investment opportunities and the benefits of BAEF as part of Cambodia’s growing securities sector. This workshop marks another important milestone under the Strategic Partnership between Banjaran Asset Management (Cambodia) Plc., ACLEDA Securities Plc., Forte General Insurance Plc., and Forte Life Assurance Plc., with the aim of enhancing investment awareness, strengthening collaboration, and creating opportunities for future business growth. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial
Market Outlook
2024 October Market Outlook: Hong Kong and China Stocks Await Policy Boost as AI Growth Persists in the US
Since the initial surge in the Hong Kong and Chinese stock market, significant profit taking has followed. Despite this, we maintain our view that company valuations in the region remains attractive. The main event that we are monitoring is towards the end of this month, where China holds their Politburo Standing Committee. We expect major stimulus measures to be announced given the state of their economy, and this should result in a positive impact to stock valuations. In the absence of strong stimulus measures, we will be reassessing our view on the region. We remain confident that investments in artificial intelligence (“AI”) applications will remain strong through 2025, driven by the industry's continued high-growth potential. While sales momentum has moderated, we believe this cycle has several more quarters of growth ahead. As a result, we believe that modest selloffs in the US technology sector are potentially attractive entry points.
2024 September Market Outlook: Tech Stocks Face Headwinds as AI Valuations Come Under Scrutiny
Since the last newsletter, technology stocks continued to underperform as investors began to question the premium valuations that these companies command since the start of the artificial intelligence (“AI”) narrative. There is no doubt that AI will result in long-term productivity gains as more companies begin to announce standalone AI products. Additionally, continued improvements in AI hardware will likely accelerate development going forward. As we assess the current investment landscape, we anticipate the road forward for AI-related opportunities to be less smooth than the past year as investors increasingly scrutinize the potential for these AI investments and applications to deliver solid returns. We believe that the first to see widespread AI adoption would be in areas that provide support in pattern recognition and personal assistance. These applications, while not entirely new, have progressed significantly over the past year. To illustrate, Salesforce has recently announced Agent Force, a client servicing bot that is easily customizable for different industry applications. Compared to older chatbots, early adopters of Agent Force have seen a 40% improvement in customer query resolution. In healthcare, doctors are also increasingly using AI to assist with effective diagnosis and drug development. We are well positioned to benefit from increasing AI adoption over the long-term on this front. Where we are looking to gain additional exposure is in AI-related hardware. We are tracking several data center equipment and power management companies. However, these sectors in general are trading at a high premium and are already well-invested. We believe we should take a more considered approach prior to initiating a significant position given the high valuations. The AI landscape is undoubtedly changing very quickly, and we will be flexible on our positions depending on the developments that unfold going forward.
2024 August Market Outlook: Yen Carry Trade Unwinds, Sparking Global Market Shifts
Early in August, equity markets experienced a sudden spike in volatility, where volatility reached levels unseen since the COVID-19 crash. This was caused by a significant unwinding of the Yen carry trade. The unwinding was triggered after the Bank of Japan (“BOJ”) unexpectedly raised interest rates, where a sharp appreciation in the Japanese Yen followed. Traders who borrowed Yen cheaply then had to sell off their investments to pay back their borrowings. The situation worsened when weaker-than-expected US employment data caused the greenback to depreciate further against the Yen. Shortly after the sharp market decline, the BOJ has given comfort to the public that they will not hike interest rates further while financial markets are unstable. Thus, we are of the opinion that as of now, the carry trade should not cause further volatility. We are cautiously optimistic about the market consolidation. The reason for the caution is due to the still high valuation of the broad US equity market despite increasingly slowing fundamentals and economic data. We will continue to watch near-term trends given that a broad recovery in equity markets normally results in bullish short-term sentiment.
2024 July, Market Outlook: Mixed Signals from China and Cautious Optimism in the US
China’s economic landscape continues to be buoyed by its manufacturing sector, while consumer spending remains notably sluggish. Recent data reveals that retail sales growth has fallen short of expectations, with the latest Q2 Gross Domestic Product (GDP) reading showing a deceleration to just 4.7% year-on-year. However, there are encouraging signs in the property market; easing measures on homebuying has resulted in a significant uptick in secondary property sales in tier-one cities, which jumped by double digits. While this early data is promising, we remain cautious. Our previous observations indicate that any increase in home sales following the significant relaxation of restrictions in 2023 was short-lived. Therefore, we will closely monitor the outcomes of the upcoming Third Plenary Session, which will shed light on the policies that will shape China’s economic future. In the United States, we maintain a cautious stance regarding the medium-term economic outlook. The deceleration in growth and rising unemployment trends have yet to raise alarms among investors, primarily due to the robust inflow of investments related to artificial intelligence. Over the long term, we believe that fiscal dominance will be a critical factor, as the Congressional Budget Office projects that debt-to-GDP ratios could soar from around 120% today to 200% within the next 30 years. This projection raises valid concerns about the sustainability of the US economy. However, we posit that the current status quo could persist longer than anticipated. History shows that attempts to time market peaks often lead to substantial opportunity costs. Thus, we will continue to invest in US firms while remaining vigilant about potential de-dollarization and long-term debt risks. Following recent testimonies from the Federal Reserve regarding their readiness to lower interest rates, combined with market expectations of a potential Donald Trump victory in the upcoming presidential election, we have witnessed a noticeable rotation into smaller-capitalization stocks. These stocks have underperformed the Standard & Poor’s 500 Index since the COVID-19 pandemic heavily impacted their operations. Market sentiment seems to be favoring a "no landing" scenario, where small businesses could benefit more from lower borrowing costs and increased fiscal spending compared to larger firms. However, we approach this sector with caution, particularly concerning smaller companies that have significant debt exposure, given our apprehensions about a global slowdown in demand. In conclusion, while China shows signs of resilience through its manufacturing sector and initial recoveries in property sales, the broader economic outlook remains mixed, requiring careful observation of forthcoming policy changes. Meanwhile, the US market, bolstered by AI investments and potential shifts in fiscal policy, is experiencing volatility as investors reassess their strategies in light of evolving economic indicators. As we navigate these complexities, our focus remains on identifying solid investment opportunities while balancing risks in an uncertain environment.
2024 June, Market Outlook: Semiconductor Surge, Fed Caution, and AI's Future Potential
The equity markets have continued to reach new highs, largely driven by the exceptional outperformance of semiconductor stocks. This concentrated movement suggests that investors are placing heavy bets on a few sectors, which may indicate underlying caution about the broader economy. While the semiconductor sector's growth has been impressive, this narrow market rally could be vulnerable to shifts in sentiment, making it essential for investors to stay vigilant. On the macroeconomic front, the US Federal Reserve has remained cautious, withholding any strong indication of interest rate cuts in the near term. Citing robust employment numbers and persistently high inflation, the Fed has expressed that it needs to see more data before making any moves. As businesses and consumers have so far shown resilience, many market analysts have pushed back their expectations of a potential recession. However, there are signs of softening in the labor market, with the US unemployment rate gradually climbing to 4%, up from a low of 3.4% in 2023. This could be a precursor to broader economic weakness, aligning with our view that the Fed may have room for at least one interest rate cut later this year. China’s market performance, by contrast, has started to lag after the initial wave of optimism following the government’s policy interventions aimed at stabilizing the property market. Profit-taking has emerged as a natural response to the sharp upward momentum in Chinese equities earlier in the year. While market participants are now in a holding pattern, awaiting further updates on the property industry, we maintain the view that China’s real estate challenges are unlikely to result in systemic risk. The Chinese government has shown a clear commitment to managing the situation and is expected to introduce further targeted measures as needed. In the technology sector, we are particularly optimistic about the long-term productivity gains that could arise from AI applications. For example, a recent study found that software developers using Microsoft's GitHub CoPilot—an AI-powered coding assistant—completed tasks up to 56% faster than those without the tool. This significant efficiency boost highlights the transformative potential of AI in the workplace. Expectations for AI are sky-high, with investment in hyperscalers projected to grow at an annual rate of at least 20% through 2030. While AI-driven automation in areas such as customer service, email summarization, and image generation is expected to yield cost savings, we believe the next major economic leap will come from advancements toward Artificial General Intelligence (AGI). Current generative AI models have made substantial progress in recent years but are still limited by their inability to adapt effectively when faced with queries outside their training data. The evolution toward AGI would address this limitation, enabling AI to perform a broader range of tasks with greater accuracy and versatility. Additionally, consumer applications of AI are somewhat constrained at present, as mobile hardware lacks the processing power needed to run AI-driven tasks efficiently. However, the sustained investment in AI technologies is already leading to rapid improvements, and we continue to monitor developments for potential investment opportunities as companies push the boundaries of innovation and find new ways to monetize AI advancements. In summary, while semiconductor stocks have driven much of the equity market gains in 2024, a cautious stance is warranted due to the concentration of market activity. The Fed's hesitance to cut rates amid a weakening labor market adds another layer of complexity. Meanwhile, China's property market stabilization efforts are ongoing, and AI’s long-term promise continues to excite, but its full potential may take years to materialize. As we navigate these shifting dynamics, we remain focused on identifying selective opportunities across sectors and regions.
2024 May, Market Outlook: Navigating Global Volatility and Strategic Opportunities
Global equity markets have staged a strong recovery from April's decline, buoyed by cooling US economic data and a wave of significant share buyback programs. We anticipate that this erratic market behavior will persist until there's more certainty regarding the timing of interest rate cuts, as investors eagerly respond to any hints of monetary easing. With the US elections approaching, we also expect heightened volatility as uncertainty around future government policies grows. In China, the government has taken direct action to restore confidence in the property sector. Restrictions on home-buying have been fully lifted in major cities like Xi’an, Hangzhou, and Chengdu, with further easing measures introduced elsewhere. More notably, the administration has launched a 300 billion RMB facility for local governments to acquire excess property inventory and convert it into affordable housing. This initiative has been well-received by market participants, leading to sharp price appreciation in China’s equity markets. However, we believe that for the facility to have a meaningful impact on the broader property sector, it will likely need to be expanded further. If these efforts are scaled up, property prices could stabilize, and consumer confidence may return. In addition, the Chinese government’s push for large-scale equipment renewals and trade-ins of durable consumer goods is aimed at boosting private consumption growth over the next few years. Other recent measures, such as removing mortgage rate floors and lowering downpayment rates, further signal China's commitment to supporting its economy. As Q1 earnings season concludes, we’ve observed mixed results from major US corporations. Consumer discretionary firms report slowing spending and a more selective consumer base, while companies with international exposure have commented on a slower-than-expected recovery from Chinese consumers. In contrast, US technology firms have maintained robust growth, particularly those benefiting from AI adoption. In China, a similar trend emerges: technology firms are expanding, while consumer spending remains tepid in most sectors. However, China's consumer base is on an upward trajectory, whereas the US is seeing a slowdown. Given the potential turning points in major global economies, we plan to be highly selective in both US and Chinese markets based on our current exposures. While economic data in Japan remains weak, we remain optimistic about the ongoing corporate governance reforms, which we believe will drive improved shareholder returns over the long term. Looking ahead, we remain focused on navigating these uncertainties and positioning ourselves to take advantage of selective opportunities in the evolving market landscape.