

Insights
Explore the latest news, expert articles, and market outlooks to stay ahead of industry trends.
Newsroom
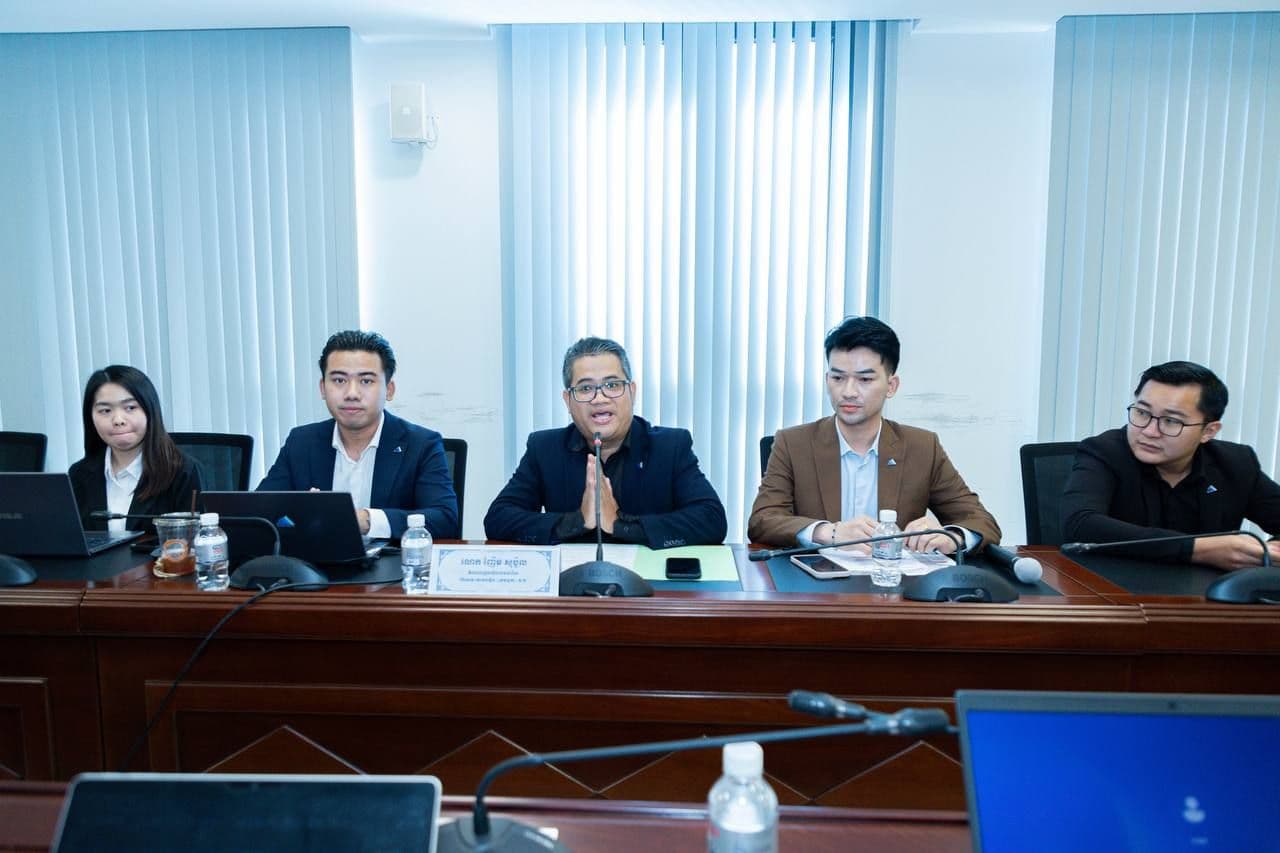
Banjaran AMC Conducts Second CIS Training Session for NSSF Officers and Staff
On the afternoon of 6 November 2026, under the direction of the management of Banjaran Asset Management (Cambodia) Plc., Mr. Nhem Sopaul, Head of Corporate Affairs, led a team from the Company in conducting the second training session on “Collective Investment Schemes (CIS)” for the officers and staff of the National Social Security Fund (NSSF) on 6 November 2026. During the training session, Mr. Sok Chantola, Sales & Marketing Deputy Manager; Mr. Taing Hoy, Internal Audit Senior Executive; and Mr. Veasna Monireach, Operation Senior Executive, delivered presentations on “Introduction to Banjaran AMC & CIS Landscape”, “BAMC Asia Equity Fund (BAEF)”, and “Investment Strategy & Key Value of Banjaran AMC”. The presentations provided participants with a better understanding of collective investment schemes, the Fund's investment approach, and the key values of Banjaran AMC. The training was organized to enhance participants' understanding of CIS, introduce the investment opportunities offered through BAEF, and raise awareness of investment funds and the development of Cambodia's capital market. Banjaran Asset Management (Cambodia) Plc. remains committed to promoting financial literacy, sharing investment knowledge, and contributing to the development of Cambodia's capital market through educational initiatives and knowledge-sharing activities.
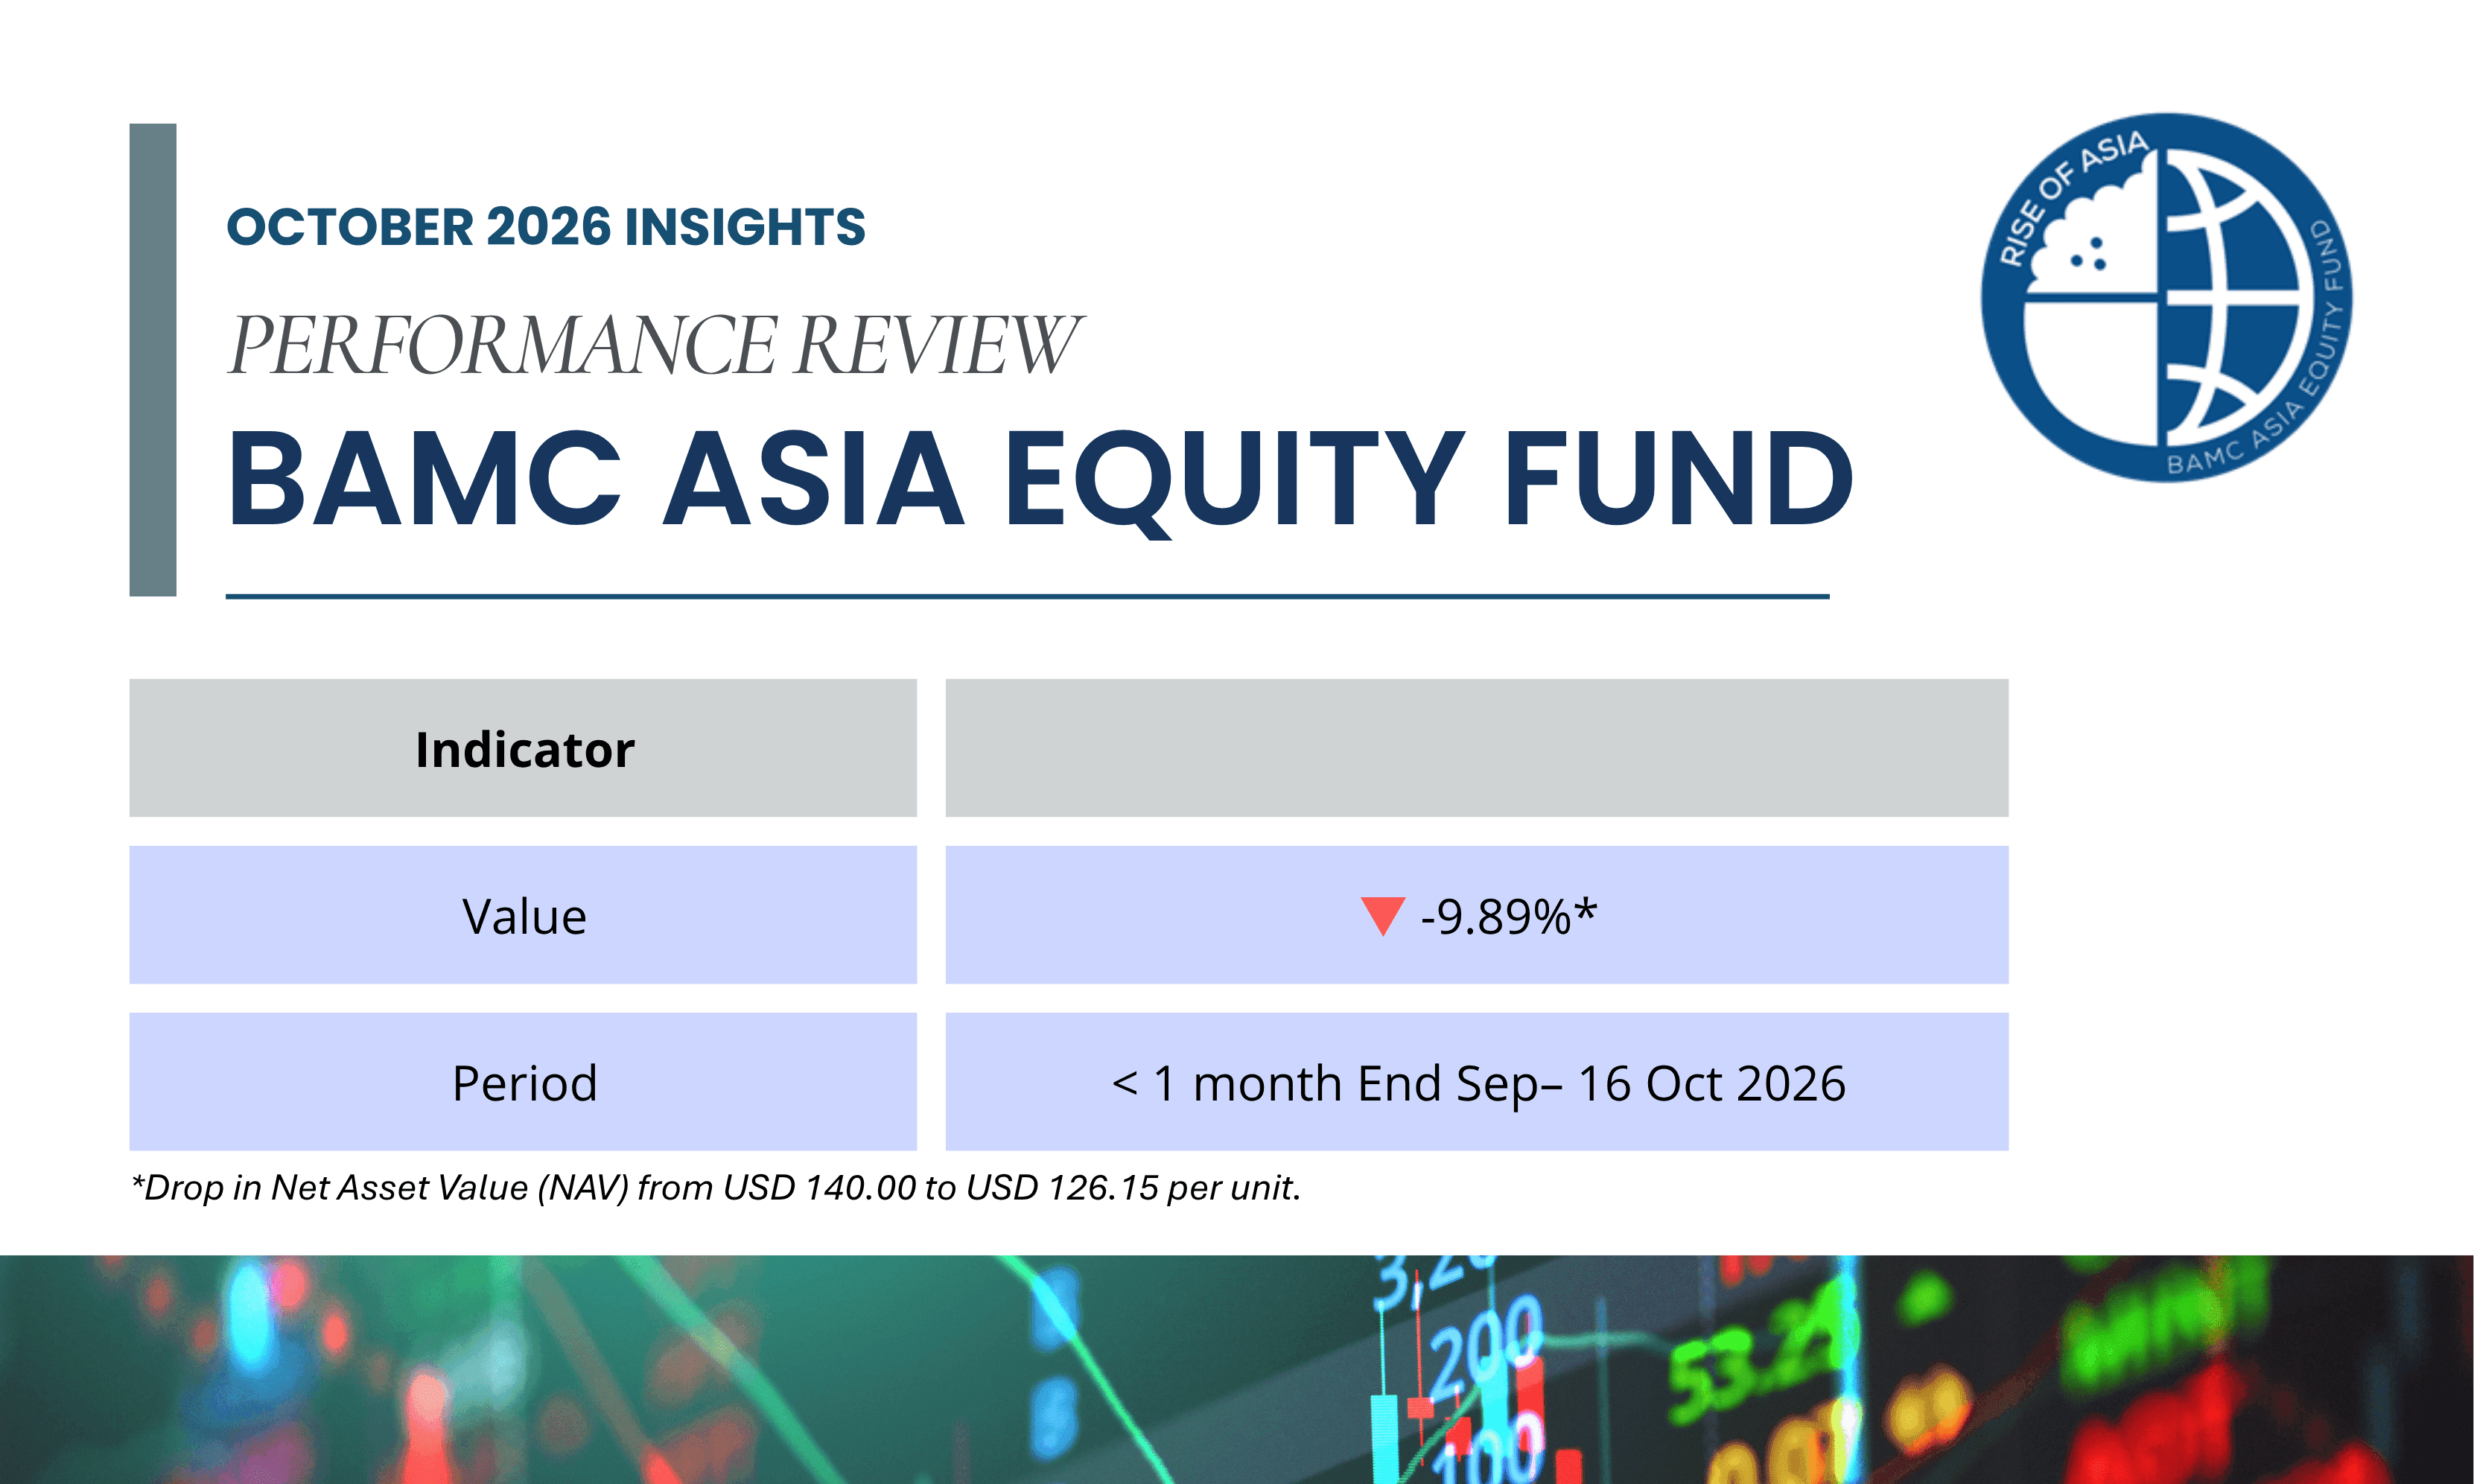
BAMC Asia Equity Fund (BAEF) Performance as of 16 October 2026
Markets in October Since end September, global equities have faced pressure from higher borrowing costs and growing scrutiny of the returns from AI related spending. Stronger than expected US inflation reinforced expectations of further Federal Reserve tightening, weighing particularly on technology and semiconductor valuations. Elevated oil prices added further pressure on inflation concerns. Overall, technology-heavy Asian markets bore a greater share of the selling in October’s global tech weakness. Our exposure to Asian equities reflects our focus on the region’s long-term growth opportunities. Short-term volatility is an inherent risk of this approach, but our investment decisions remain anchored in companies’ fundamentals and their potential to generate sustainable returns over time. Portfolio underperformance Against this backdrop, BAEF’s main drag was its concentration in Korean and Taiwanese equities and semiconductor related holdings, which together accounted for 32.3% of the portfolio and approximately 4% of the calculated drag. The Korea ETF and Samsung alone contributed roughly 2%. Korea was particularly affected by the unwinding of AI-related positions. On 15 October, its benchmark equity index fell approximately 8%. Samsung’s weakness came despite guidance for a substantial increase in third-quarter operating profit, suggesting that concerns over valuations, financing conditions and competition outweighed the near-term earnings improvement. The drop was compounded by sharp falls in several Singapore small caps and financials. Addvalue fell 22.9%, UOB Kay-Hian 25.2%, OCBC 10.3%. OCBC faced a specific catalyst when Citi downgraded the stock from “neutral” to “sell”, citing risks to third-quarter earnings, pressure on net interest margins from higher deposit costs, and the potential normalisation of exceptionally strong first-half wealth-related income. Addvalue’s share price weakness is due to profit-taking after a strong run. Singapore’s semiconductor-related suppliers to chipmakers fell harder than the larger chipmakers; Frencken fell 14.9%, UMS 14.8% and AEM 9.9%. Together, these holdings constituted approximately 14% of the portfolio and implied another 2.3% of drag. Like the global technology sell-off, broader concerns over the AI investment cycle were weighing on sentiment beyond individual companies’ reported performance. There were few meaningful offsets in the portfolio as gains elsewhere were insufficient to counter the losses. Why we still hold these stocks Despite the recent weakness, we retain these holdings because the underlying earnings drivers remain relevant to our investment horizon. The sell-off has weakened share prices more than the underlying medium- to long-term investment case. In semiconductors, the correction has coincided with continued growth in demand for AI compute. TSMC’s latest results and guidance pointed to sustained demand for advanced chips, while Samsung’s earnings guidance reflected stronger memory sales and pricing. These developments support maintaining exposure to the sector, although we recognise that strong operating performance does not eliminate valuation risk or the possibility of further share price volatility. Our Singapore semiconductor holdings provide exposure to different parts of this investment cycle. UMS benefits from equipment demand and increasing exposure to advanced packaging, AEM offers participation in increasingly complex semiconductor testing, and Frencken provides a more diversified manufacturing exposure. The rationale for retaining these positions rests on their prospective earnings as customers invest in additional capacity and advanced chip architectures, rather than an expectation that all semiconductor-related stocks will recover together. For the financial holdings, recent operating results provide a basis for distinguishing share price weakness from deterioration in the businesses. OCBC’s wealth-management and other non-interest income have helped offset pressure on lending margins, while its capital position continues to support business growth and distributions. UOB Kay Hian reported substantially higher first-half earnings, supported by stronger trading activity, commission income and interest income. We retain exposure to these earnings streams, while recognising that wealth related revenue and brokerage activity are market sensitive and that recent growth rates may not persist. We retain exposure to Addvalue to the long-term growth in satellite connectivity and space infrastructure. Recent share-price weakness appears to reflect, in part, profit-taking following a strong rally, while continued orders support the underlying growth outlook. In september, Addvalue announced US$15 million of new orders across its space connectivity and advanced digital radio business, bringing its order book to US$20.2 million. Converting these orders into earnings and cash flow remains central to our investment case. Overall, we remain selective and view the decline as a potential opportunity to top up positions rather as a reason to hold every position unchanged. Continued ownership must be supported by company fundamentals, an acceptable valuation, and grounded in earnings growth. Moving forward Looking ahead, we intend to increase exposure to quality large-cap and blue-chip companies to strengthen portfolio resilience amid continued volatility. We will prioritise businesses with sound balance sheets, sustainable earnings and cash flows, and durable competitive advantages. Further market weakness could provide opportunities to build positions at more attractive entry prices, while maintaining a disciplined approach to valuation. Disclaimer : This Document is issued for information and investor awareness purposes only to explain the factors contributing to the changes in BAEF’s NAV. It does not constitute investment advice, an investment recommendation, an offer, or a solicitation to buy, sell, or hold units of BAEF. The information provided herein should not be relied upon as the sole basis for any investment decision and does not guarantee future performance. Investors should refer to the Fund’s official offering documents and disclosures and carefully assess their own investment objectives and risk tolerance before making any investment decision.
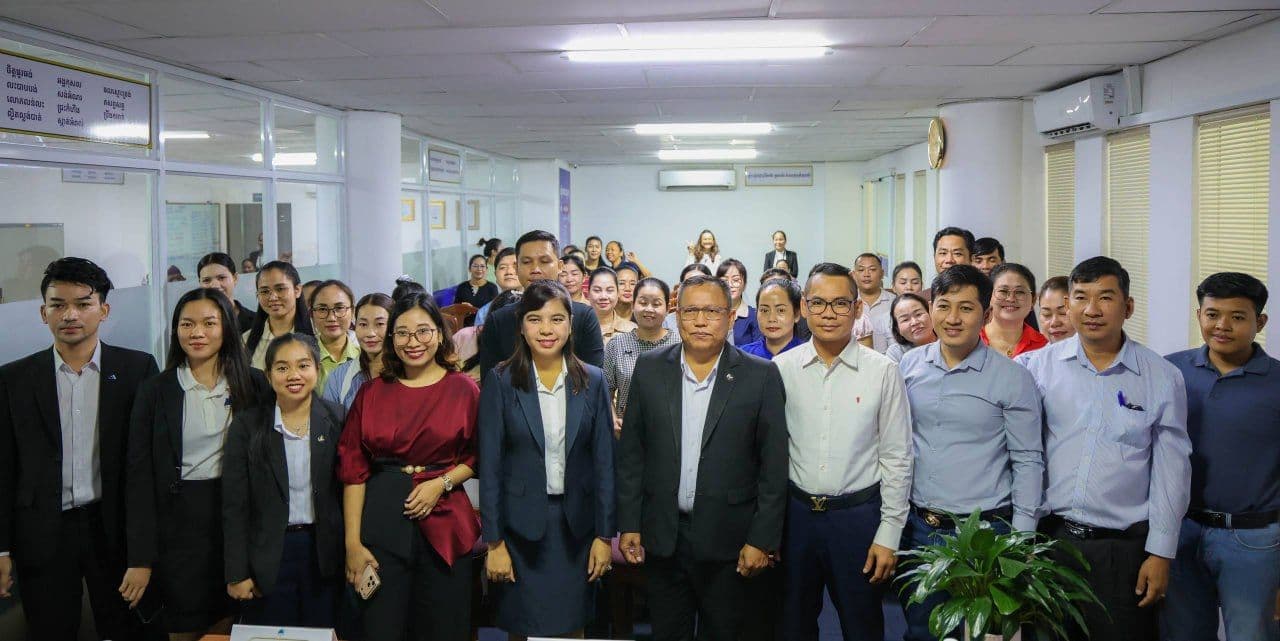
Banjaran AMC and ACLEDA Securities Host Golden Securities Investment Workshop in Chbar Ampov
Banjaran Asset Management (Cambodia) Plc. in collaboration with ACLEDA Securities Plc. and the ACLEDA Bank Plc. Local Branch (Khan Chbar Ampov – Sangkat Chbar Ampov Ti Muoy), successfully hosted the Workshop on “Golden Securities Investment Opportunities” as part of the 3rd Round Roadshow. The workshop was held at the meeting hall of ACLEDA Bank Plc. Local Branch (Khan Chbar Ampov – Sangkat Chbar Ampov Ti Muoy) on the morning of 12 September 2026. The workshop aimed to enhance public understanding of capital market investments and the BAMC Asia Equity Fund (BAEF), a Collective Investment Scheme (CIS). We sincerely appreciate the support of our partners and the active participation of all attendees. Special thanks to Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc. on the topic “BAMC Asia Equity Fund (BAEF)”. We look forward to welcoming you to our upcoming events. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial
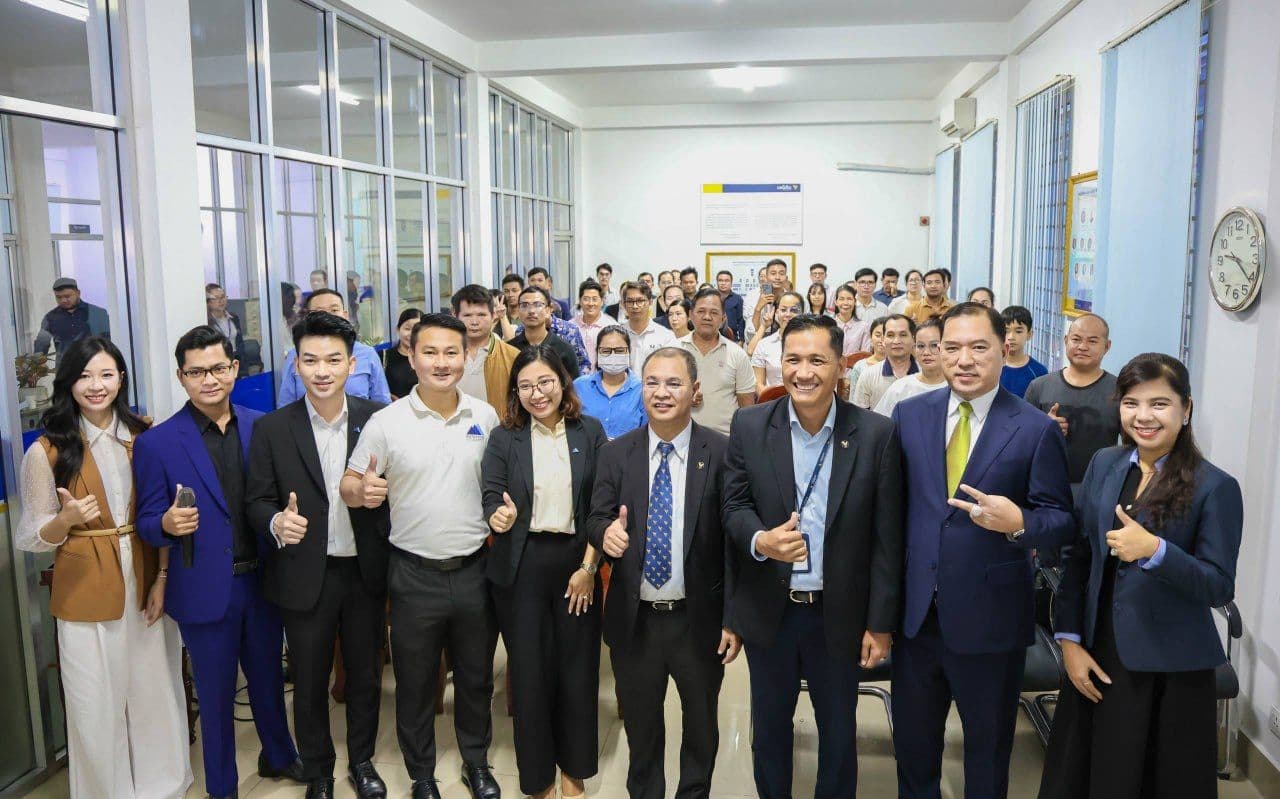
Banjaran AMC Brings BAEF Investment Opportunities to Investors in Phnom Penh Through 3rd Round Roadshow
Banjaran Asset Management (Cambodia) Plc. in collaboration with ACLEDA Securities Plc. and ACLEDA Bank Plc. Local Branch, (Khan Mean Chey, Sangkat Boeng Tumpun 01), successfully hosted the Workshop on “Golden Securities Investment by Opportunities” as part of the 3rd Round Roadshow. The workshop was held at the meeting hall of ACLEDA Bank Plc. Local Branch, (Khan Mean Chey, Sangkat Boeng Tumpun 01) on the morning of 05 September 2026. The workshop aimed to enhance public understanding of capital market investments and the BAMC Asia Equity Fund (BAEF), a Collective Investment Scheme (CIS). We sincerely appreciate the support of our partners and the active participation of all attendees. Special thanks to Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc. on the topic “BAMC Asia Equity Fund (BAEF)”. We look forward to welcoming you to our upcoming events. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial
Banjaran AMC Expands Securities Investment Awareness Through 3rd Round Roadshow in Svay Rieng
Banjaran Asset Management (Cambodia) Plc., in collaboration with ACLEDA Securities Plc., and ACLEDA Bank Plc. Local Branch (Svay Rieng Province), successfully hosted the Workshop on “Golden Securities Investment by Opportunities” as part of the 3rd Round Roadshow. The workshop was held at the meeting hall of ACLEDA Bank Plc. Local Branch (Svay Rieng Province) on the morning of 22 August 2026. The workshop aimed to enhance public understanding of capital market investments and the BAMC Asia Equity Fund (BAEF), a Collective Investment Scheme (CIS). We sincerely appreciate the support of our partners and the active participation of all attendees. Special thanks to Mr. Taing Hoy, Legal and Compliance Officer of Banjaran Asset Management (Cambodia) Plc., on the topic “Investment Value and Benefits of the BAMC Asia Equity Fund (BAEF)”. We look forward to welcoming you to our upcoming events. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial
Banjaran AMC Strengthens Strategic Partnership with Forte Through BAEF Investment Workshop
Banjaran Asset Management (Cambodia) Plc., in collaboration with ACLEDA Securities Plc., successfully organized a workshop on “Golden Investment Opportunities in Securities Sector” for the Management team and staff of Forte General Insurance Plc., and Forte Life Assurance Plc., on 19 August 2026 at Forte Office, One Park Tower. The workshop provided participants with valuable insights into the BAMC Asia Equity Fund (BAEF), including its key features, investment strategy, and the opportunities available through investing in a professionally managed fund licensed by the Securities and Exchange Regulator of Cambodia (SERC). During the session, Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc., delivered a presentation on “Investment Value and Benefits of the BAMC Asia Equity Fund (BAEF)”, sharing knowledge on investment opportunities and the benefits of BAEF as part of Cambodia’s growing securities sector. This workshop marks another important milestone under the Strategic Partnership between Banjaran Asset Management (Cambodia) Plc., ACLEDA Securities Plc., Forte General Insurance Plc., and Forte Life Assurance Plc., with the aim of enhancing investment awareness, strengthening collaboration, and creating opportunities for future business growth. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial
Banjaran AMC Advances BAEF Investment Awareness Through 3rd Round Roadshow in Siem Reap
Banjaran Asset Management (Cambodia) Plc., in collaboration with ACLEDA Securities Plc., ACLEDA Bank Plc. Local Branch (Krong Siem Reap, Sangkat Sla Kram), and ACLEDA Bank Plc. Local Branch (Krong Siem Reap, Sangkat Svay Dankum), successfully hosted the Workshop on “Golden Securities Investment by Opportunities” as part of the 3rd Round Roadshow. The workshop was held at the meeting hall of ACLEDA Bank Plc. Local Branch (Krong Siem Reap, Sangkat Sla Kram) on the morning of 15 August 2026. The workshop aimed to enhance public understanding of capital market investments and the BAMC Asia Equity Fund (BAEF), a Collective Investment Scheme (CIS). We sincerely appreciate the support of our partners and the active participation of all attendees. Special thanks to Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc., on the topic “Investment Value and Benefits of the BAMC Asia Equity Fund (BAEF)”. We look forward to welcoming you to our upcoming events. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial
Banjaran AMC Promotes BAEF Investment Opportunities to Forte Group
Banjaran Asset Management (Cambodia) Plc., in collaboration with ACLEDA Securities Plc., successfully organized a workshop on “Golden Investment Opportunities in Securities Sector” for the Management team and staff of Forte General Insurance Plc., and Forte Life Assurance Plc., on 12 August 2026 at Forte Office, One Park Tower. The workshop provided participants with valuable insights into the BAMC Asia Equity Fund (BAEF), including its key features, investment strategy, and the opportunities available through investing in a professionally managed fund licensed by the Securities and Exchange Regulator of Cambodia (SERC). During the session, Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc., delivered a presentation on “Investment Value and Benefits of the BAMC Asia Equity Fund (BAEF)”, sharing knowledge on investment opportunities and the benefits of BAEF as part of Cambodia’s growing securities sector. This workshop marks another important milestone under the Strategic Partnership between Banjaran Asset Management (Cambodia) Plc., ACLEDA Securities Plc., Forte General Insurance Plc., and Forte Life Assurance Plc., with the aim of enhancing investment awareness, strengthening collaboration, and creating opportunities for future business growth. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial
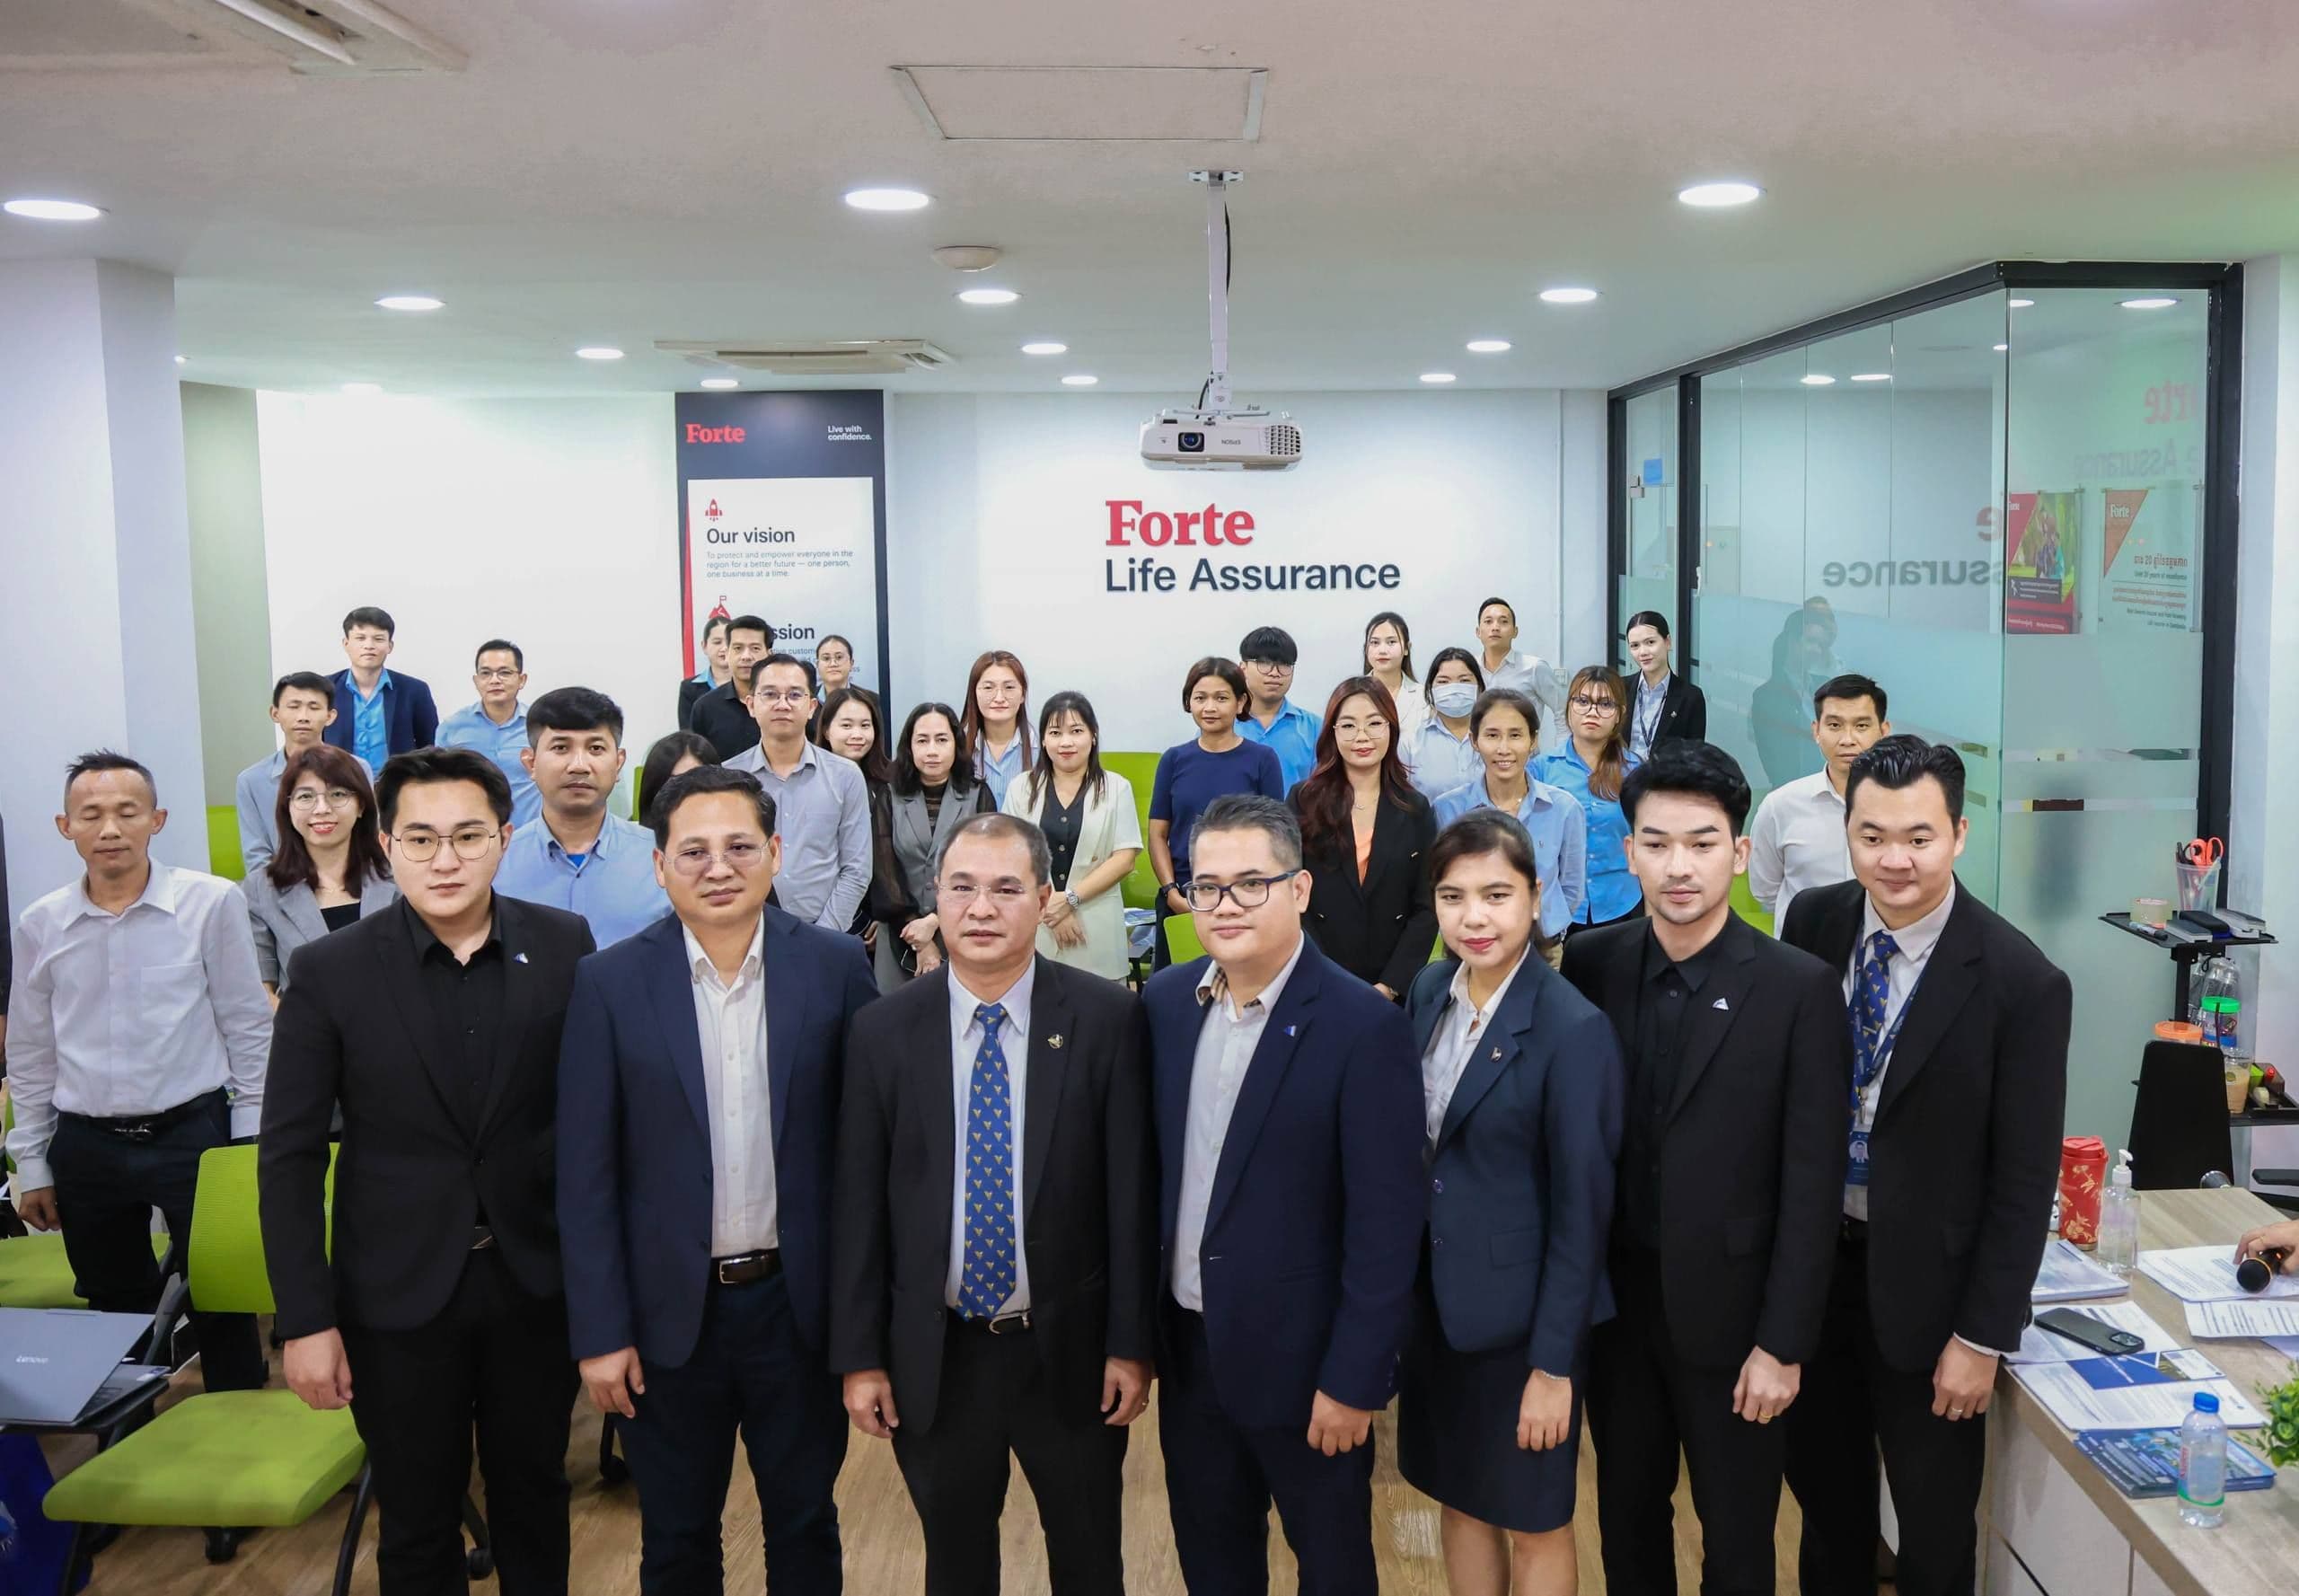
Banjaran AMC and ACLEDA Securities Host Investment Workshop for Forte
Banjaran Asset Management (Cambodia) Plc., in collaboration with ACLEDA Securities Plc., successfully organized a workshop on “Golden Investment Opportunities in Securities Sector” for the Management team and staff of Forte General Insurance Plc., and Forte Life Assurance Plc., on 06 August 2026 at Forte Office, One Park Tower. The workshop provided participants with valuable insights into the BAMC Asia Equity Fund (BAEF), including its key features, investment strategy, and the opportunities available through investing in a professionally managed fund licensed by the Securities and Exchange Regulator of Cambodia (SERC). During the session, Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc., delivered a presentation on “Investment Value and Benefits of the BAMC Asia Equity Fund (BAEF)”, sharing knowledge on investment opportunities and the benefits of BAEF as part of Cambodia’s growing securities sector. This workshop marks another important milestone under the Strategic Partnership between Banjaran Asset Management (Cambodia) Plc., ACLEDA Securities Plc., Forte General Insurance Plc., and Forte Life Assurance Plc., with the aim of enhancing investment awareness, strengthening collaboration, and creating opportunities for future business growth. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial
Market Outlook
2025 April Market Outlook: Tariff Shocks Rate Dilemmas and China’s Next Move
US tariff announcements have introduced a wave of uncertainty into global markets. While the initial shock caused equities to retreat sharply, sentiment steadied somewhat after the US paused broad-based tariffs for most countries, leaving China as the primary target for higher levies. This erratic policy approach has unsettled businesses and investors alike, with US Treasury yields responding with unusual speed. We are keeping a close eye on trade negotiations, particularly those involving China, as their outcomes could significantly influence market direction in the coming months. Meanwhile, the Federal Reserve’s decision to hold interest rates steady comes amid mixed signals from the economy. Strong consumer spending and a resilient labour market suggest underlying strength, but inflationary pressures remain a persistent concern. Political calls for rate cuts have added to the noise, yet the Fed’s next steps remain uncertain. For now, we are watching closely to see how these dynamics unfold, as the interplay between economic data and policy decisions will be critical in shaping the path ahead. In China, the investment climate remains somewhat cloudy amid ongoing tensions with the US. While fiscal stimulus measures announced during the Two Sessions meeting provide some support, including efforts to boost consumption and bolster key industries, we believe there is scope for further measures in the coming months.
2025 March Market Outlook: Cautious Optimism Amid Policy Shifts and Economic Uncertainty
The conclusion of China’s Two Sessions has injected optimism into the Chinese and Hong Kong markets. Key policy measures include maintaining a 5% growth target and increasing deficit spending to 4% of GDP. Beijing has also pledged greater support for the private sector and cutting-edge technologies. Investors’ reaction to these announcements have been positive so far as the government is shifting priority to restoring the private sector and help drive economic growth. In our view, this positive momentum is still in its early stages, given how negative global sentiment towards China has been over recent years. US-led trade tariff hikes have introduced significant political and economic uncertainty, primarily through passing higher costs for consumers and businesses, alongside the threat of retaliatory measures from trading partners. This has contributed to market instability and has dampened business optimism. We are cautious about trade-related developments due to their potential impact on global supply chains. However, we believe it is too early to make significant portfolio adjustments, as supply chains have historically demonstrated resilience to changing conditions. US consumer sentiment has dropped suddenly as rising inflation expectations weigh on confidence. Consumers are growing more cautious with spending, fearing a decline in purchasing power. This hesitation is reinforced by slowing economic indicators such as retail sales. A closer look at the data reveals a significant decline in sales at food service establishments, which could signal weakening consumer demand. We will closely monitor whether this is a temporary fluctuation or the beginning of a broader negative trend. At this time, we are still comfortable with our risk positioning, which remains well-diversified across various sectors and regions.
2025 February Market Outlook: Deepseek Shakes Up AI—Is China’s Tech Rebound Just Beginning?
The launch of Deepseek marks a notable development for China as the startup claims it is significantly more efficient than widespread models developed by US companies. The startup also claims to have developed the model with only US$ 6 million and has made their model publicly available for use globally. This stands in contrast to US technology firms, which have been spending billions of dollars. Additionally, the availability of Deepseek’s model has raised concerns about potential reductions in AI infrastructure investment. Our view is that these investments will continue since the US sees AI as a national security issue and will continue to advance their own AI models. The rise of Deepseek has also brought investor attention back to Chinese technology firms with their share prices rebounding strongly. Despite the meteoric rise, valuations are still at reasonable levels though we do expect profit-taking along the way given the recent sharp rise. We believe the positive shift in China’s stock market is at its early innings given how negative global investors have been on China over the past few years. We will be closely monitoring the outlook from major Chinese technology companies in their coming earnings results, along with key political events such as the upcoming Chinese government’s Two Sessions. These developments could further bolster investors interest in China. So far, earnings results from most US technology firms that we monitor were only marginally disappointing, yet significant price corrections have followed. We see this as a result of high analyst expectations and stretched valuations, which have amplified volatility even on minor earnings misses. That said, market sentiment remains positive, and with no signs of a recession, we will continue to maintain our positions.
2025 January Market Outlook: Strategies for Navigating a Shifting Global Landscape
In our previous update, we briefly shared our outlook for 2025, and we maintain our view that market risks will be driven by three key factors: the uncertain interest rate trajectory in the US, elevated US equity valuations in the sectors that we monitor and heightened geopolitical risks globally. These factors are likely to result in higher volatility in equity markets compared to recent years. However, this does not mean that equity prices will drop precipitously. Instead, we simply believe a more cautious approach to positioning and stock picking is warranted. The US equity market has benefited from the strength in its economy and leading position in artificial intelligence (“AI”) technologies. This has led to high earnings expectations being baked into stock valuations, which we find to be optimistic given the looming risk of tariffs and the ongoing cooling of the general economy. Some argue that the Trump administration will reduce corporate taxes to boost earnings and control interest rates despite inflation risks. Our view is that timing all these initiatives to benefit the US economy will be challenging and there will likely be knee-jerk reactions to any significant policy announcements, earnings misses and economic data surprises. For ASEAN countries, while the “China + 1” narrative is beneficial, they may not be spared from US tariffs as Trump announced his attention to impose tariffs on close allies such as the EU and Canada. Additionally, recent US technology export regulations were tightened, and none of the ASEAN countries were included in the list of “US allies” who were granted unrestricted access to advanced semiconductors. In other developed markets such as major EU countries and Japan, we believe that their economies are still struggling to pick-up meaningfully. Coupled with the ongoing geopolitical environment, we will continue to be selective in increasing exposure to these regions. Among the countries we monitor, we believe that China could be a bright spot in 2025, provided the administration acts strongly and decisively. They have announced ambitious goals to stimulate the economy with no concrete actions yet, in our view. We will be monitoring their key policy meetings for actionable plans before significantly increasing our weighting in the region.
2024 December Market Outlook: Balancing Caution and Opportunity Amid Global Economic Shifts
Recently, China has expressed increasing urgency to stabilize its property market and domestic consumption, through stronger-than-usual language from the administration. Given that these were mostly high-level statements, we remain skeptical on the announcement given the Chinese government’s hesitance to implement substantial economic stimulus in recent years. In the US, we also see that there has been growing interest in value stocks, as investors seek opportunities in undervalued companies amid concentrated gains in companies like the Magnificent Seven. At current valuations, Goldman Sachs has forecasted that the broader S&P500 index will return a mere 3% annually over the next 10 years. We will however remain focused and selective on US opportunities - buying on dips, looking at undervalued stocks or even going into smaller capitalization companies if they have differentiated business models or products. We believe this approach is more sensible under the current conditions of uncertainty in both the global economy and geopolitics heading into 2025.
2024 November Market Outlook: Balancing Chinese Stimulus and U.S. Political Shifts
The Chinese administration have announced their intention to rollout an additional RMB 6 trillion package to support the debt burden of local governments and China’s finance minister also gave forward guidance that they would be introducing new measures to further stabilize the property market. While the headline number of RMB 6 trillion seems substantial, ultimately it was not impressive as the debt swap is intended to occur gradually over the next 3 years. Furthermore, there is uncertainty over how the local governments will spur their respective economies once their debt position improves. A positive note is that there has been some initial rebound in property sales. However, we believe near-term equity valuations in China are likely to remain rangebound until further stimulus measures are announced given the modest earnings results so far. In the US, the presidential election results were a red sweep, where the Republican party took control of the House and Senate. This shift is expected to lead to more decisive policy action going forward which would be beneficial for domestic US companies. Nevertheless, President Donald Trump’s erratic nature may cause bouts of market volatility despite the anticipated policy clarity. Going forward into 2025, we remain constructive on technology companies. With overall valuation levels in this space remaining high and economic growth still normalizing, we shall selectively initiate new positions. We note that equity markets have been exhibiting high amounts of volatility on surprising economic data or slight earnings misses. We believe this is due to the high valuations observed in the broad equity market. Though disappointing earnings results may signal the start of a deterioration in business performance, we tend to see that most of these reactions are overblown over a long-term horizon. This presenting attractive buying opportunities.