

Insights
Explore the latest news, expert articles, and market outlooks to stay ahead of industry trends.
Newsroom
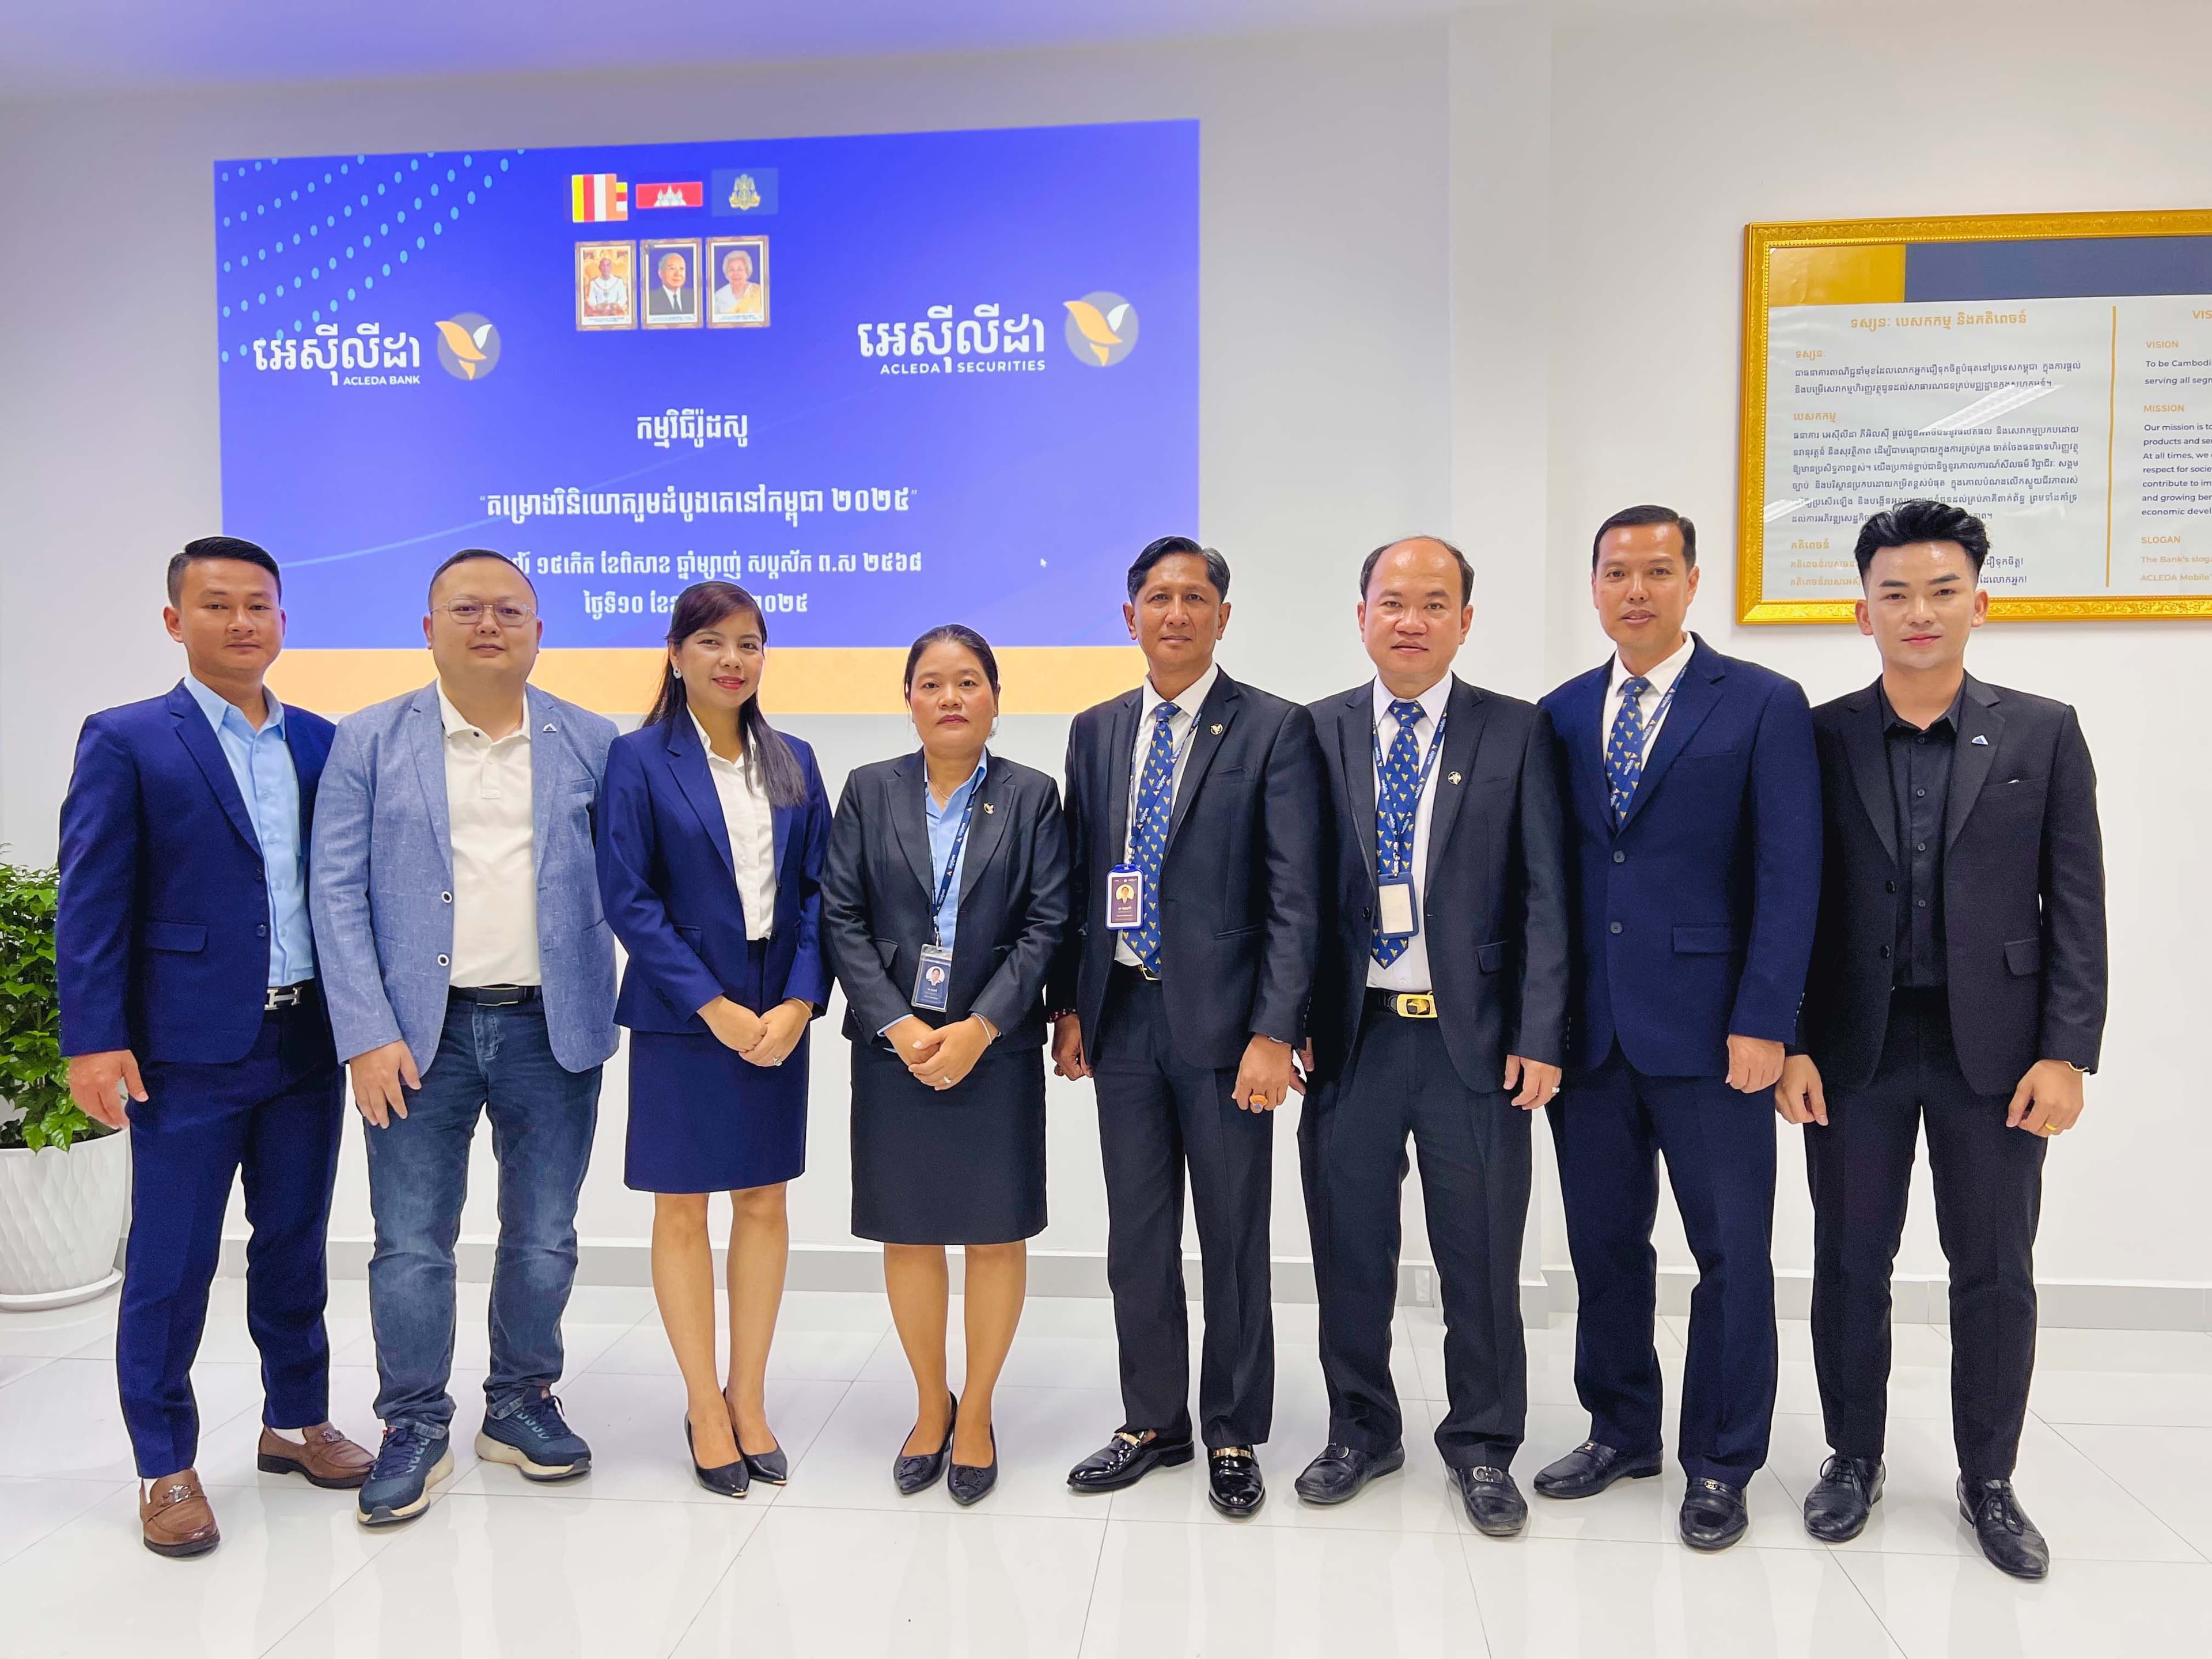
Cambodia's First Fund Roadshow 2.0, a Success in Prey Veng
Phnom Penh, Cambodia – May 10, 2025 – The second leg of Cambodia’s First Fund Subscription Roadshow 2.0 concluded successfully on 10 May 2025, at ACLEDA Bank Plc. in Prey Veng province. The initiative, a collaborative effort between Banjaran Asset Management (Cambodia) Plc. and ACLEDA Securities Plc, also included participation from several local ACLEDA Bank branches, including Pea Reang, Svay Antor, and Peam Ro. Banjaran AMC expressed their gratitude to all attendees for their support in making the event a success. The roadshow aims to introduce the BAMC Asia Equity Fund (BAEF) to a wider audience across Cambodia. Following the successful event in Prey Veng, the roadshow is set to continue its journey, bringing investment opportunities to more provinces throughout May and June 2025.
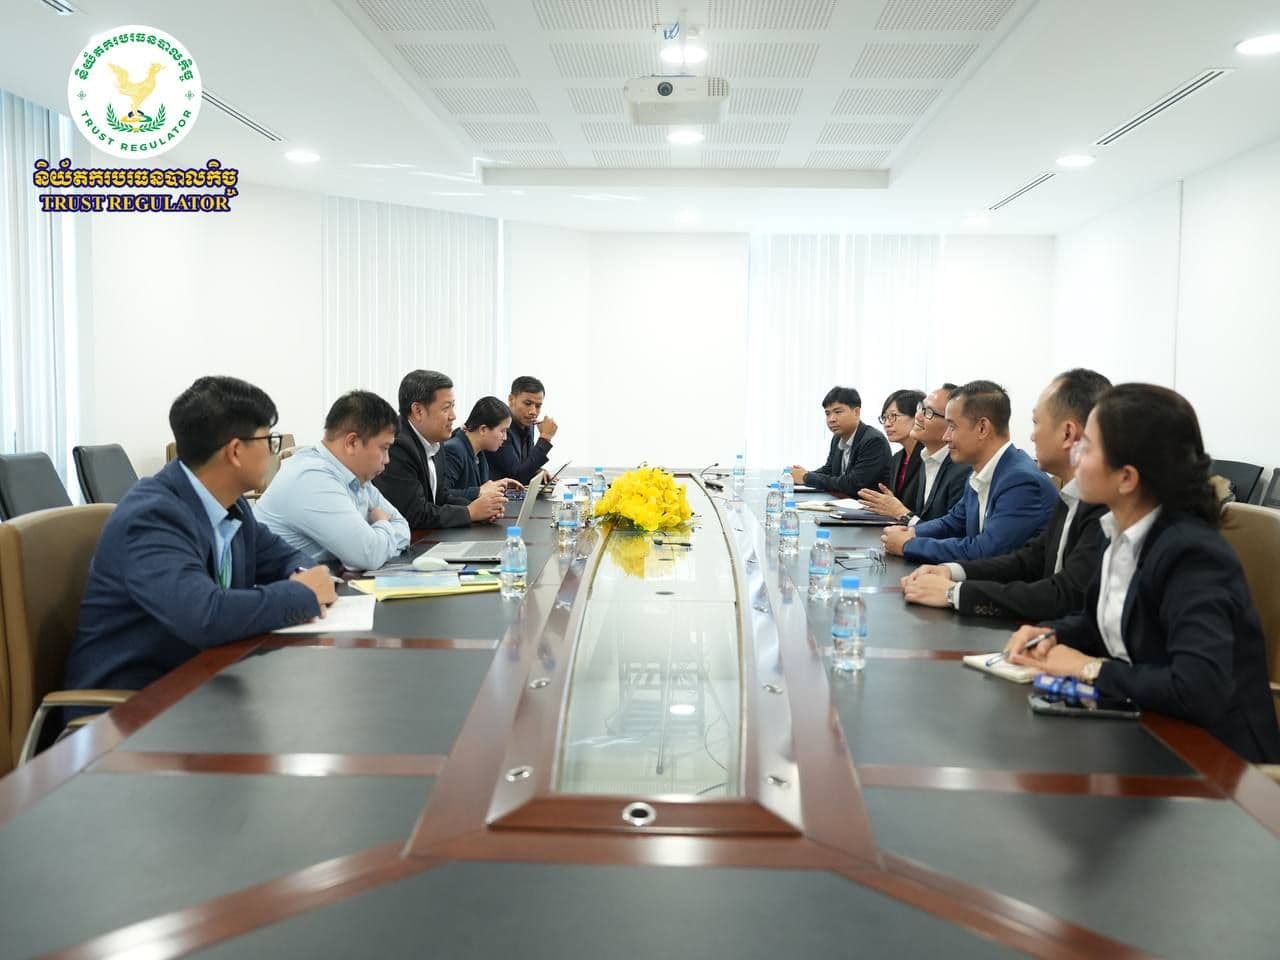
Mr. Eric Loo, CEO of Banjaran Asset Management (Cambodia) Plc., Participates in High-Level Meeting with Trust Regulator on Non-Bank Financial Sector Development
Phnom Penh, Cambodia – May 7, 2025 – Banjaran Asset Management (Cambodia) Plc., represented by its CEO, Mr. Eric Loo , alongside Lion Trust Group, held a pivotal high-level meeting with the Cambodia Trust Regulator (TR). Chaired by His Excellency Sok Dara, Director General of the TR , the session focused on advancing the non-bank financial sector and strengthening Cambodia’s regulatory framework. The strategic discussion highlighted a shared commitment between regulators and industry leaders to foster growth, innovation, and long-term trust in the Kingdom's financial ecosystem. A central focus of the meeting was the Trust Regulator's (TR) strategic emphasis on expanding trust structures, particularly family trusts, as a cornerstone of asset protection and intergenerational wealth transfer. For asset managers like Banjaran AMC, these frameworks serve as vital mechanisms to help high-net-worth individuals and businesses secure long-term financial stability while ensuring smooth succession planning—a growing priority in Cambodia’s evolving economic landscape. This dialogue aligns closely with the Trust Regulator's (TR) ongoing market development efforts, such as their recent “Family Trust for Succession Planning” seminar held on April 29, 2025, at Sokha Hotel, Phnom Penh. Organized in partnership with Phillip Trustee (Cambodia) and Phillip Capital (Singapore), that session provided deep insights into regional best practices, offering tailored strategies that firms can leverage within the local market. Reflecting this proactive environment, Banjaran AMC’s active engagement with the TR underscores its commitment to shaping a dynamic, sophisticated, and inclusive trust sector in Cambodia. By maintaining a close collaborative relationship with regulators, the firm aims to develop innovative financial solutions that directly address the wealth preservation needs of local families and institutional investors. This momentum builds upon continuous regulatory engagement, including a previous baseline dialogue between His Excellency Ney Sakal, Deputy Director General of the TR (representing Director General Sok Dara) , and the leadership of Lion Trust (Singapore) Limited. Given the Trust Regulator's (TR) active promotion of these services, the ongoing collaboration with specialized institutions like Banjaran AMC holds substantial promise for elevating the sophistication of Cambodia's broader financial sector.
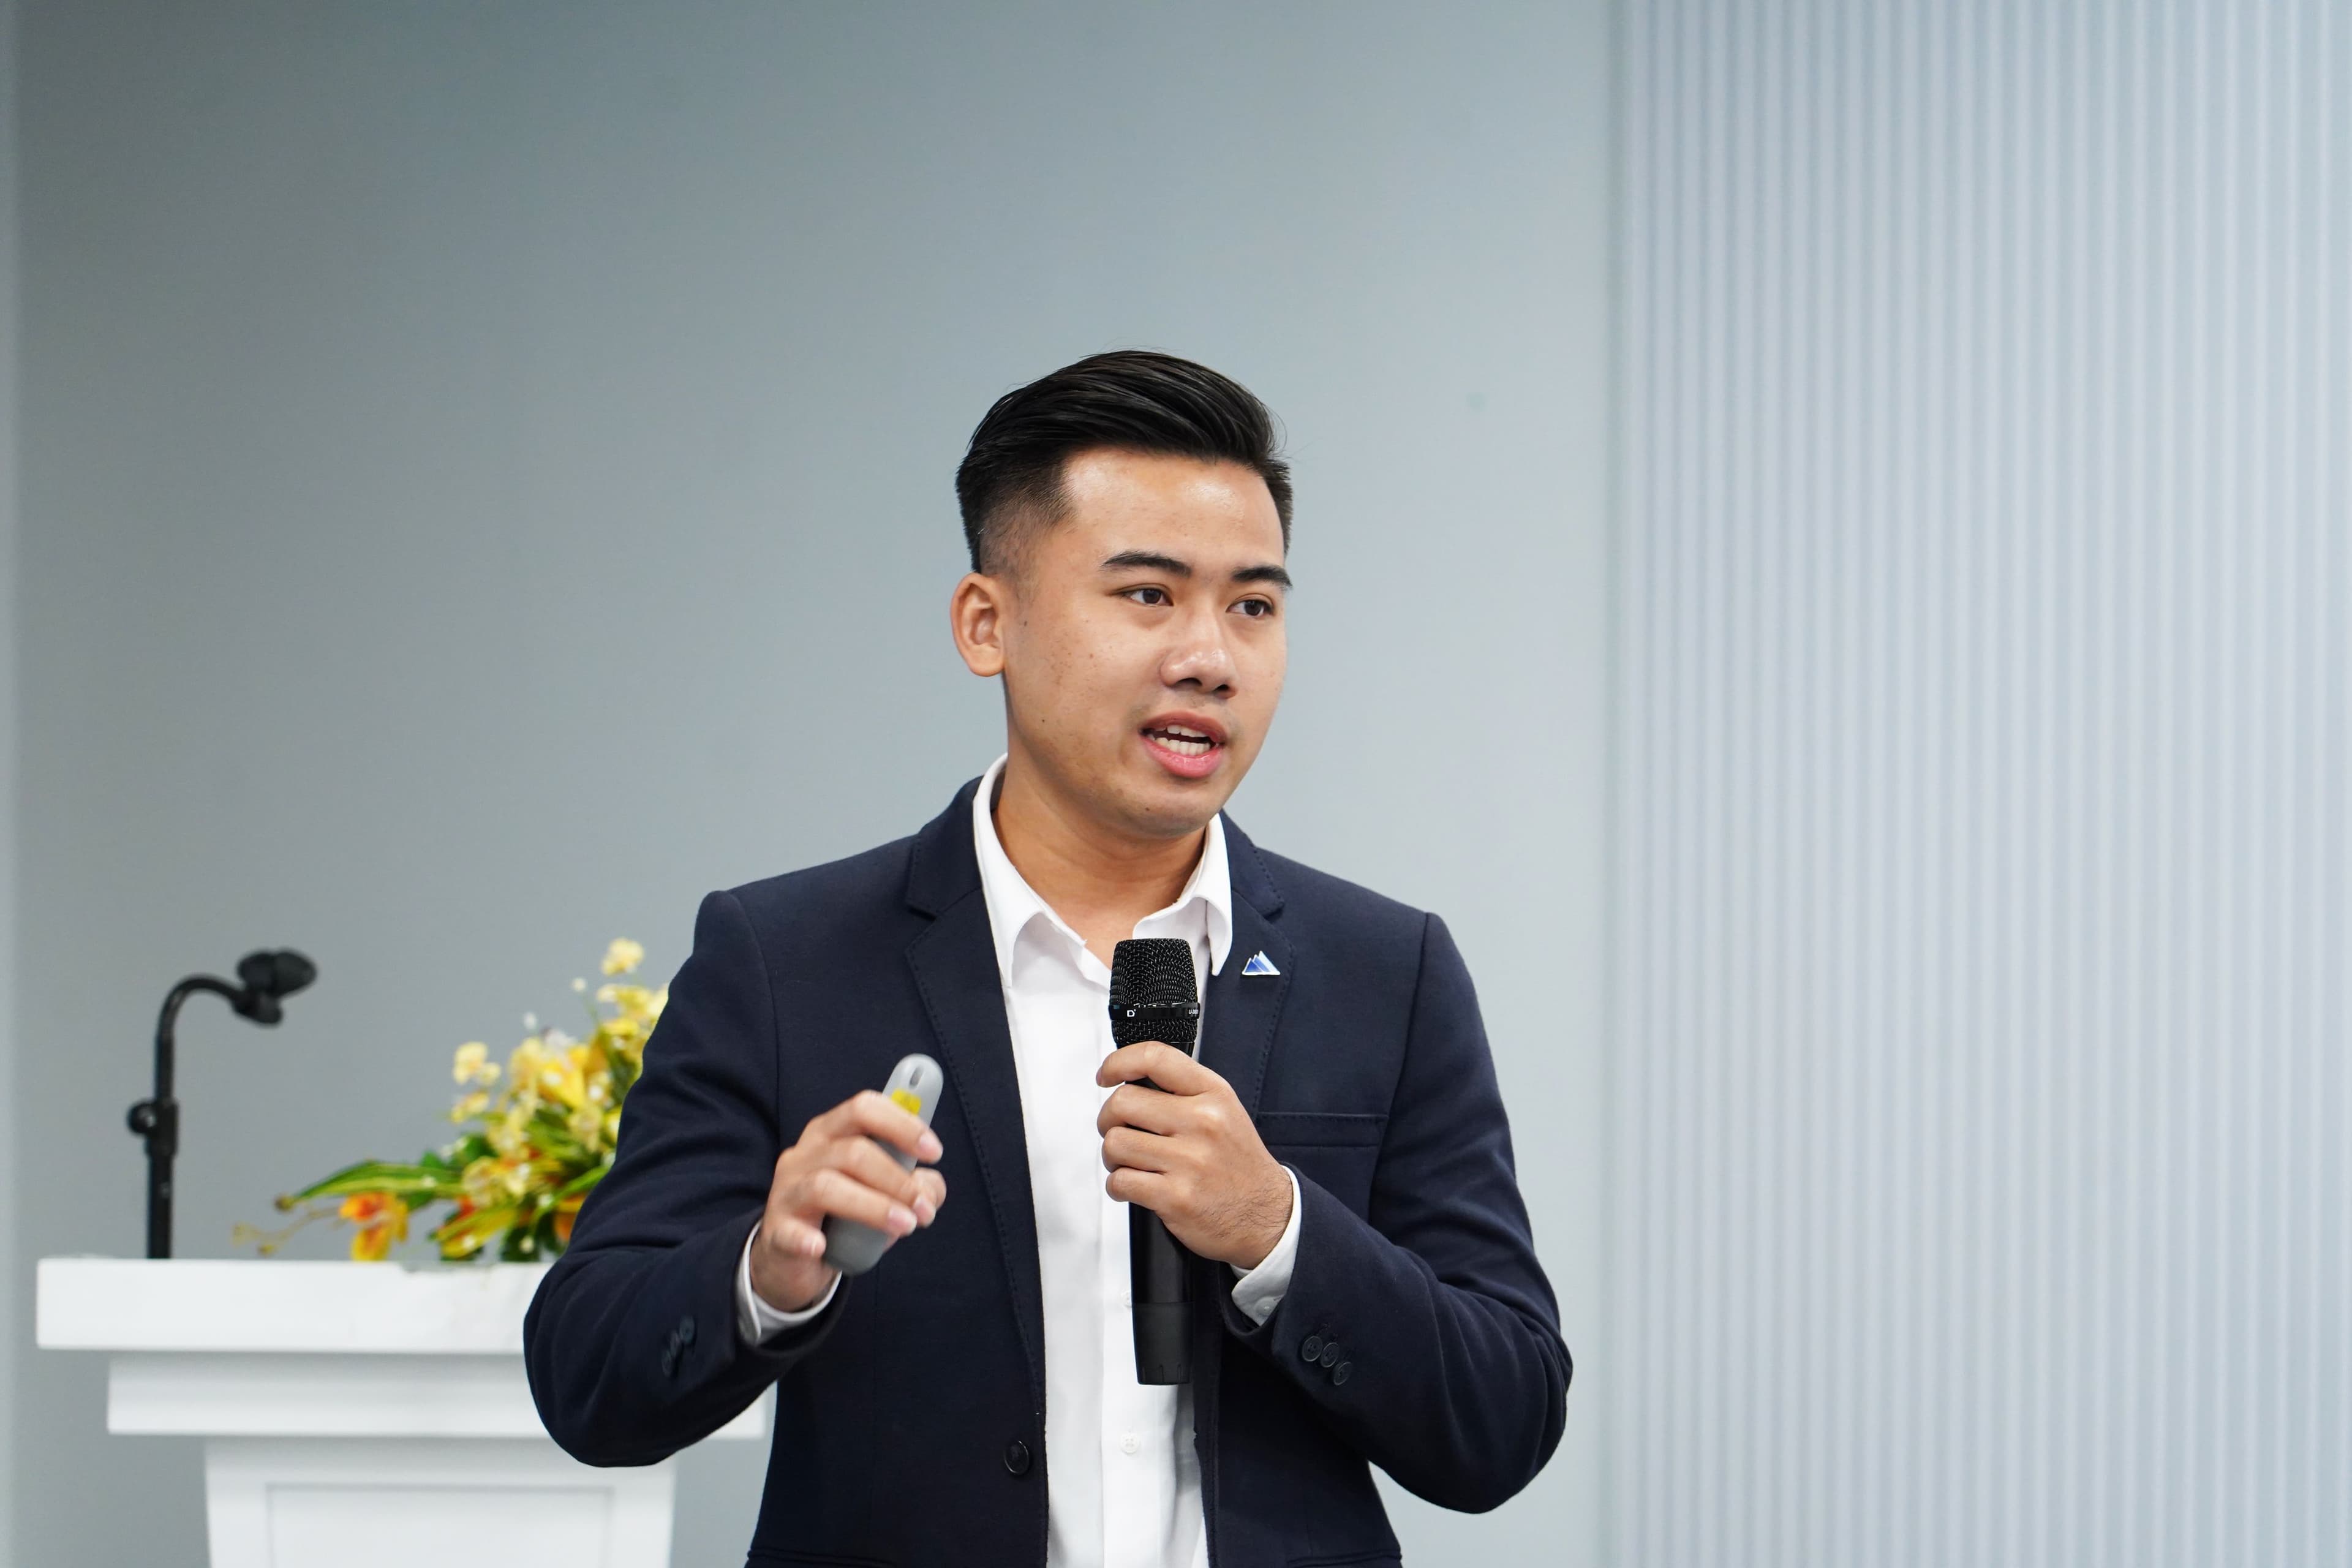
Banjaran Asset Management Shares Insights on Risk Management in CIS at SERC’s 29th Training
Banjaran Asset Management Highlights Risk Management in CIS at SERC’s 29th Securities Sector Training On the morning of April 28, 2025, Mr. Veasna Monireach, Operation Department Representative of Banjaran Asset Management (Cambodia) Plc., delivered an insightful presentation on Risk Management in Collective Investment Schemes (CIS) during the 29th Training, Examination, and Continuing Professional Education event. The event was organized by the Securities and Exchange Regulator of Cambodia (SERC) and held at the Business Development Center. Mr. Monireach’s presentation emphasized the importance of robust risk management practices within CIS operations to ensure investor protection, regulatory compliance, and sustainable fund performance. Through real-world examples and best practices, he highlighted Banjaran's commitment to strengthening Cambodia’s investment fund industry and promoting professional excellence in the securities sector. This engagement underscores Banjaran’s ongoing contribution to the growth, education, and innovation of Cambodia’s financial markets.
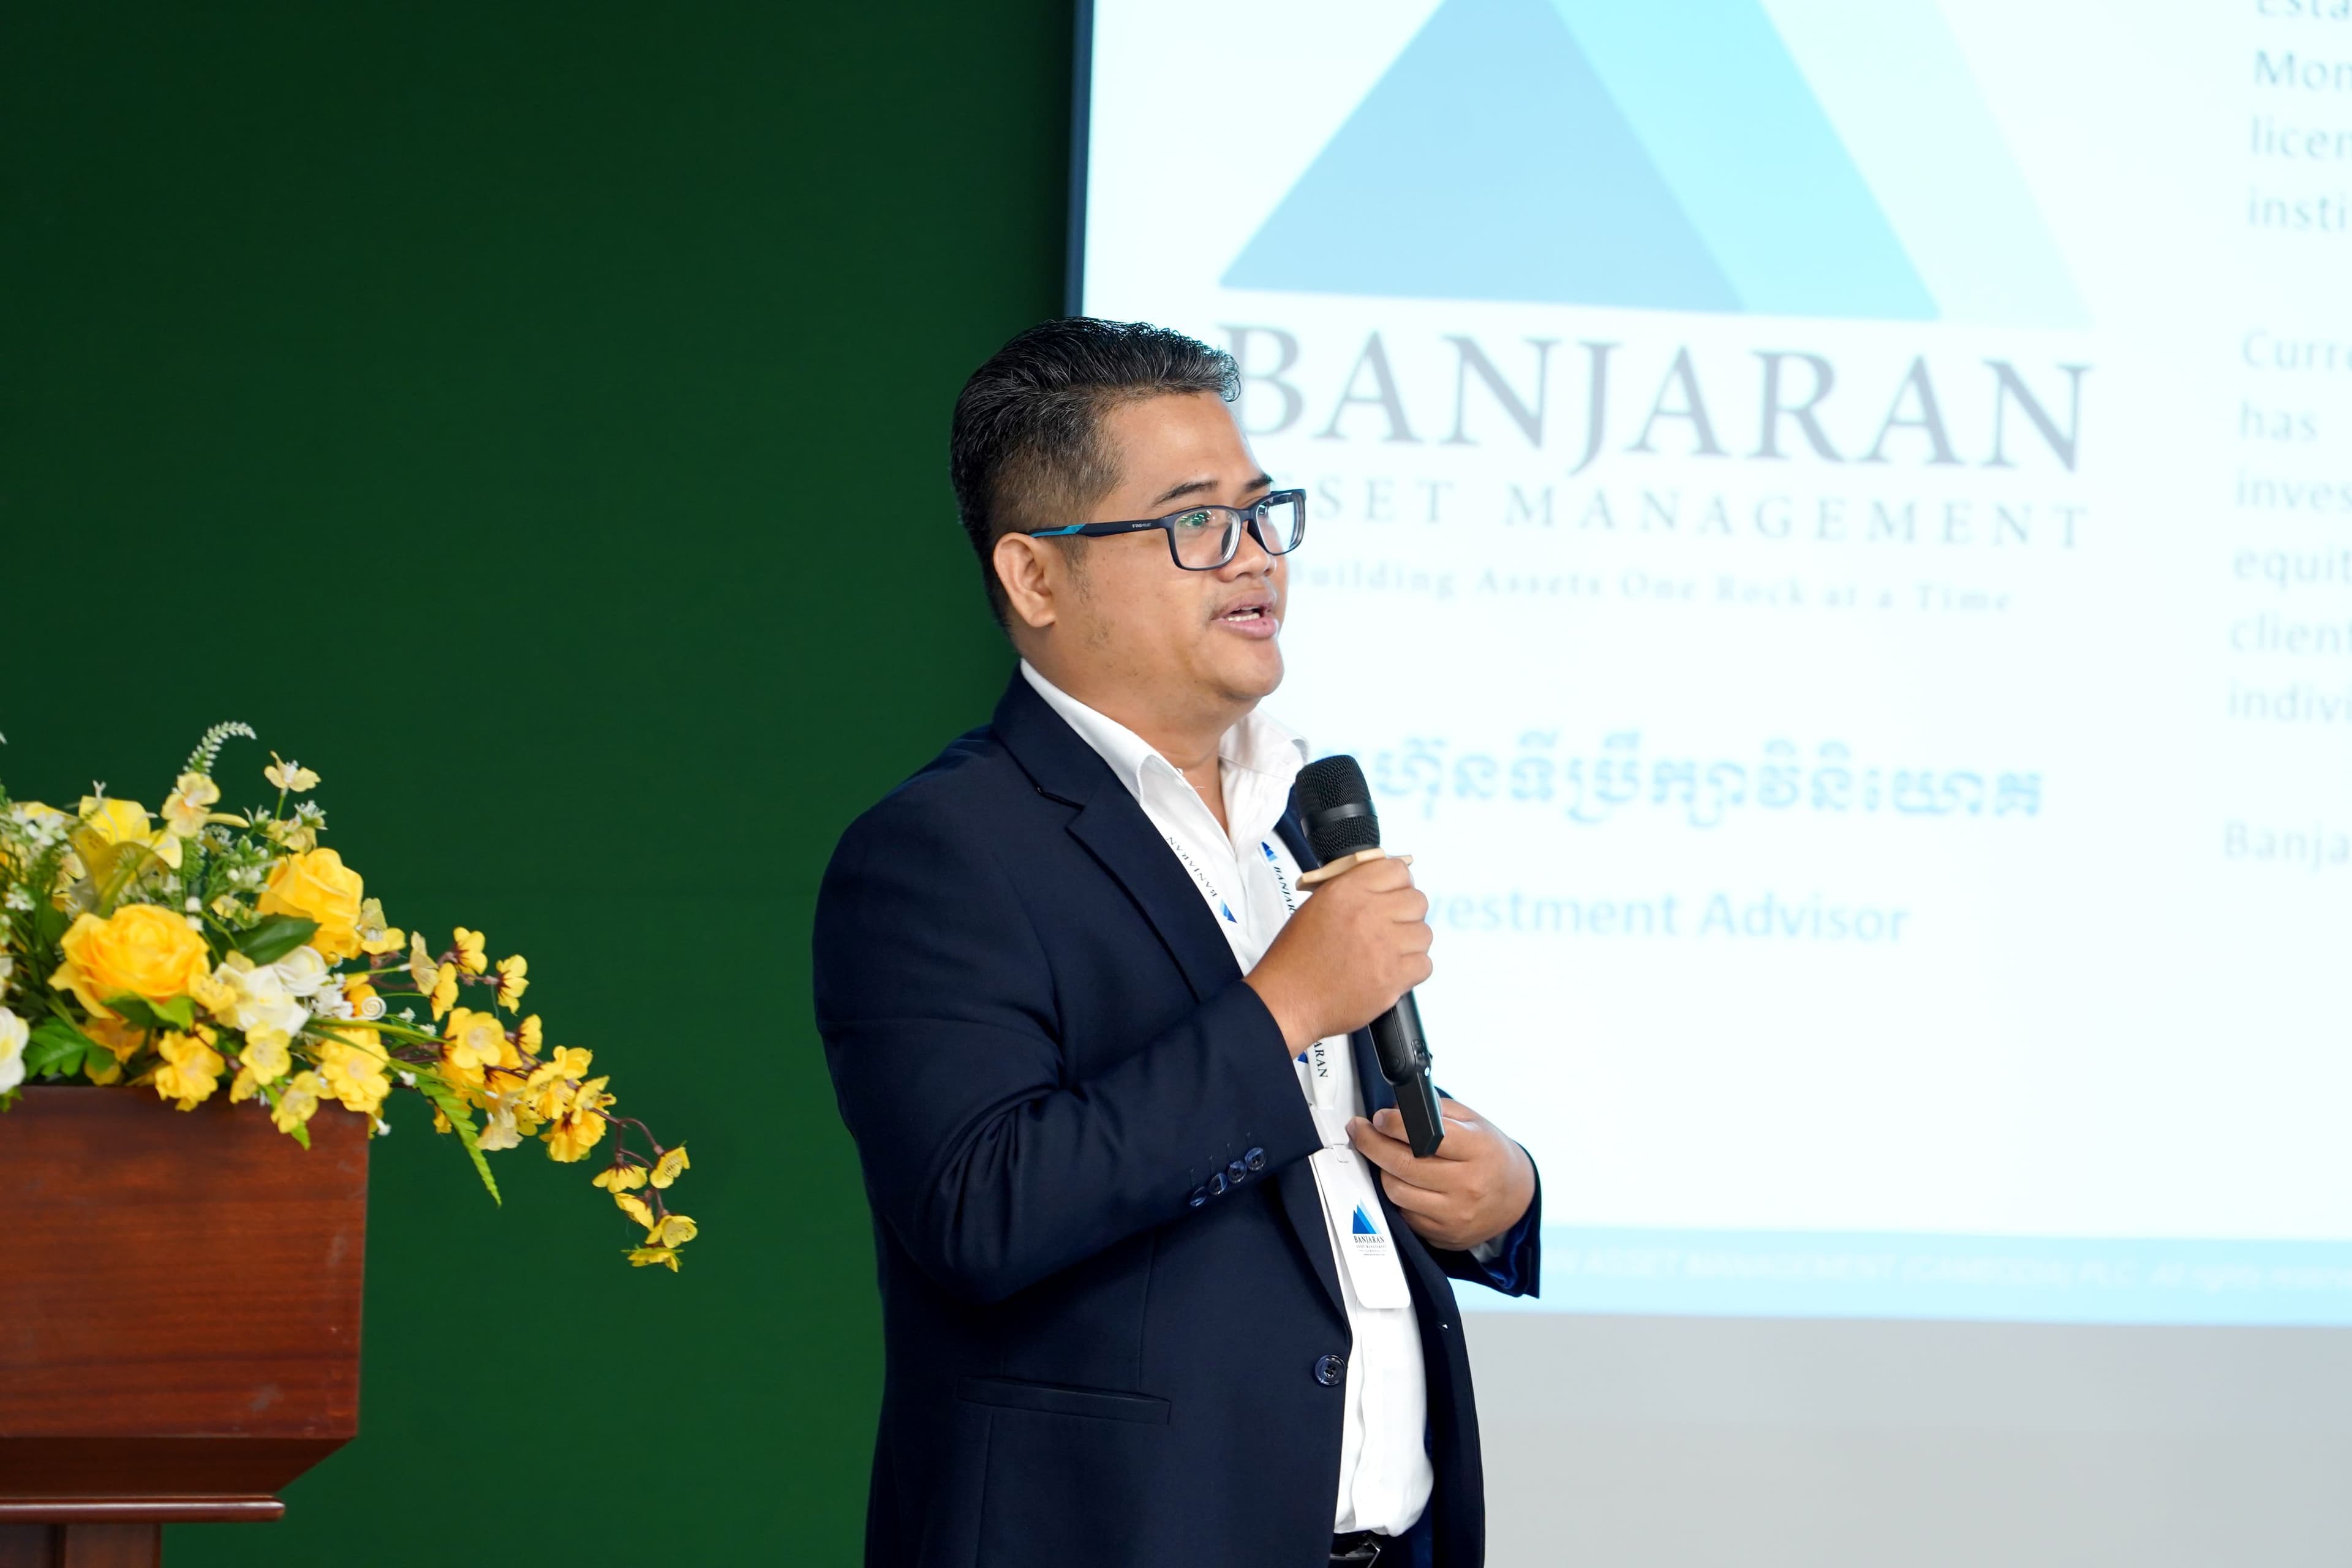
Experience Sharing on Cambodia’s First CIS Fund at SERC’s 29th Securities Sector Training
Banjaran Asset Management Shares Experience on Cambodia’s First Collective Investment Scheme Fund at SERC Event On the morning of April 25, 2025, Mr. Nhem Sopaul, Corporate Manager of Banjaran Asset Management (Cambodia) Plc., delivered a keynote presentation during the 29th Training, Examination, and Continuing Professional Education event organized by the Securities and Exchange Regulator of Cambodia (SERC). The event was held at the Business Development Center, bringing together professionals across Cambodia’s securities sector. Mr. Sopaul shared valuable insights on the Experience of Issuing the First Collective Investment Scheme (CIS) Fund in Cambodia, along with an overview of asset management and fund operations. His presentation highlighted Banjaran’s role as a pioneer in the local fund management space and its commitment to supporting the development of Cambodia’s capital markets through innovation, transparency, and investor education. The event marked another significant milestone in fostering professional excellence and knowledge-sharing in the financial sector, further reinforcing Banjaran’s position as a leader in the Cambodian investment landscape.
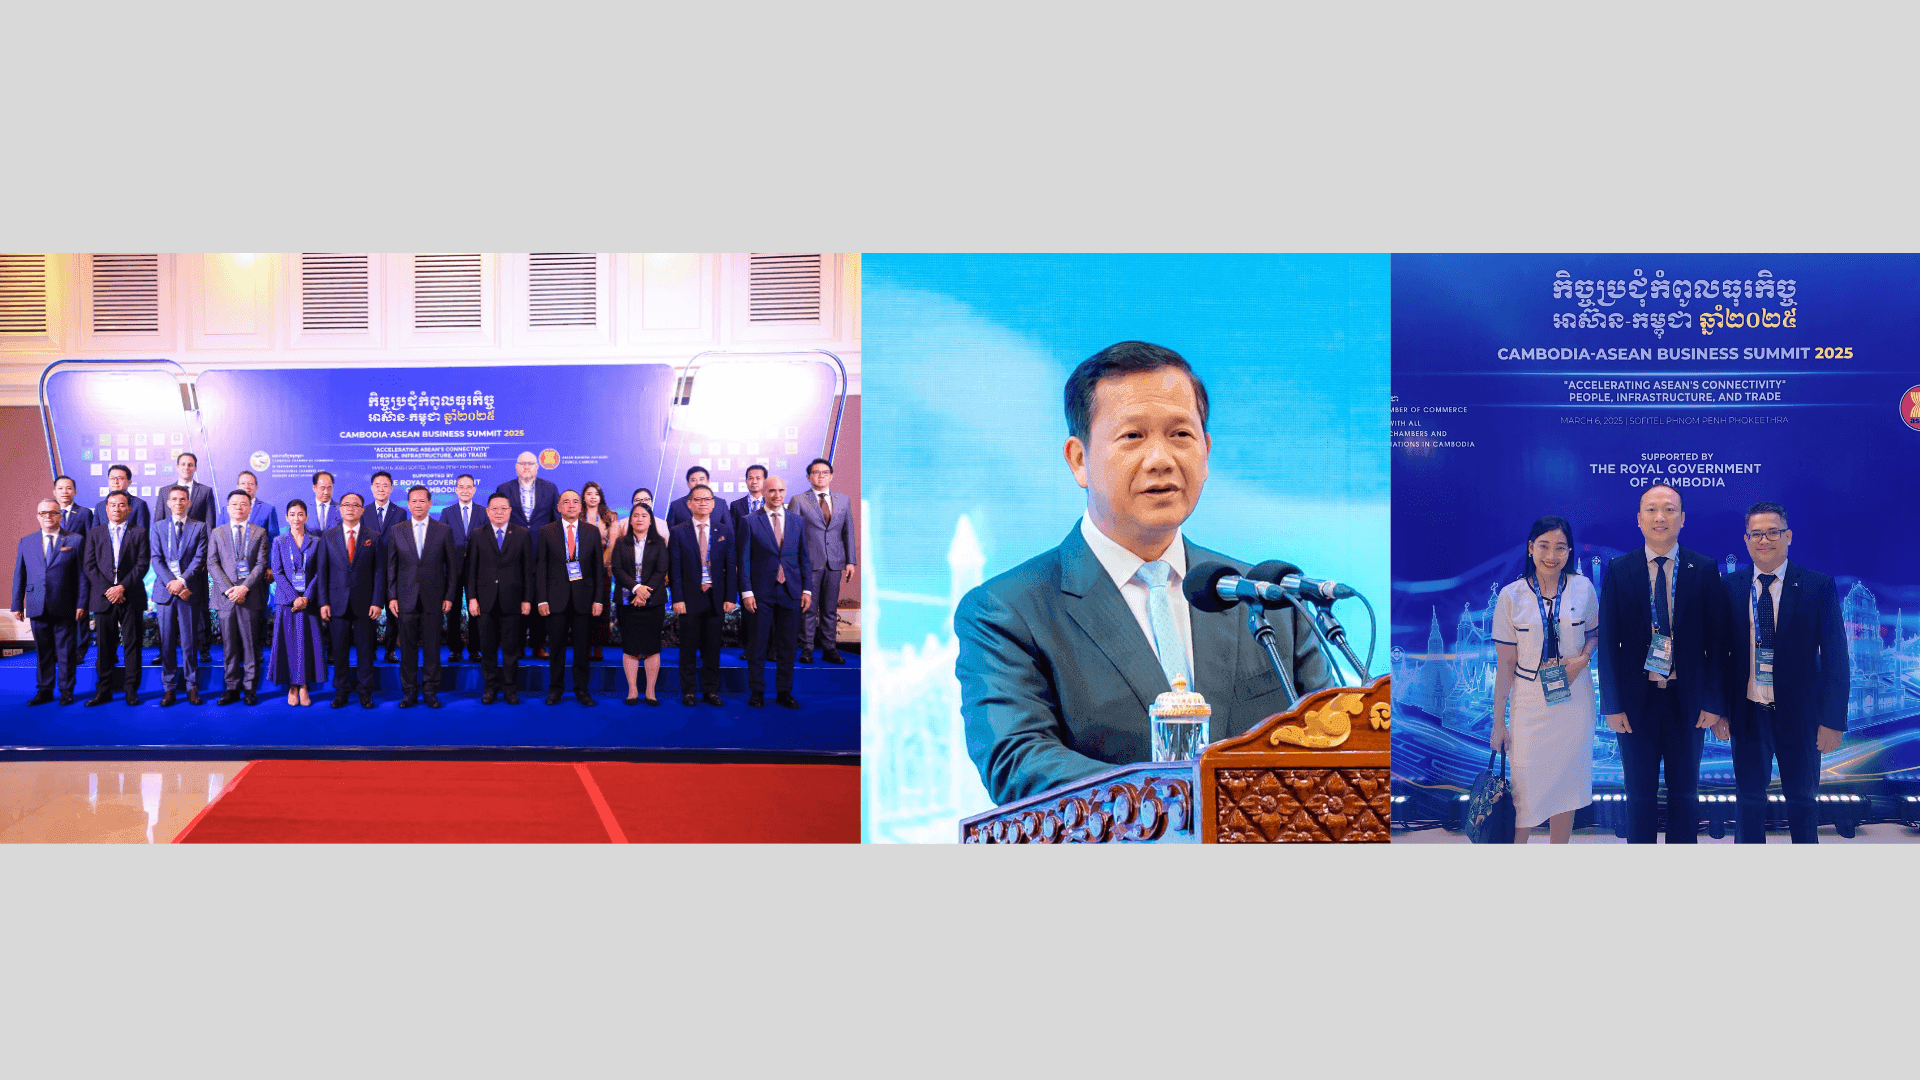
Banjaran Asset Management (Cambodia) Plc. at the Cambodia-ASEAN Business Summit 2025
The Cambodian ASEAN Business Summit 2025: “Accelerating ASEAN’s Connectivity” People, Infrastructure, and Trade The Cambodia ASEAN Business Summit 2025 served as a dynamic platform to foster economic cooperation and development within the ASEAN region, specifically showcasing Cambodia's growing role in regional economic integration. Held at Sofitel Phnom Penh Phokeethra on March 6th, 2025, the summit brought together government officials, business leaders, and experts under the theme "Accelerating ASEAN's Economic Integration." This summit underscored Cambodia's dedication to sustainable and inclusive growth, as outlined in the Royal Government of Cambodia’s policy, while aligning with ASEAN’s overarching economic objectives. The event targeted CEOs, senior executives, entrepreneurs, investors, policymakers, and thought leaders from across ASEAN, representing diverse industries and sectors. It was with great honor that the summit was presided over by Samdech Moha Borvor Thipadei Hun Manet, Prime Minister of the Kingdom of Cambodia. Attendees heard directly from the Prime Minister about the Royal Government’s commitment to supporting ASEAN businesses and fostering shared prosperity. Beyond insightful discussions, the summit provided ample opportunities for networking and collaboration. A networking lunch, accompanied by the Cambodia Investment Showcase, allowed participants to connect with business leaders and explore investment opportunities in key sectors. Additionally, the Business Matching sessions facilitated pre-arranged B2B meetings, fostering potential partnerships and collaborations. The Closing Ceremony summarized key takeaways and issued a call to action for continued collaboration and investment in ASEAN, concluding with a networking reception where attendees further built relationships. The Cambodia ASEAN Business Summit 2025 was a pivotal event, attracting a diverse audience and contributing significantly to accelerating economic growth, strengthening regional integration, and promoting sustainable development in Cambodia and the ASEAN region. The Program of Cambodia ASEAN Business Summit 2025: * Keynote Speeches by H.E. Keo Rottanak, Minister of Mines and Energy Panel Discussion 1: Building ASEAN's Future: Infrastructure Development and Regional Connectivity This panel explored the vital role of infrastructure development in driving economic growth and regional integration within ASEAN. The discussion delved into the importance of physical infrastructure, digital connectivity, and the ASEAN Energy Grid (AEG), focusing on how these elements contribute to a more integrated and prosperous region. Panel Discussion 2: Driving Prosperity Through Trade and Investment This panel examined how ASEAN leveraged trade and investment to drive economic growth and development across the region. Key strategies, initiatives, and partnerships that shaped ASEAN's economic landscape were explored. Panelists: - H.E. Sun Chanthol, Deputy Prime Minister, First Vice-Chairman of the Council for the Development of Cambodia. - H.E. Cham Nimul, Minister of Commerce, Cambodia. - H.E. Kong Vibol, Minister attached to the Prime Minister, Director General of the General Department of Taxation, Cambodia. - Mr. Chan Sopheap, Deputy Director General, General Department of Customs and Excise, Cambodia. - H.E. Sou Socheat, Director General of the Securities and Exchange Regulator of Cambodia. Panel Discussion 3: Human Capital: Key to Trade and Infrastructure Development This panel discussed the critical role of human capital in driving trade and infrastructure development across ASEAN. Prominent voices from ASEAN member states explored how investing in human capital could unlock the region's economic potential. Panelists: - H.E. Heng Suor, Minister of Labor and Vocational Training, Cambodia. - H.E. Hem Vanndy, Minister of Industry, Science, Technology and Innovation (MISTI), Cambodia. - Mr. Parson Lam, Director of Hong Kong Economic and Trade Office in Bangkok, Government of Hong Kong Special Administrative Region. - Mr. Sheanghai Lao, Division Chief Human Resources Officer, Wing Bank (Cambodia) Plc. Moderated by: Mr. Casey Barnett, President of the American Chamber of Commerce in Cambodia (AmCham) Pictures credited to ASSOCIATION OF SOUTHEAST ASIAN NATIONS
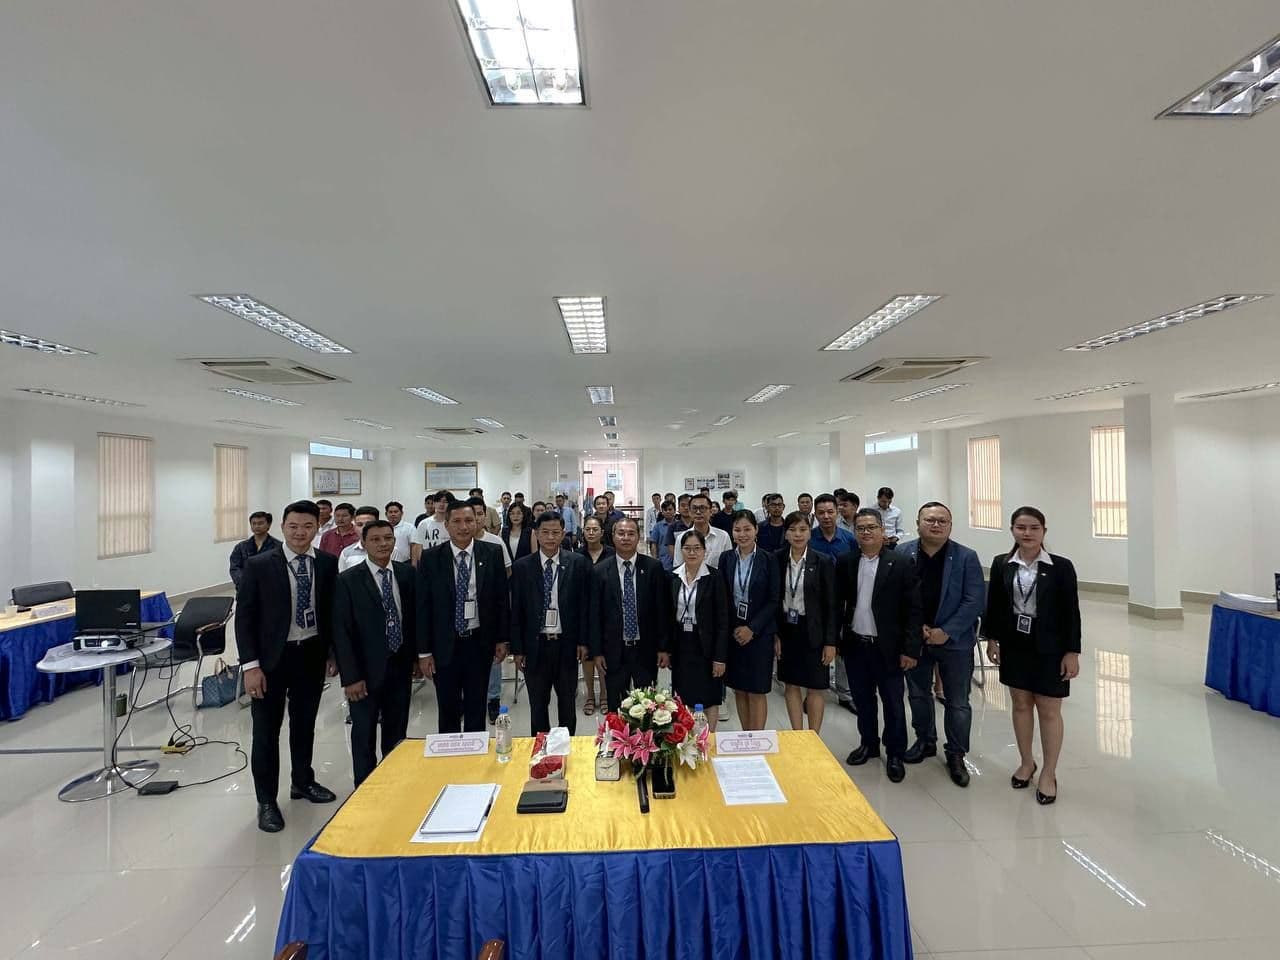
Roadshow Reflections: Insights and Innovations Unveiled
On the morning of December 7, 2024, Banjaran Asset Management (Cambodia) Plc. partnered with ACLEDA Bank Plc., Chamkar Doung Branch, to host the landmark event titled "Cambodia’s First Fund Subscription Roadshow." This pioneering initiative aimed to introduce local investors to the "BAMC Asia Equity Fund (BAEF)," showcasing its potential as a catalyst for capital growth and economic development in Cambodia. The roadshow featured an engaging presentation that outlined the strategic objectives of the "BAMC Asia Equity Fund", emphasizing its focus on high-growth sectors within the region. Attendees were given insights into the fund's investment philosophy, risk management strategies, and expected returns, all tailored to the unique opportunities present in the Cambodian market. Throughout the event, participants had the chance to engage in meaningful discussions with industry experts and gain firsthand knowledge about emerging trends and investment strategies. The roadshow not only highlighted the fund's potential to drive significant economic growth but also reinforced the importance of collaboration between financial institutions and asset management firms in fostering a robust investment landscape in Cambodia. In conclusion, the event served as a pivotal moment for local investors, providing them with valuable resources and insights to navigate the evolving financial market, while highlighting the BAMC Asia Equity Fund's crucial role in driving Cambodia's economic growth, signaling that this is just the beginning, with more exciting opportunities to come.
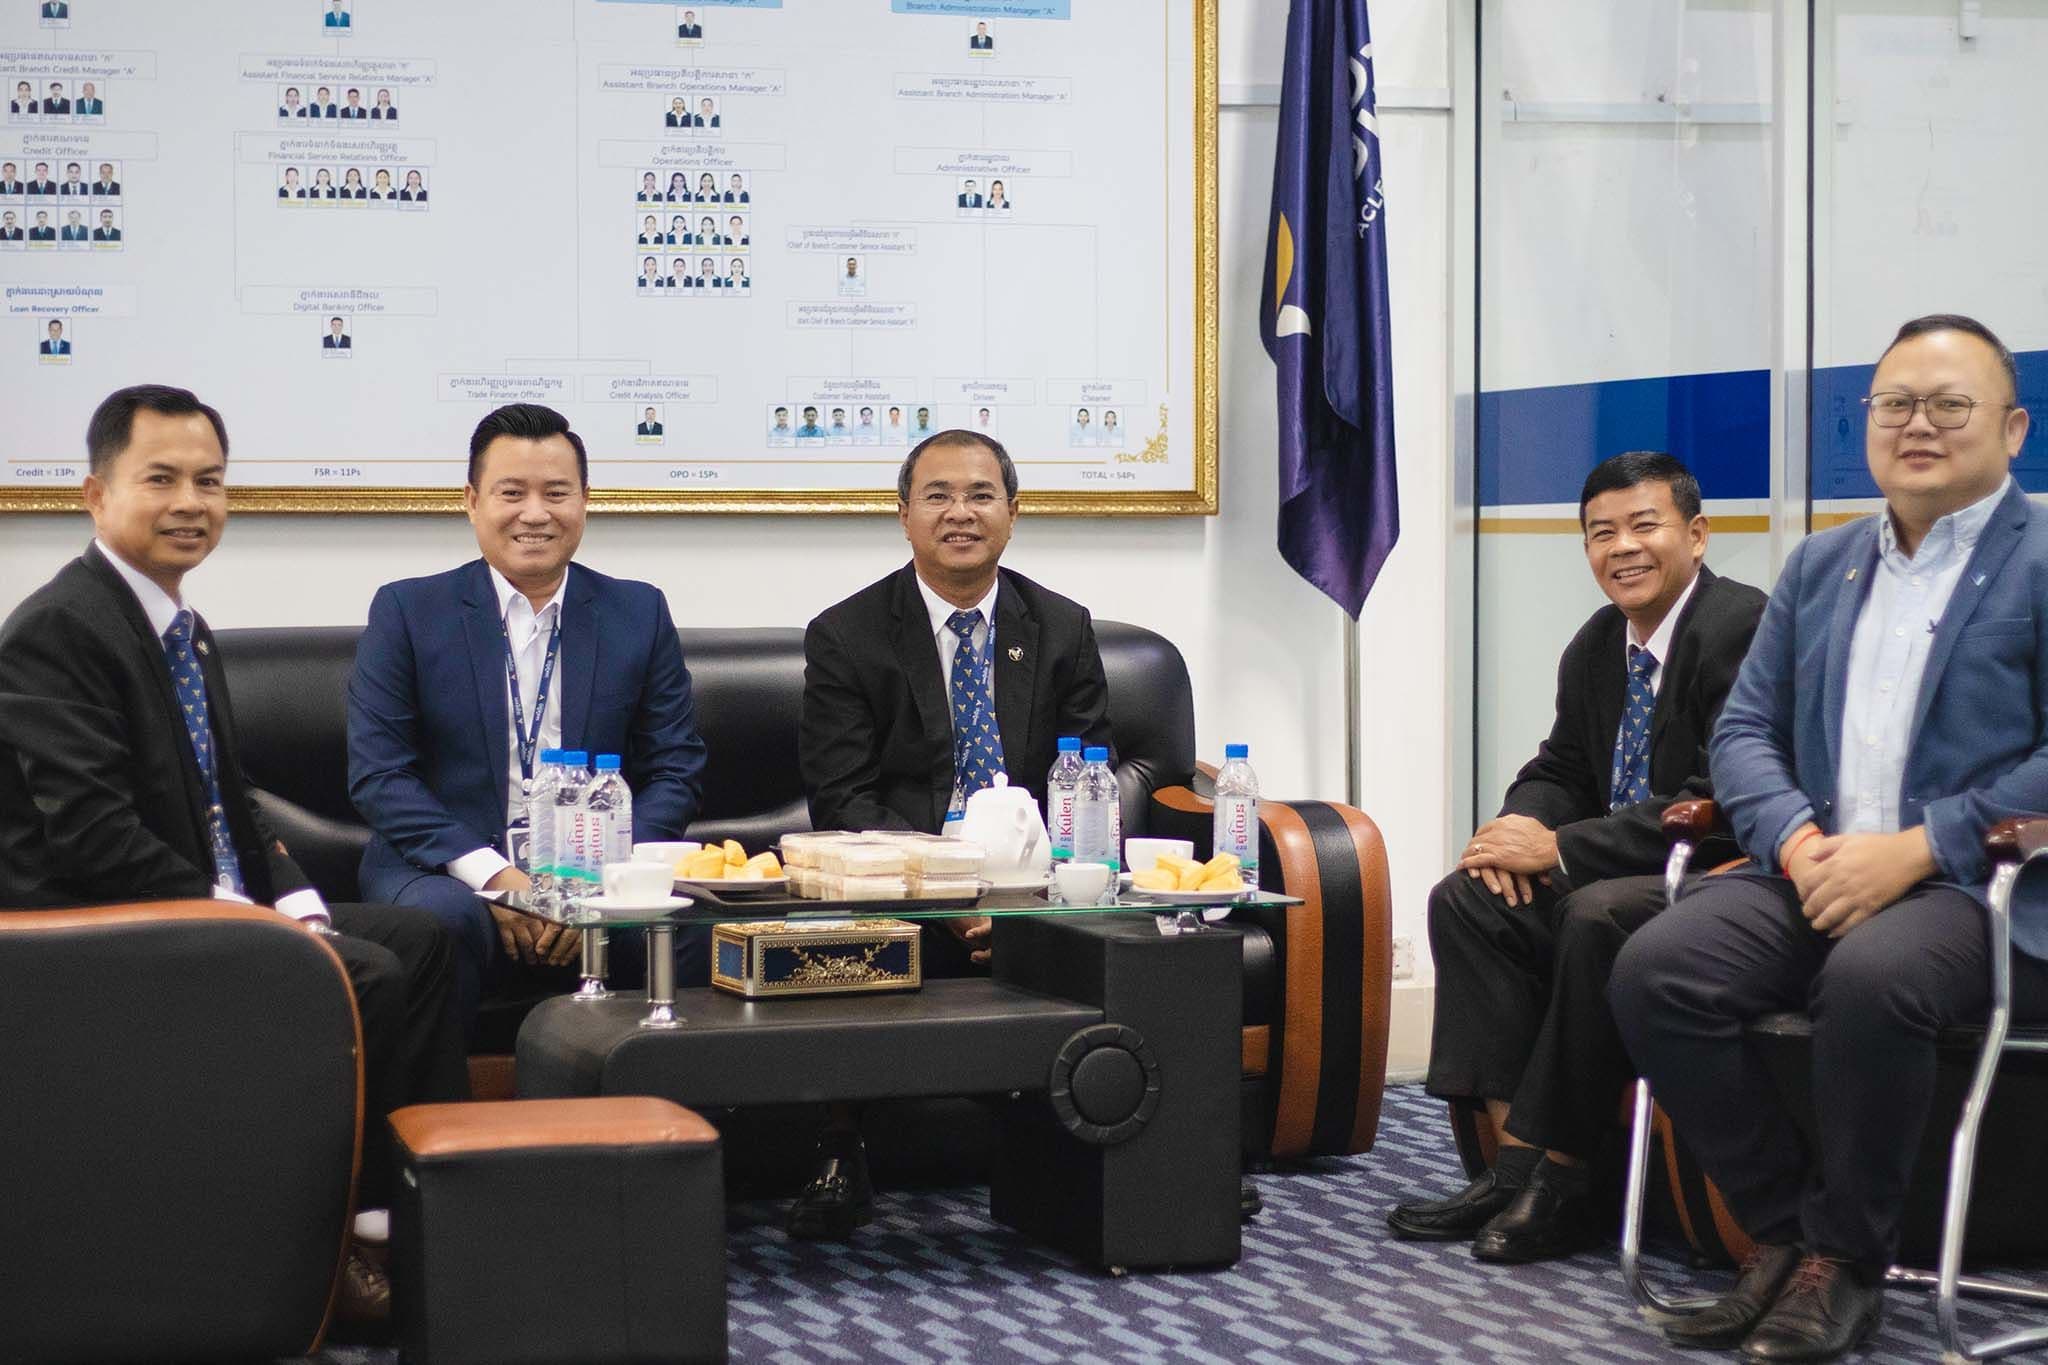
Cambodia's First Fund Subscription Roadshow
On morning, 23rd November 2024, Banjaran Asset Management (Cambodia) PLC. has participated in "Cambodia's First Fund Subscription Roadshow" hosted by Acleda Securities Plc. Through engaging presentations and topic about BAMC Asia Equity Fund (BAEF), we were able to connect and promote the CIS fund to a wide range of participants, marking another significant milestone in Cambodia’s financial market growth.A heartfelt thank you to the organizers and attendees for making this event a success.
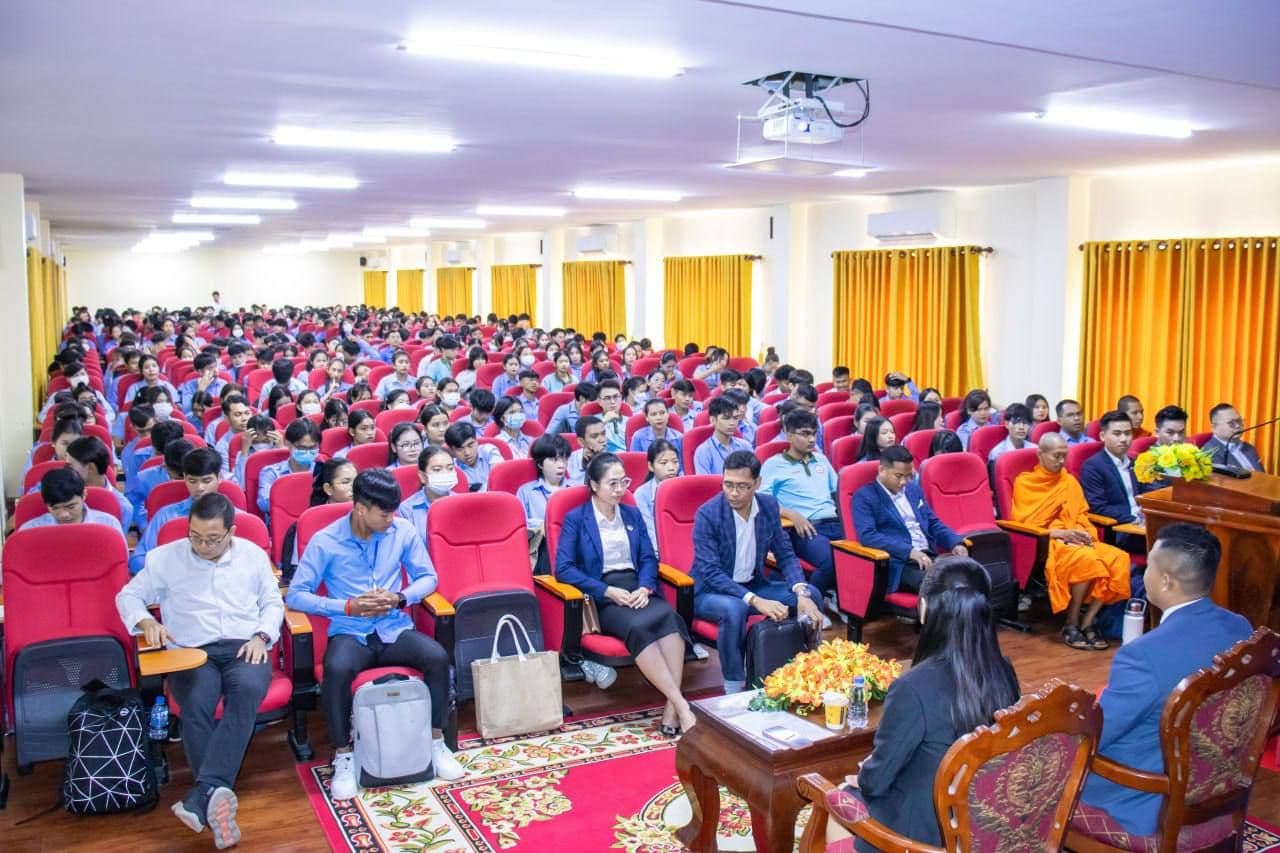
Empowering Future Investors: Banjaran Asset Management's Insightful Collective Investment Scheme (CIS) Fund
On the morning of October 30, 2024, Mr. Sok Chantola, Sales & Marketing Executive of Banjaran Asset Management (Cambodia) Plc., conducted a presentation on the Collective Investment Scheme (CIS) Fund at Preah Sihanouk Raja Buddhist University as part of the “Smart Investing” training program, organized by ACLEDA Securities Plc. The session aimed to deepen attendees’ understanding of CIS investment strategies.
Seminar on Professional Ethics in Collective Investment Schemes with SERC
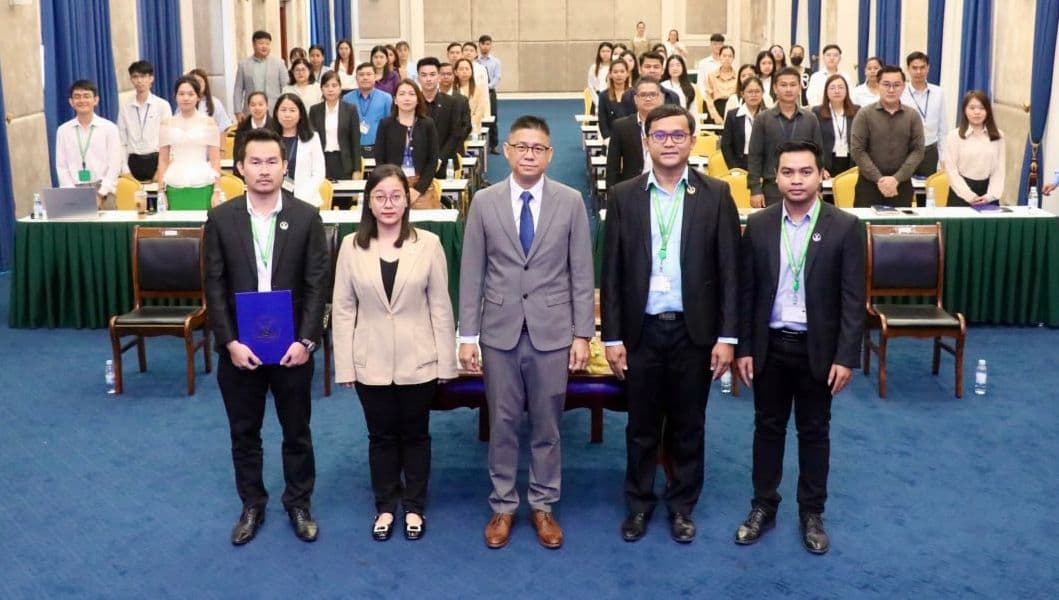
On the morning of Wednesday, corresponding to October 23rd 2024, the Securities and Exchange Regulator of Cambodia (SERC) organized a seminar to promote “Professional Ethics in Collective Investment Schemes” . This seminar was held for fund management companies, custodians, distributors, and trustees, at the building of the Non-Bank Financial Services Authority. The event was presided over by His Excellency Dr. Vin Pakdey , Deputy Director-General of SERC, representing His Excellency Sou Socheat , the Government Delegate in charge as Director-General of SERC. The seminar was designed to provide an opportunity for fund management companies and related businesses to understand the importance of professional ethics, transparency, and responsibility in the collective investment scheme business. It also aimed to ensure that these entities adhere to high standards in their operations, enhancing investor confidence in the financial market. The gathering covered important topics on how ethical practices contribute to sustainable business growth and regulatory compliance, reinforcing the importance of good governance in the financial sector. More Securities and Exchange Regulator of Cambodia
Market Outlook
2025 August Market Outlook: AI and Tech Earnings Fuel Optimism Despite Uncertainty
Investors continue to watch closely for disinflationary indicators and the Fed's response. Despite macro uncertainties, the narrowing credit spread likely indicates the ongoing high investors' risk appetite. The strong earnings from AI-driven tech companies further supported investors' confidence, albeit after a slight June pullback. In Asia, the negative PPI in China reflects Chinese consumers becoming more price-sensitive and cutting back on non-essential spending. Sectors like electric vehicles ("EVs") and food delivery companies have slashed prices to stay competitive. The government launched an "anti-involution" campaign to combat the deepening price wars, and the initiatives such as pricing oversight have shown early signs of effectiveness. Despite this, the Chinese and Hong Kong equity markets have gained, with AI-linked firms and industrial-tech stocks driving market performance. Looking ahead, we remain cautiously optimistic. Despite continued geopolitical tensions and macro uncertainties weighing on sentiment, resilient corporate earnings and tightening credit spreads would likely continue to support the global equity markets, notably in the AI and tech sectors. Meanwhile, we believe the Fed will remain cautious, closely watching sticky inflationary indicators; if inflation continues to ease, gradual rate cuts are likely. In spite of trade reroutes and structural market challenges leading to overcapacity, Asian equity markets performed better than expected, supported by a strengthened macro backdrop. Against this landscape, we maintain a disciplined and balanced approach, grounded in bottom-up fundamental analysis in our portfolio construction.
2025 July Market Outlook: Resilient Earnings and Renewed Trade Ties Keep Investor Confidence Intact
Since June, investor sentiment has gradually improved, supported by resilient corporate earnings, stronger-than-expected macroeconomic indicators, and measured progress in trade diplomacy. Despite lingering policy uncertainty and geopolitical risks, market conditions have remained relatively calm, with volatility largely contained. Trade policy continues to be a central concern. The Trump administration’s 90-day pause on tariffs is set to expire on August 1, with proposed tariffs of up to 50% on autos and consumer electronics still under consideration. However, in spite of looming tariff risks, the successful negotiation of bilateral trade agreements - with Japan, the U.K., and South Korea - has helped bolster investor confidence. The U.S. - Japan deal, which includes a reported US$550 billion investment commitment, has further supported sentiments across Asian markets, which benefits from improved trade ties and regional policy coordination. Meanwhile, the One Big Beautiful Bill (BBB Act), which offers generous tax incentives - including permanent R&D deductions and 100% expensing of production property - has provided notable support to the technology, semiconductor, and data center sectors. While the BBB Act raises concerns over fiscal deficits, it has already helped sustain momentum in pro-growth and AI-exposed equities. In Asia, China’s Q2 GDP growth exceeded expectations, underpinned by strong industrial output and a rebound in exports, driven in part by front-loaded shipments ahead of potential new tariffs. However, weakness in retail sales and property investment underscores China’s continued reliance on external demand and industrial production over domestic consumption - raising expectations for further targeted fiscal support in the second half of 2025. Looking ahead, we remain cautiously optimistic. While U.S. headline CPI rose in June, disinflationary trends are still evident in core components. Profitability remains strong in key sectors, and Asia continues to benefit from trade gains and pro-growth policies. However, with valuation multiples remaining elevated, the upcoming earnings season will play a pivotal role in supporting the valuation premium. With liquidity conditions stable and market volatility subdued, we maintain a disciplined and balanced approach, guided by bottom-up fundamental analysis in our portfolio construction.
2025 June Market Outlook: Resilient Markets in a World of Risk
Since May, markets have continued to operate in an environment marked by policy uncertainty and rising geopolitical risks. The Trump administration’s 90-day pause on “Liberation Day Tariffs” offered temporary relief, but limited progress in broader trade talks - especially with the EU and Japan - has kept investors cautious. While a limited agreement with the U.K. was reached, the overall trade landscape remains unresolved, affecting sentiment and weighing on risk appetite. Geopolitical tensions escalated in June, particularly with the Israel-Iran conflict. Iran’s threat to close the Strait of Hormuz - a key route for around 20% of global oil supply - triggered a sharp rise in oil prices. This has increased concerns about supply disruptions, global shipping rerouting, and broader instability in the region. The timing of this conflict has added complexity to the inflation outlook. Central banks, including the Fed, were preparing for a potential shift toward easing. However, the surge in oil prices has introduced new uncertainty. In its June meeting, the Fed held rates steady and signaled only one possible cut for the rest of the year, citing persistent services inflation and elevated geopolitical risks. A prolonged conflict could keep oil prices elevated, which may delay or limit policy easing. Concerns over U.S. fiscal stability, driven by political gridlock and unresolved budget discussions, have added to the uncertainty. Despite these challenges, we maintain a cautiously optimistic outlook. Disinflationary trends are taking hold, and market volatility has stayed relatively contained. With a potential easing in tariff tensions, expectations of reduced geopolitical friction, and supportive fiscal and probusiness policies in China and the U.S., global equities are expected to continue recovery. Against this backdrop, we maintain a disciplined and balanced approach, guided by bottom-up fundamental analysis in our portfolio construction.
2025 May Market Outlook: Navigating Volatility Amid Trade Tensions and Monetary Policy Caution
Global Markets The global stock market, as represented by the MSCI World Index, rose 0.74% in April. Gains were primarily driven by robust performance in non-U.S. equities and a temporary easing of global trade tensions. While U.S. markets experienced sharp mid-month volatility following the announcement of sweeping new tariffs, a partial rollback—excluding China—helped restore investor confidence. Resilience in large-cap technology stocks and a rotation into defensive sectors also contributed to gains. Additionally, expectations of monetary easing in select developed markets outside the U.S. provided a tailwind, helping global equities recover despite ongoing geopolitical and trade-related uncertainty. General Outlook and Views April began with heightened volatility following the surprise rollout of the “Liberation Day Tariffs,” which included a blanket 10% levy on all imports and steeper country-specific rates. Markets reacted swiftly—equities tumbled, and Treasury yields dropped as risk-off sentiment took hold. A temporary rebound followed the U.S. decision to pause most tariffs, excluding those on China. However, China’s swift retaliation reignited trade tensions, pulling markets lower once again. Despite the volatility and uncertainty, equities have since staged a robust recovery, supported by a tentative trade truce between the two economic powers. Investor sentiment was buoyed by the prospect of renewed negotiations, contributing to a broad-based rally. Meanwhile, the Federal Reserve opted to keep interest rates unchanged, adopting a cautious, data-dependent approach as it assesses the broader impact of trade disruptions. Recession risks, however, remain elevated amid subdued consumer sentiment, persistent macroeconomic headwinds, and the fragile state of U.S.–China trade negotiations. The Fed’s decision to hold rates steady reinforces its wait-and-see stance, while the recent credit rating downgrade by Moody’s has drawn renewed attention to the U.S.’s long-term fiscal vulnerabilities—adding another layer of uncertainty to the market outlook. Nonetheless, we remain cautiously optimistic. While the broader economic landscape remains clouded by trade policy uncertainty and political volatility, the possibility of continued U.S.–China engagement offers some hope for de-escalation and market stabilization. Against this backdrop of fragile trade dynamics, tightening fiscal credibility, and a patient Fed, we remain focused on navigating near-term volatility through disciplined portfolio positioning. We continue to monitor developments closely, recognizing that trade relations, monetary policy, and political developments will remain key drivers of global growth and market stability in the months ahead. Given the current environment, we believe it remains prudent to refrain from significant portfolio shifts until greater policy clarity emerges.
2025 April Market Outlook: Tariff Shocks Rate Dilemmas and China’s Next Move
US tariff announcements have introduced a wave of uncertainty into global markets. While the initial shock caused equities to retreat sharply, sentiment steadied somewhat after the US paused broad-based tariffs for most countries, leaving China as the primary target for higher levies. This erratic policy approach has unsettled businesses and investors alike, with US Treasury yields responding with unusual speed. We are keeping a close eye on trade negotiations, particularly those involving China, as their outcomes could significantly influence market direction in the coming months. Meanwhile, the Federal Reserve’s decision to hold interest rates steady comes amid mixed signals from the economy. Strong consumer spending and a resilient labour market suggest underlying strength, but inflationary pressures remain a persistent concern. Political calls for rate cuts have added to the noise, yet the Fed’s next steps remain uncertain. For now, we are watching closely to see how these dynamics unfold, as the interplay between economic data and policy decisions will be critical in shaping the path ahead. In China, the investment climate remains somewhat cloudy amid ongoing tensions with the US. While fiscal stimulus measures announced during the Two Sessions meeting provide some support, including efforts to boost consumption and bolster key industries, we believe there is scope for further measures in the coming months.
2025 March Market Outlook: Cautious Optimism Amid Policy Shifts and Economic Uncertainty
The conclusion of China’s Two Sessions has injected optimism into the Chinese and Hong Kong markets. Key policy measures include maintaining a 5% growth target and increasing deficit spending to 4% of GDP. Beijing has also pledged greater support for the private sector and cutting-edge technologies. Investors’ reaction to these announcements have been positive so far as the government is shifting priority to restoring the private sector and help drive economic growth. In our view, this positive momentum is still in its early stages, given how negative global sentiment towards China has been over recent years. US-led trade tariff hikes have introduced significant political and economic uncertainty, primarily through passing higher costs for consumers and businesses, alongside the threat of retaliatory measures from trading partners. This has contributed to market instability and has dampened business optimism. We are cautious about trade-related developments due to their potential impact on global supply chains. However, we believe it is too early to make significant portfolio adjustments, as supply chains have historically demonstrated resilience to changing conditions. US consumer sentiment has dropped suddenly as rising inflation expectations weigh on confidence. Consumers are growing more cautious with spending, fearing a decline in purchasing power. This hesitation is reinforced by slowing economic indicators such as retail sales. A closer look at the data reveals a significant decline in sales at food service establishments, which could signal weakening consumer demand. We will closely monitor whether this is a temporary fluctuation or the beginning of a broader negative trend. At this time, we are still comfortable with our risk positioning, which remains well-diversified across various sectors and regions.