

Insights
Explore the latest news, expert articles, and market outlooks to stay ahead of industry trends.
Newsroom
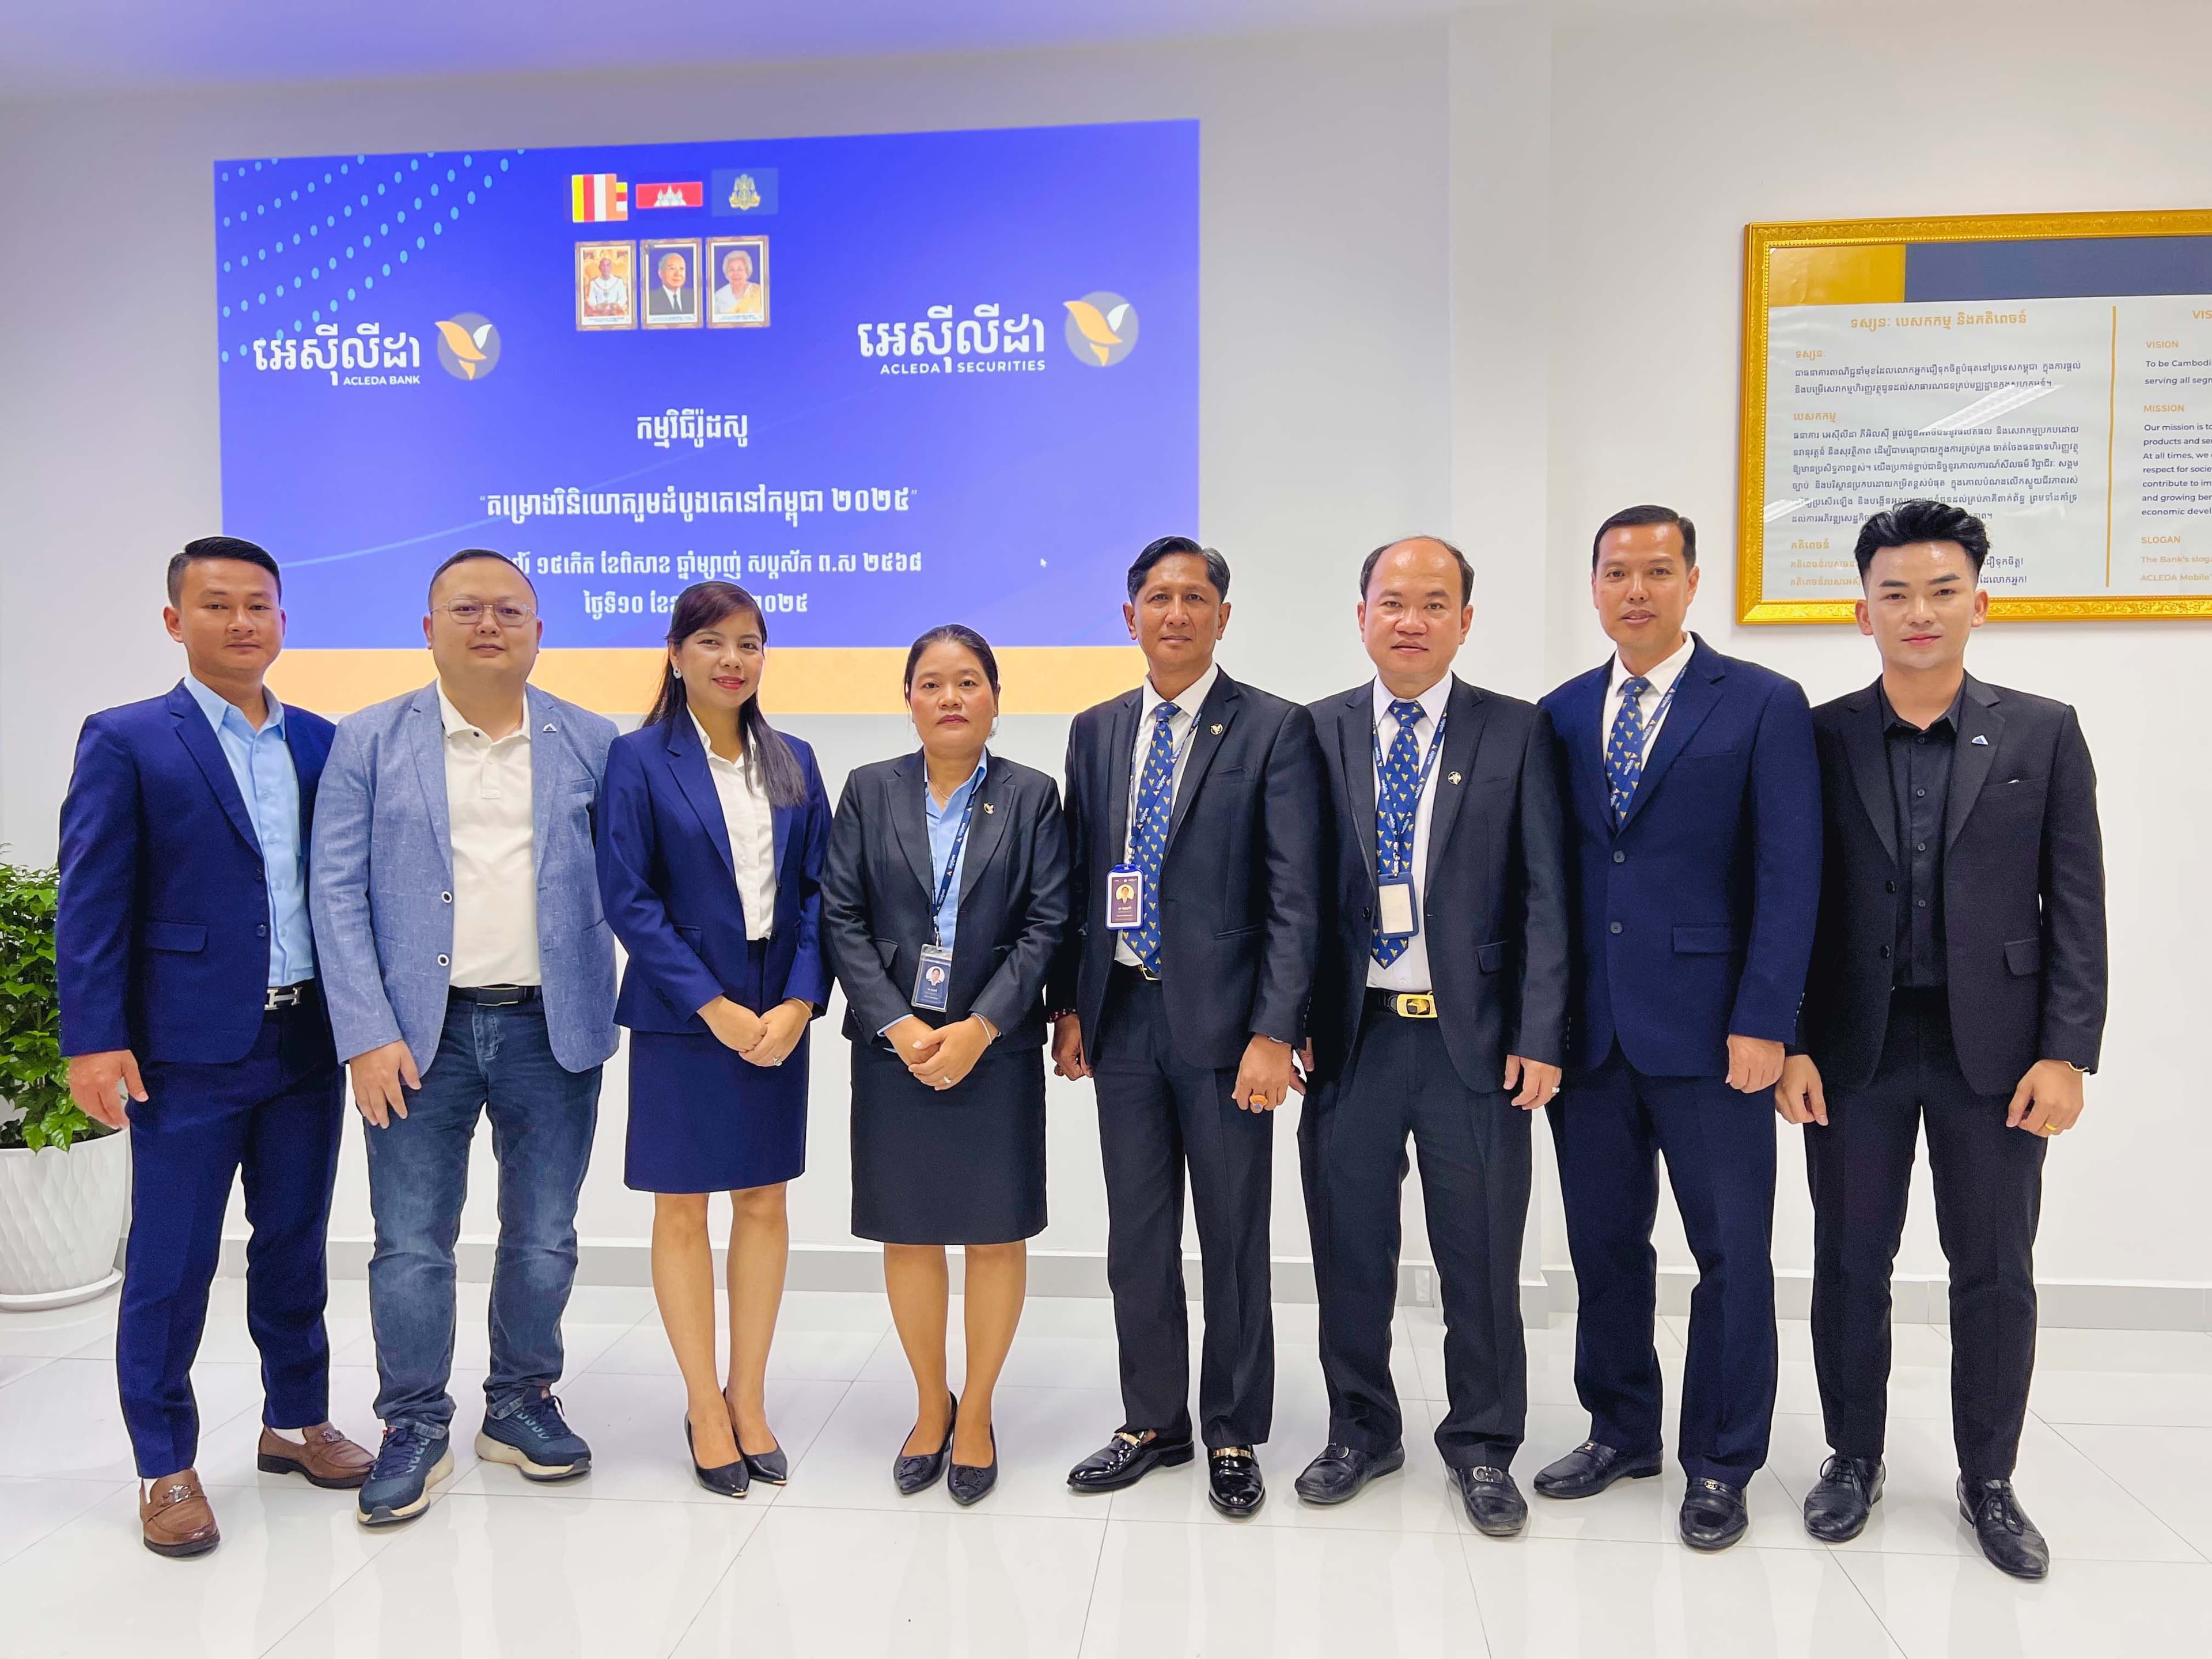
Cambodia's First Fund Roadshow 2.0, a Success in Prey Veng
Phnom Penh, Cambodia – May 10, 2025 – The second leg of Cambodia’s First Fund Subscription Roadshow 2.0 concluded successfully on 10 May 2025, at ACLEDA Bank Plc. in Prey Veng province. The initiative, a collaborative effort between Banjaran Asset Management (Cambodia) Plc. and ACLEDA Securities Plc, also included participation from several local ACLEDA Bank branches, including Pea Reang, Svay Antor, and Peam Ro. Banjaran AMC expressed their gratitude to all attendees for their support in making the event a success. The roadshow aims to introduce the BAMC Asia Equity Fund (BAEF) to a wider audience across Cambodia. Following the successful event in Prey Veng, the roadshow is set to continue its journey, bringing investment opportunities to more provinces throughout May and June 2025.
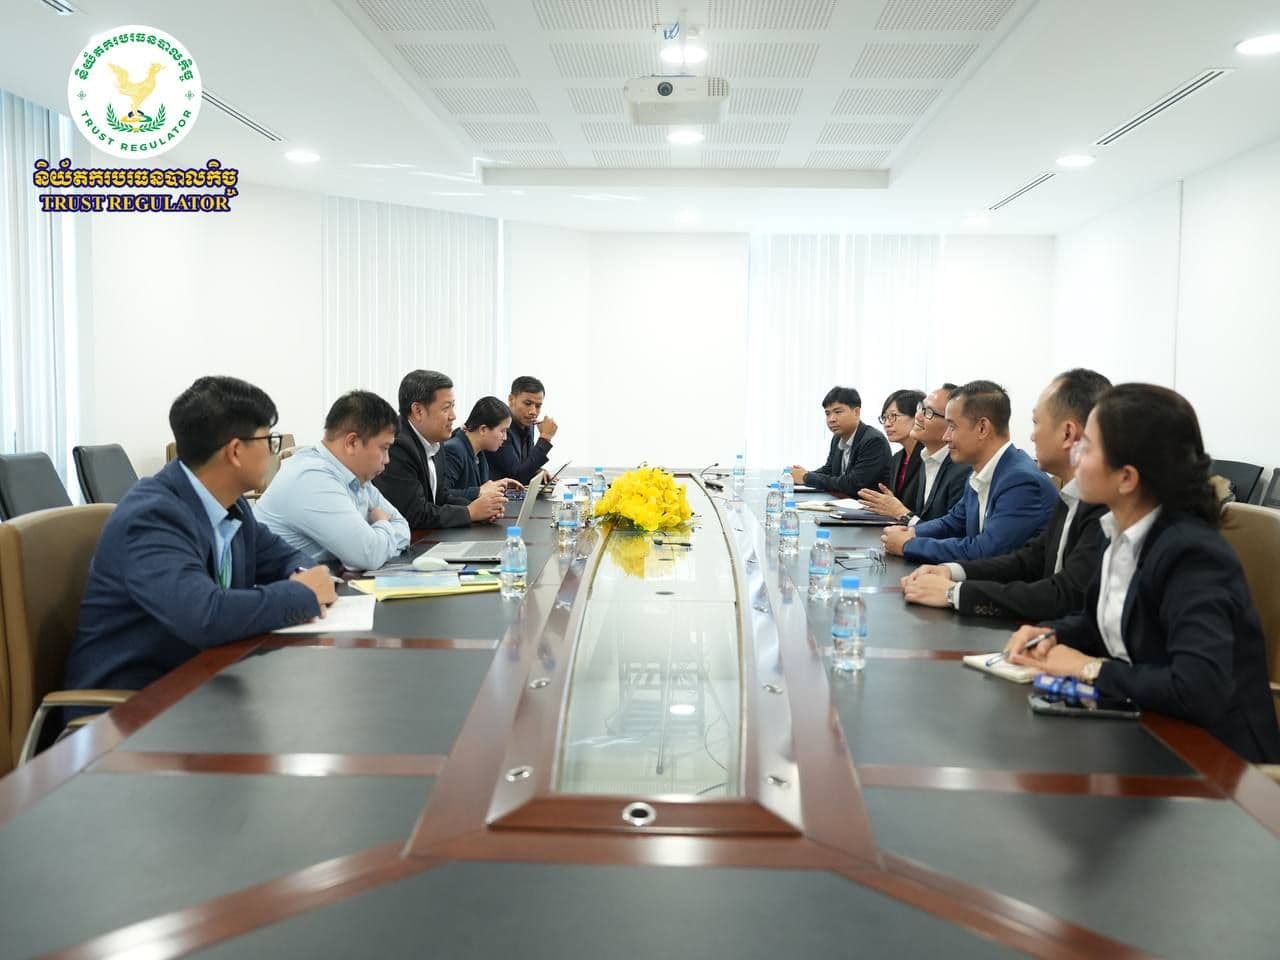
Mr. Eric Loo, CEO of Banjaran Asset Management (Cambodia) Plc., Participates in High-Level Meeting with Trust Regulator on Non-Bank Financial Sector Development
Phnom Penh, Cambodia – May 7, 2025 – Banjaran Asset Management (Cambodia) Plc., represented by its CEO, Mr. Eric Loo , alongside Lion Trust Group, held a pivotal high-level meeting with the Cambodia Trust Regulator (TR). Chaired by His Excellency Sok Dara, Director General of the TR , the session focused on advancing the non-bank financial sector and strengthening Cambodia’s regulatory framework. The strategic discussion highlighted a shared commitment between regulators and industry leaders to foster growth, innovation, and long-term trust in the Kingdom's financial ecosystem. A central focus of the meeting was the Trust Regulator's (TR) strategic emphasis on expanding trust structures, particularly family trusts, as a cornerstone of asset protection and intergenerational wealth transfer. For asset managers like Banjaran AMC, these frameworks serve as vital mechanisms to help high-net-worth individuals and businesses secure long-term financial stability while ensuring smooth succession planning—a growing priority in Cambodia’s evolving economic landscape. This dialogue aligns closely with the Trust Regulator's (TR) ongoing market development efforts, such as their recent “Family Trust for Succession Planning” seminar held on April 29, 2025, at Sokha Hotel, Phnom Penh. Organized in partnership with Phillip Trustee (Cambodia) and Phillip Capital (Singapore), that session provided deep insights into regional best practices, offering tailored strategies that firms can leverage within the local market. Reflecting this proactive environment, Banjaran AMC’s active engagement with the TR underscores its commitment to shaping a dynamic, sophisticated, and inclusive trust sector in Cambodia. By maintaining a close collaborative relationship with regulators, the firm aims to develop innovative financial solutions that directly address the wealth preservation needs of local families and institutional investors. This momentum builds upon continuous regulatory engagement, including a previous baseline dialogue between His Excellency Ney Sakal, Deputy Director General of the TR (representing Director General Sok Dara) , and the leadership of Lion Trust (Singapore) Limited. Given the Trust Regulator's (TR) active promotion of these services, the ongoing collaboration with specialized institutions like Banjaran AMC holds substantial promise for elevating the sophistication of Cambodia's broader financial sector.
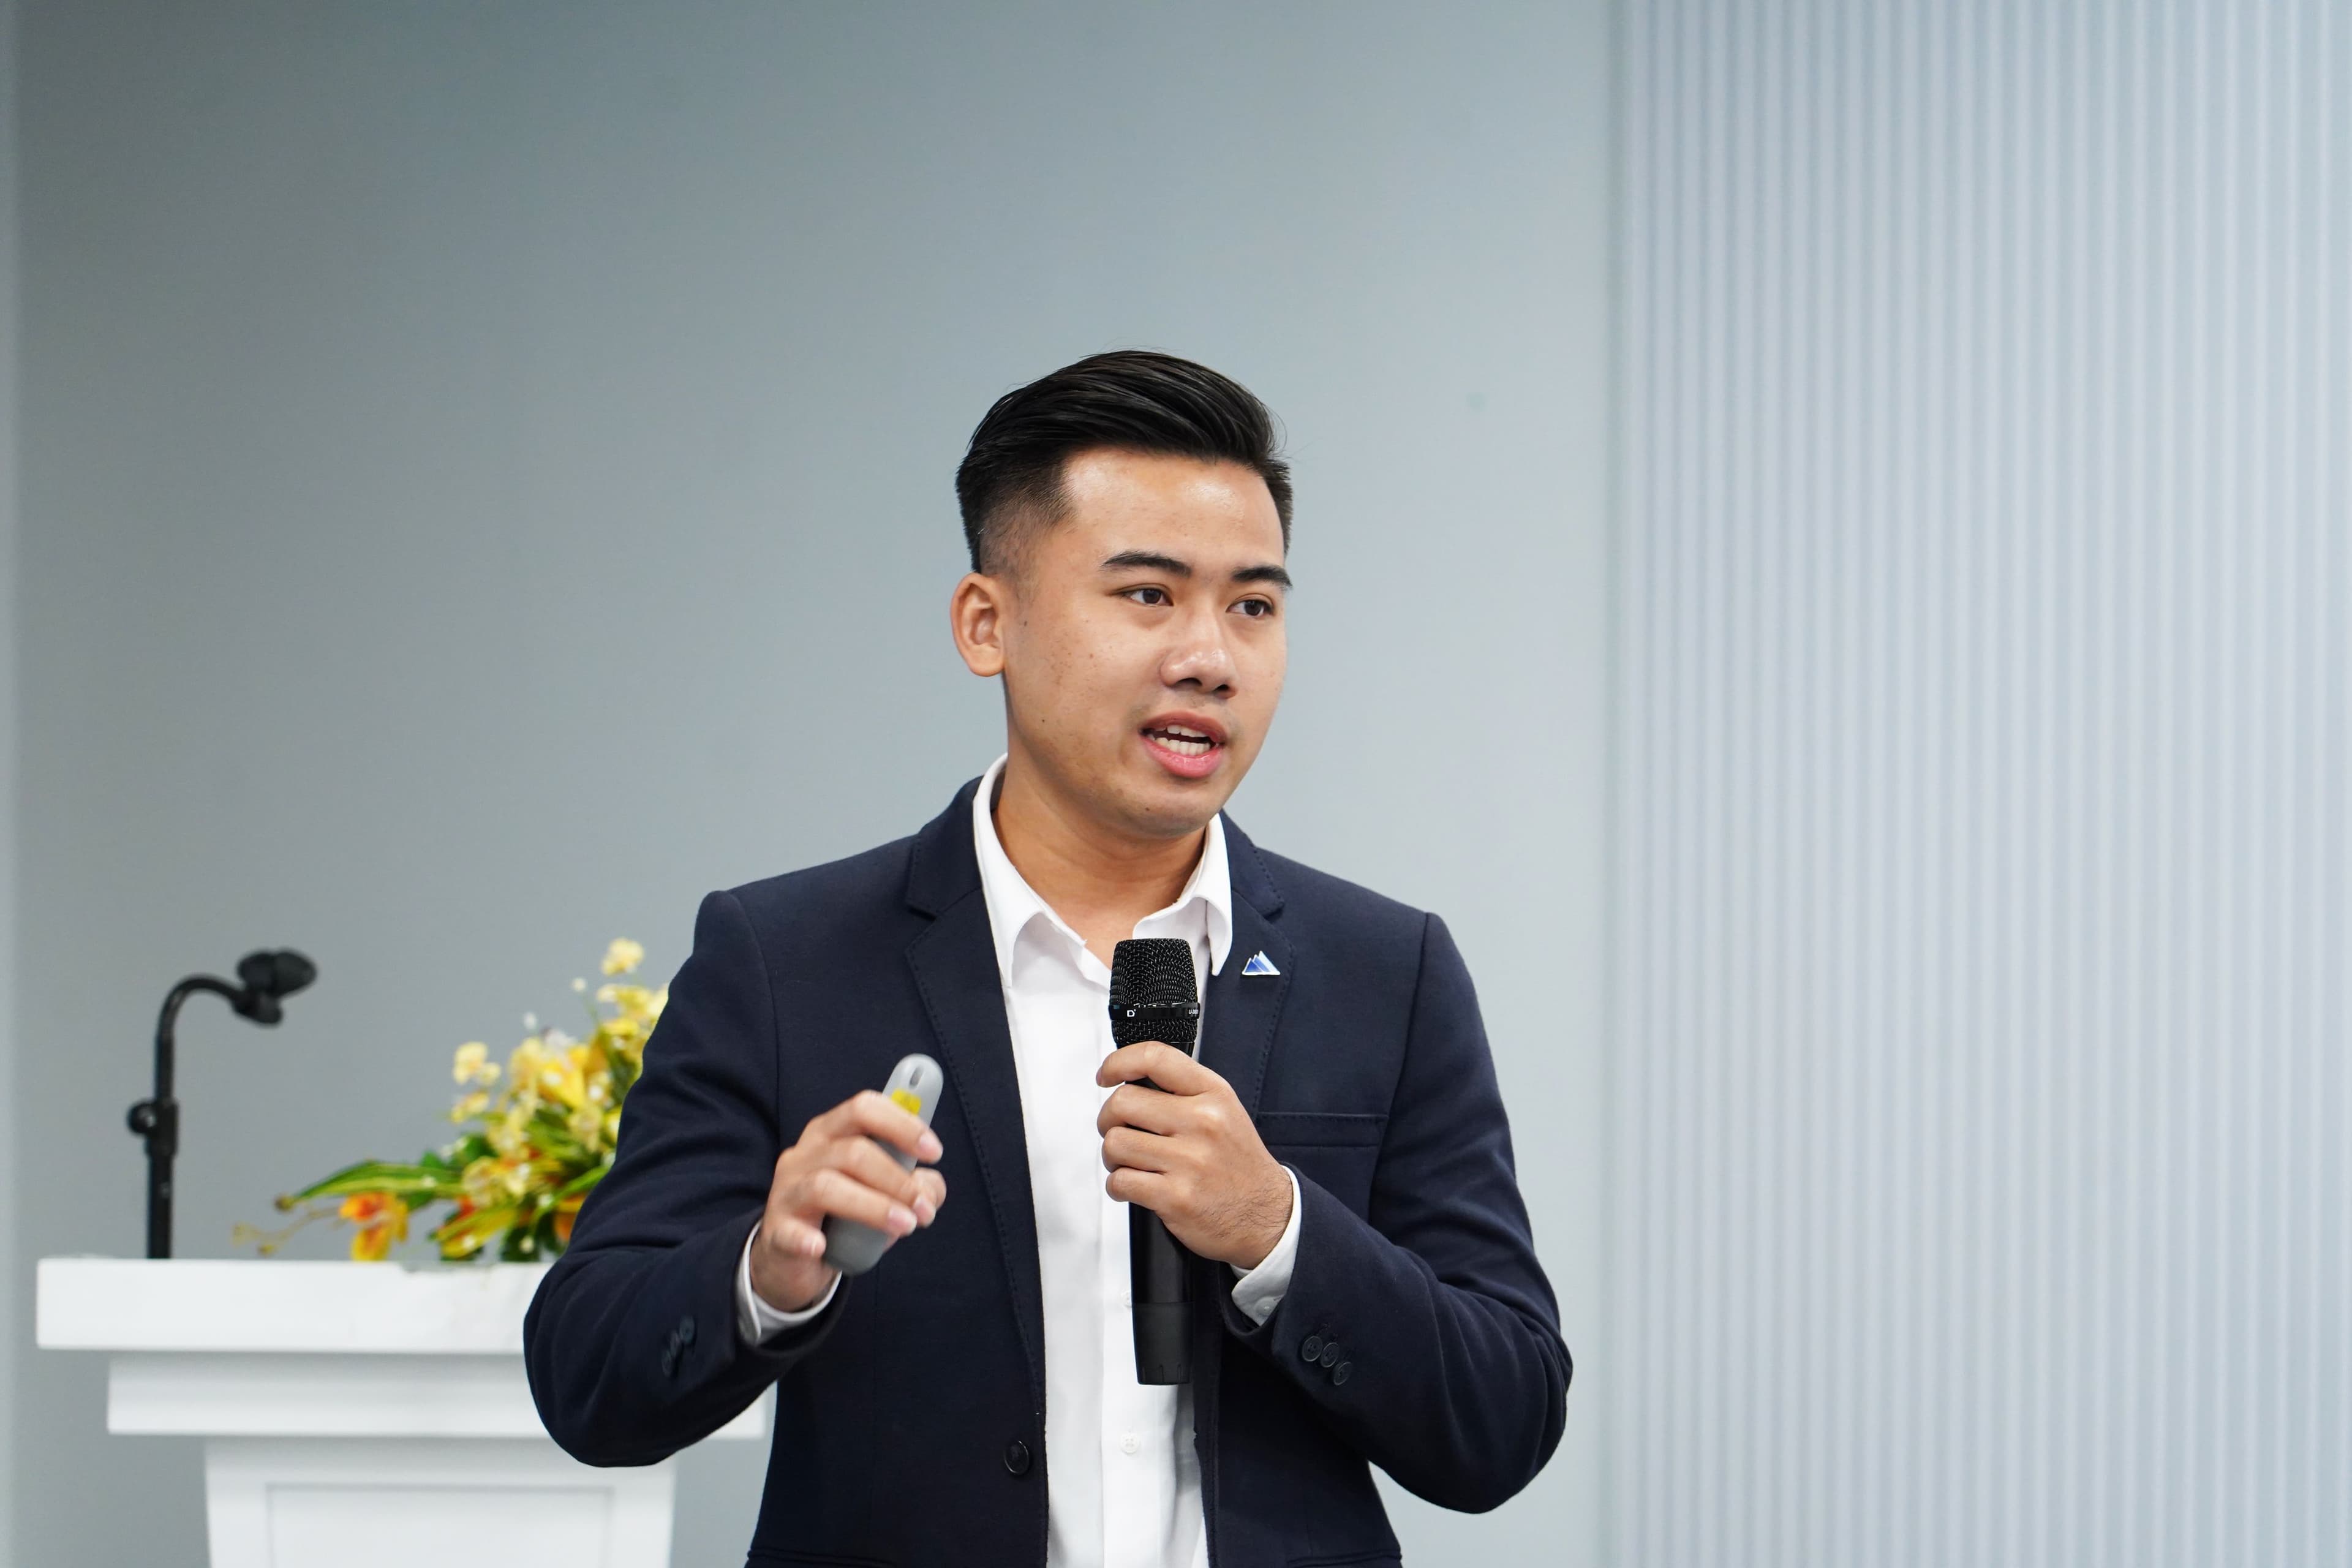
Banjaran Asset Management Shares Insights on Risk Management in CIS at SERC’s 29th Training
Banjaran Asset Management Highlights Risk Management in CIS at SERC’s 29th Securities Sector Training On the morning of April 28, 2025, Mr. Veasna Monireach, Operation Department Representative of Banjaran Asset Management (Cambodia) Plc., delivered an insightful presentation on Risk Management in Collective Investment Schemes (CIS) during the 29th Training, Examination, and Continuing Professional Education event. The event was organized by the Securities and Exchange Regulator of Cambodia (SERC) and held at the Business Development Center. Mr. Monireach’s presentation emphasized the importance of robust risk management practices within CIS operations to ensure investor protection, regulatory compliance, and sustainable fund performance. Through real-world examples and best practices, he highlighted Banjaran's commitment to strengthening Cambodia’s investment fund industry and promoting professional excellence in the securities sector. This engagement underscores Banjaran’s ongoing contribution to the growth, education, and innovation of Cambodia’s financial markets.
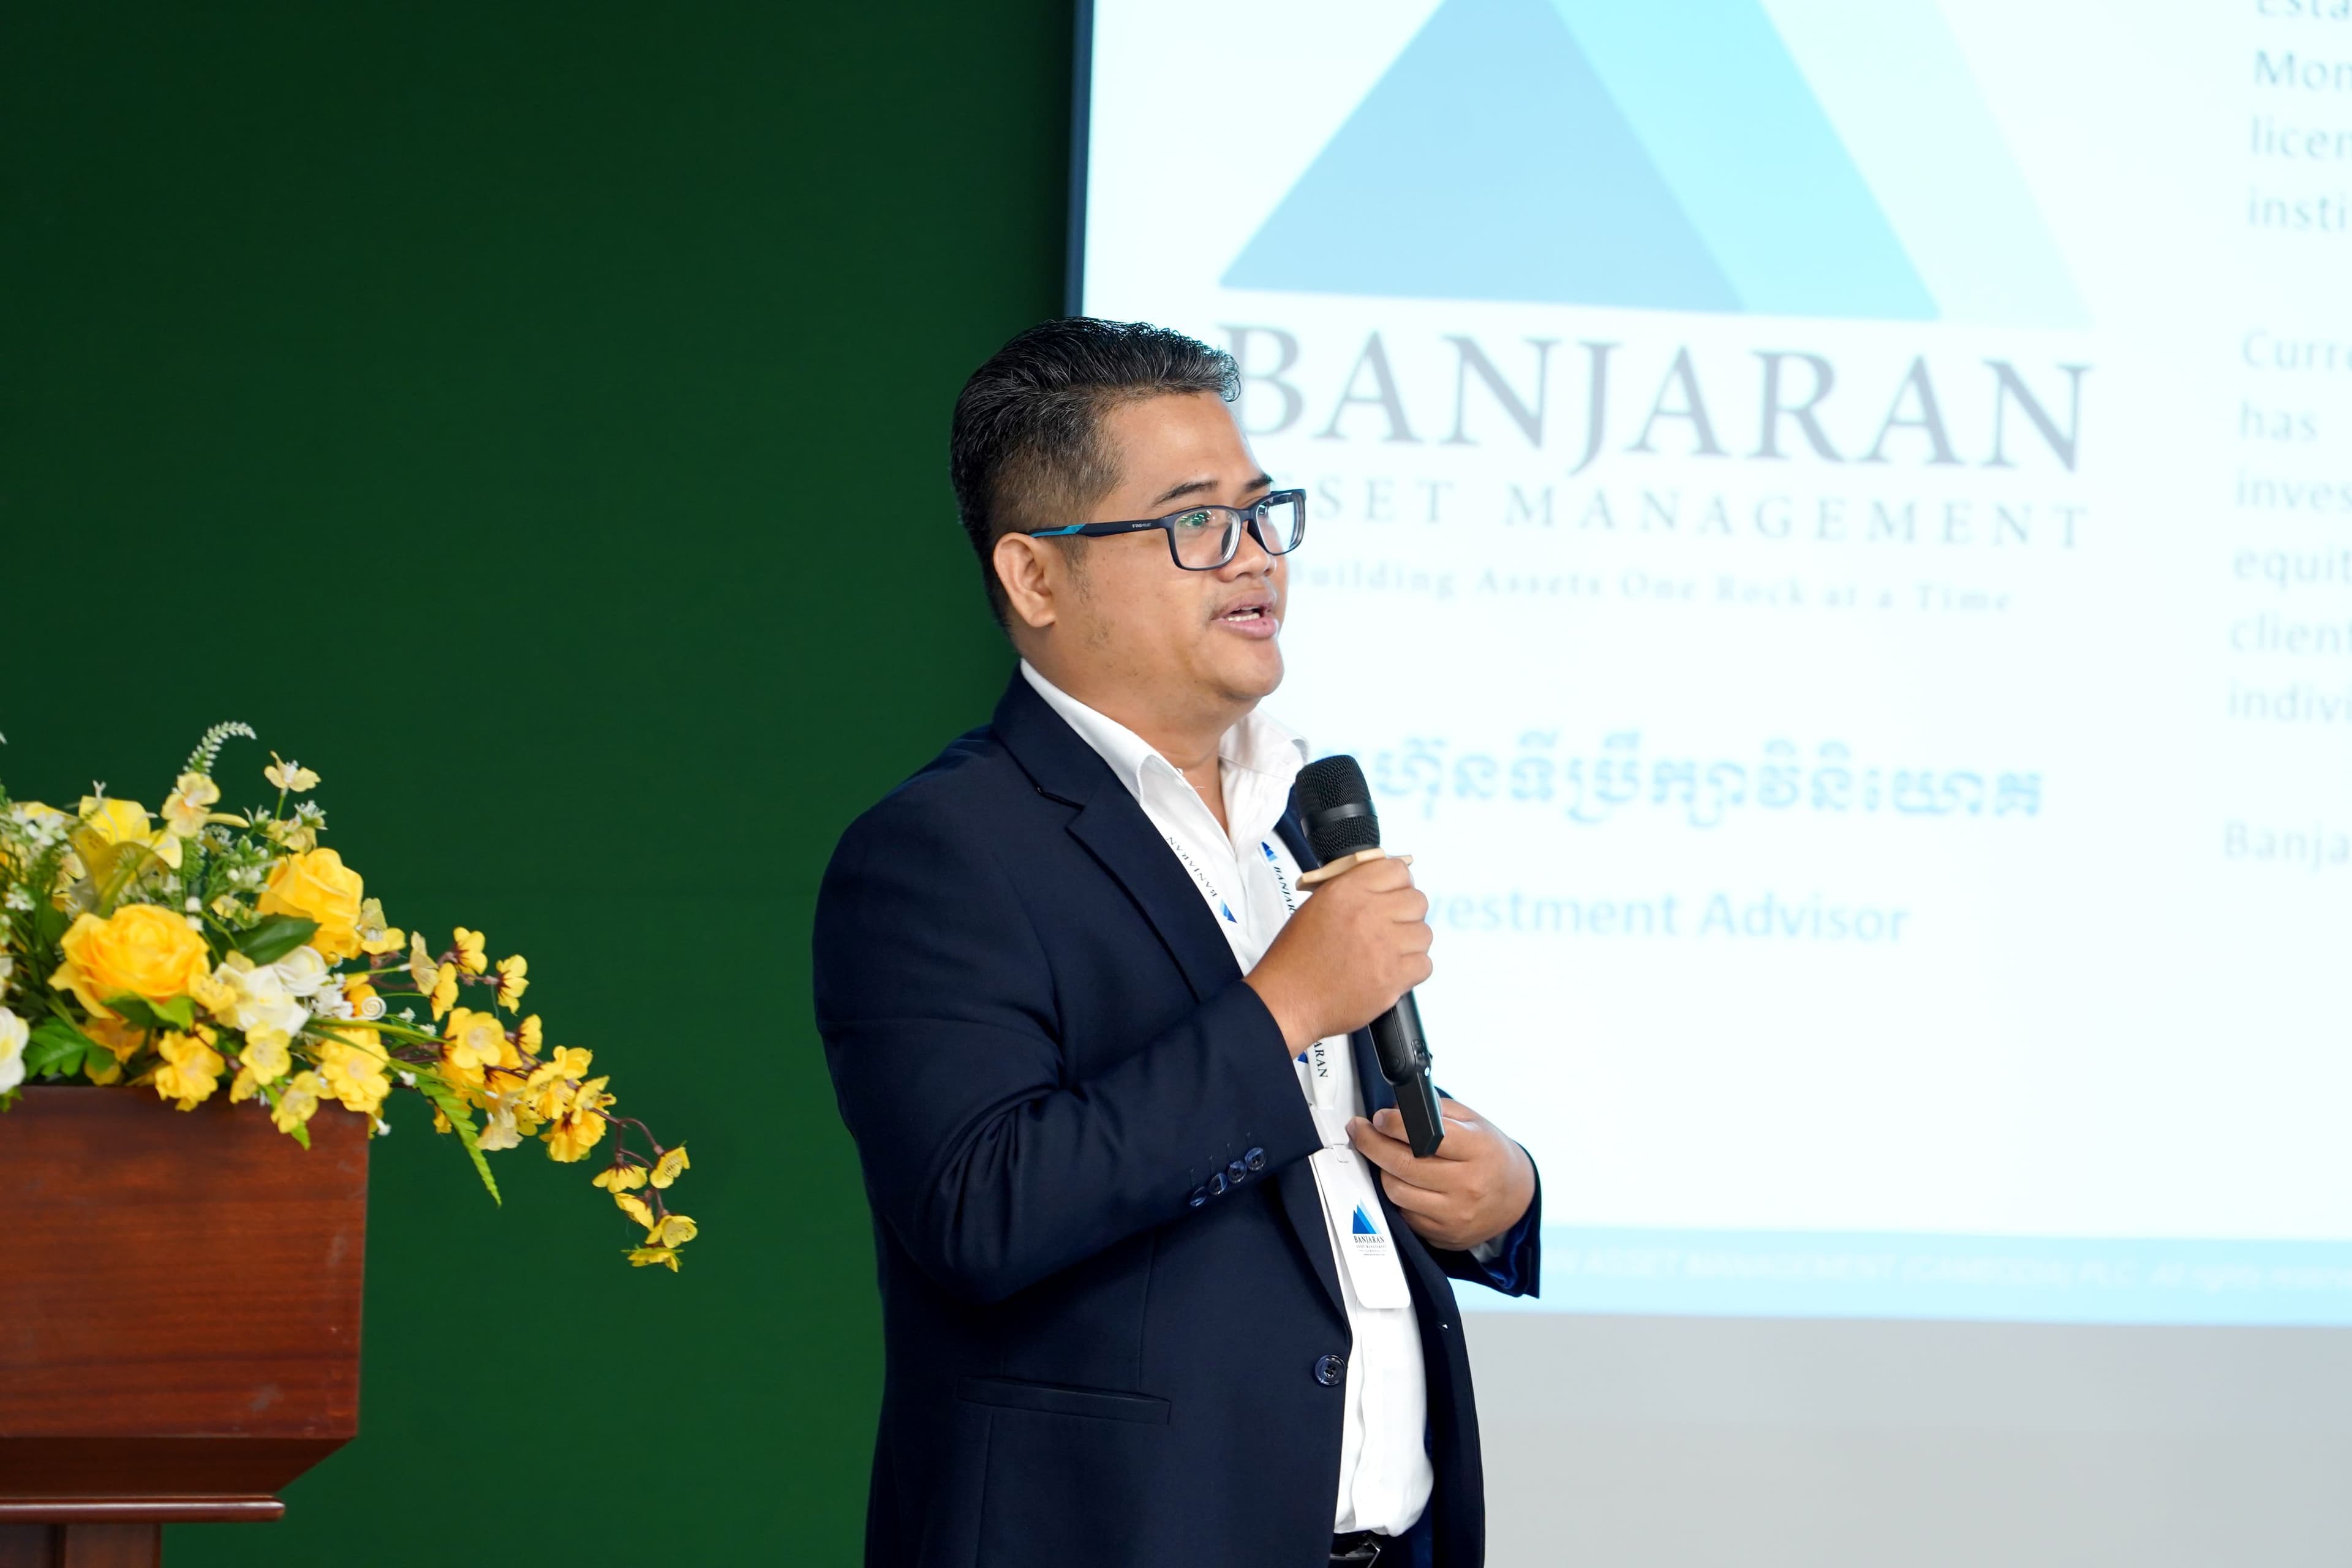
Experience Sharing on Cambodia’s First CIS Fund at SERC’s 29th Securities Sector Training
Banjaran Asset Management Shares Experience on Cambodia’s First Collective Investment Scheme Fund at SERC Event On the morning of April 25, 2025, Mr. Nhem Sopaul, Corporate Manager of Banjaran Asset Management (Cambodia) Plc., delivered a keynote presentation during the 29th Training, Examination, and Continuing Professional Education event organized by the Securities and Exchange Regulator of Cambodia (SERC). The event was held at the Business Development Center, bringing together professionals across Cambodia’s securities sector. Mr. Sopaul shared valuable insights on the Experience of Issuing the First Collective Investment Scheme (CIS) Fund in Cambodia, along with an overview of asset management and fund operations. His presentation highlighted Banjaran’s role as a pioneer in the local fund management space and its commitment to supporting the development of Cambodia’s capital markets through innovation, transparency, and investor education. The event marked another significant milestone in fostering professional excellence and knowledge-sharing in the financial sector, further reinforcing Banjaran’s position as a leader in the Cambodian investment landscape.
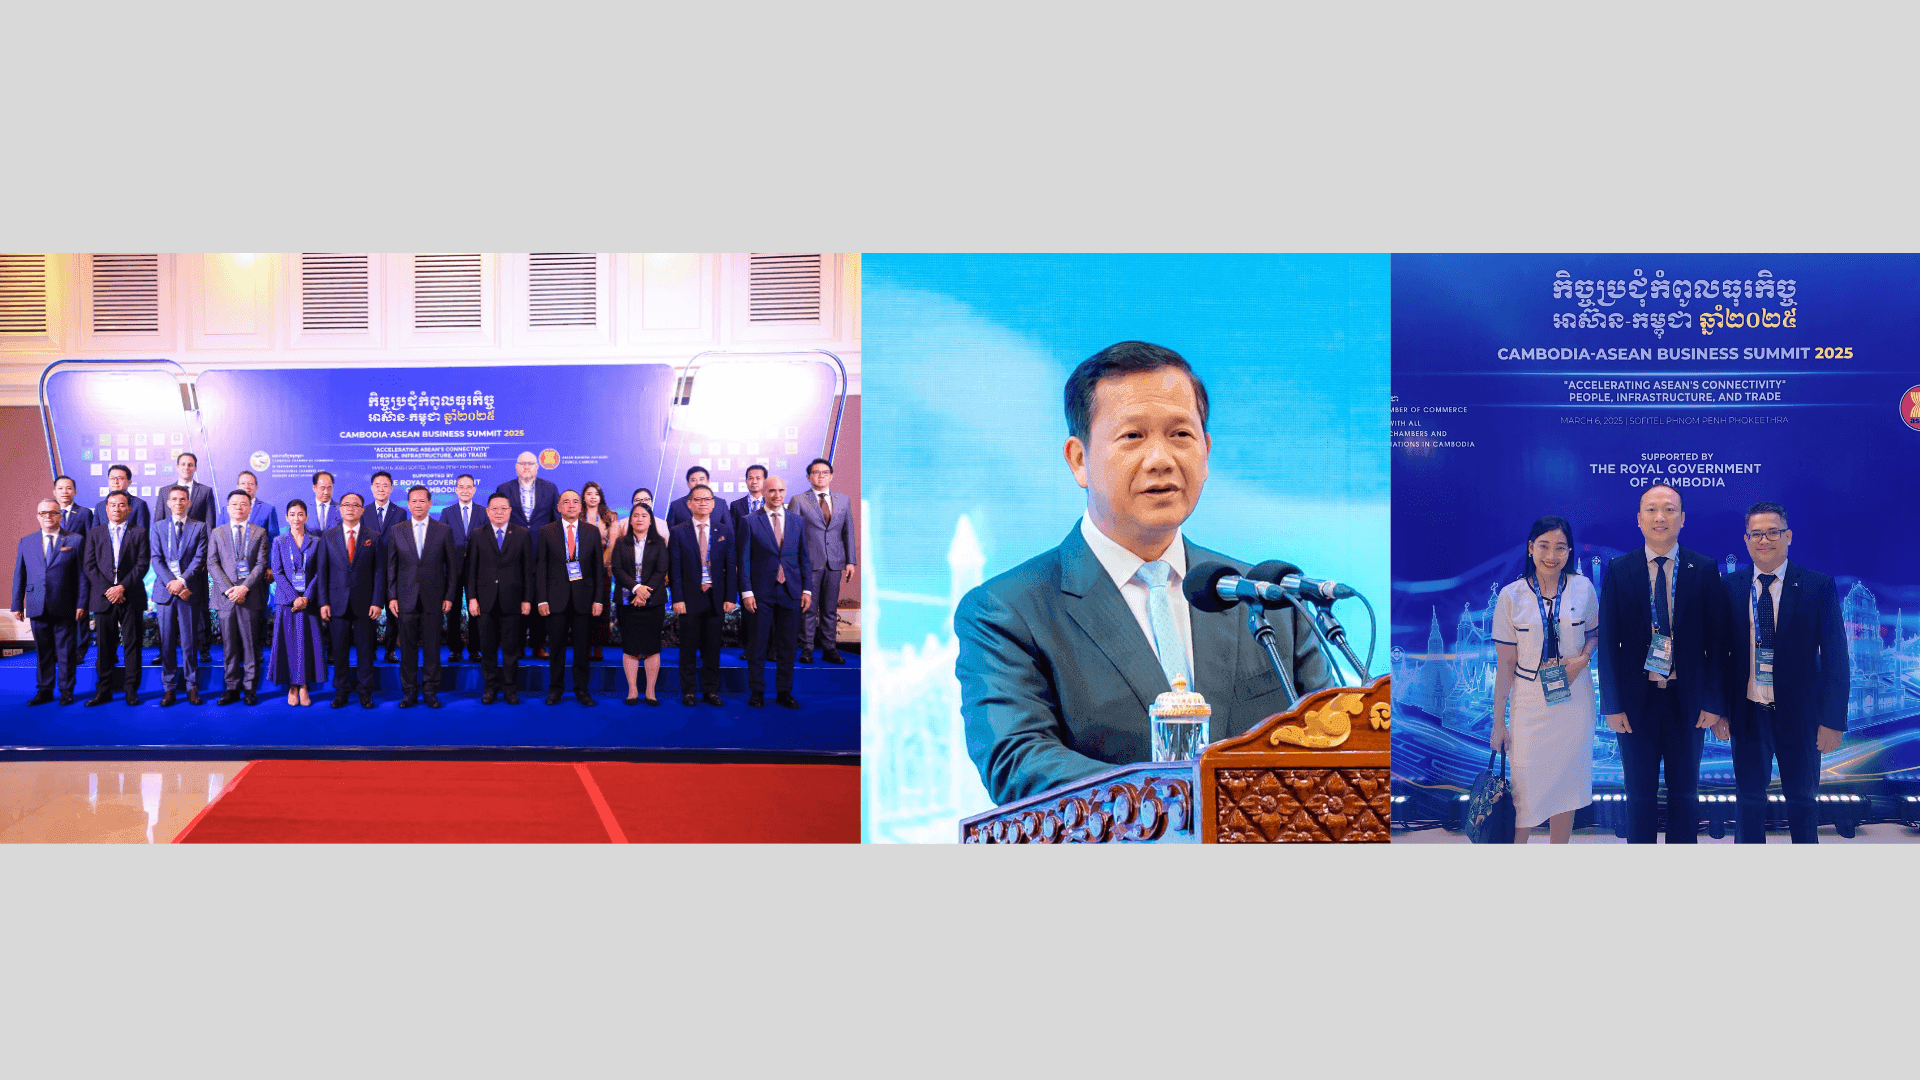
Banjaran Asset Management (Cambodia) Plc. at the Cambodia-ASEAN Business Summit 2025
The Cambodian ASEAN Business Summit 2025: “Accelerating ASEAN’s Connectivity” People, Infrastructure, and Trade The Cambodia ASEAN Business Summit 2025 served as a dynamic platform to foster economic cooperation and development within the ASEAN region, specifically showcasing Cambodia's growing role in regional economic integration. Held at Sofitel Phnom Penh Phokeethra on March 6th, 2025, the summit brought together government officials, business leaders, and experts under the theme "Accelerating ASEAN's Economic Integration." This summit underscored Cambodia's dedication to sustainable and inclusive growth, as outlined in the Royal Government of Cambodia’s policy, while aligning with ASEAN’s overarching economic objectives. The event targeted CEOs, senior executives, entrepreneurs, investors, policymakers, and thought leaders from across ASEAN, representing diverse industries and sectors. It was with great honor that the summit was presided over by Samdech Moha Borvor Thipadei Hun Manet, Prime Minister of the Kingdom of Cambodia. Attendees heard directly from the Prime Minister about the Royal Government’s commitment to supporting ASEAN businesses and fostering shared prosperity. Beyond insightful discussions, the summit provided ample opportunities for networking and collaboration. A networking lunch, accompanied by the Cambodia Investment Showcase, allowed participants to connect with business leaders and explore investment opportunities in key sectors. Additionally, the Business Matching sessions facilitated pre-arranged B2B meetings, fostering potential partnerships and collaborations. The Closing Ceremony summarized key takeaways and issued a call to action for continued collaboration and investment in ASEAN, concluding with a networking reception where attendees further built relationships. The Cambodia ASEAN Business Summit 2025 was a pivotal event, attracting a diverse audience and contributing significantly to accelerating economic growth, strengthening regional integration, and promoting sustainable development in Cambodia and the ASEAN region. The Program of Cambodia ASEAN Business Summit 2025: * Keynote Speeches by H.E. Keo Rottanak, Minister of Mines and Energy Panel Discussion 1: Building ASEAN's Future: Infrastructure Development and Regional Connectivity This panel explored the vital role of infrastructure development in driving economic growth and regional integration within ASEAN. The discussion delved into the importance of physical infrastructure, digital connectivity, and the ASEAN Energy Grid (AEG), focusing on how these elements contribute to a more integrated and prosperous region. Panel Discussion 2: Driving Prosperity Through Trade and Investment This panel examined how ASEAN leveraged trade and investment to drive economic growth and development across the region. Key strategies, initiatives, and partnerships that shaped ASEAN's economic landscape were explored. Panelists: - H.E. Sun Chanthol, Deputy Prime Minister, First Vice-Chairman of the Council for the Development of Cambodia. - H.E. Cham Nimul, Minister of Commerce, Cambodia. - H.E. Kong Vibol, Minister attached to the Prime Minister, Director General of the General Department of Taxation, Cambodia. - Mr. Chan Sopheap, Deputy Director General, General Department of Customs and Excise, Cambodia. - H.E. Sou Socheat, Director General of the Securities and Exchange Regulator of Cambodia. Panel Discussion 3: Human Capital: Key to Trade and Infrastructure Development This panel discussed the critical role of human capital in driving trade and infrastructure development across ASEAN. Prominent voices from ASEAN member states explored how investing in human capital could unlock the region's economic potential. Panelists: - H.E. Heng Suor, Minister of Labor and Vocational Training, Cambodia. - H.E. Hem Vanndy, Minister of Industry, Science, Technology and Innovation (MISTI), Cambodia. - Mr. Parson Lam, Director of Hong Kong Economic and Trade Office in Bangkok, Government of Hong Kong Special Administrative Region. - Mr. Sheanghai Lao, Division Chief Human Resources Officer, Wing Bank (Cambodia) Plc. Moderated by: Mr. Casey Barnett, President of the American Chamber of Commerce in Cambodia (AmCham) Pictures credited to ASSOCIATION OF SOUTHEAST ASIAN NATIONS
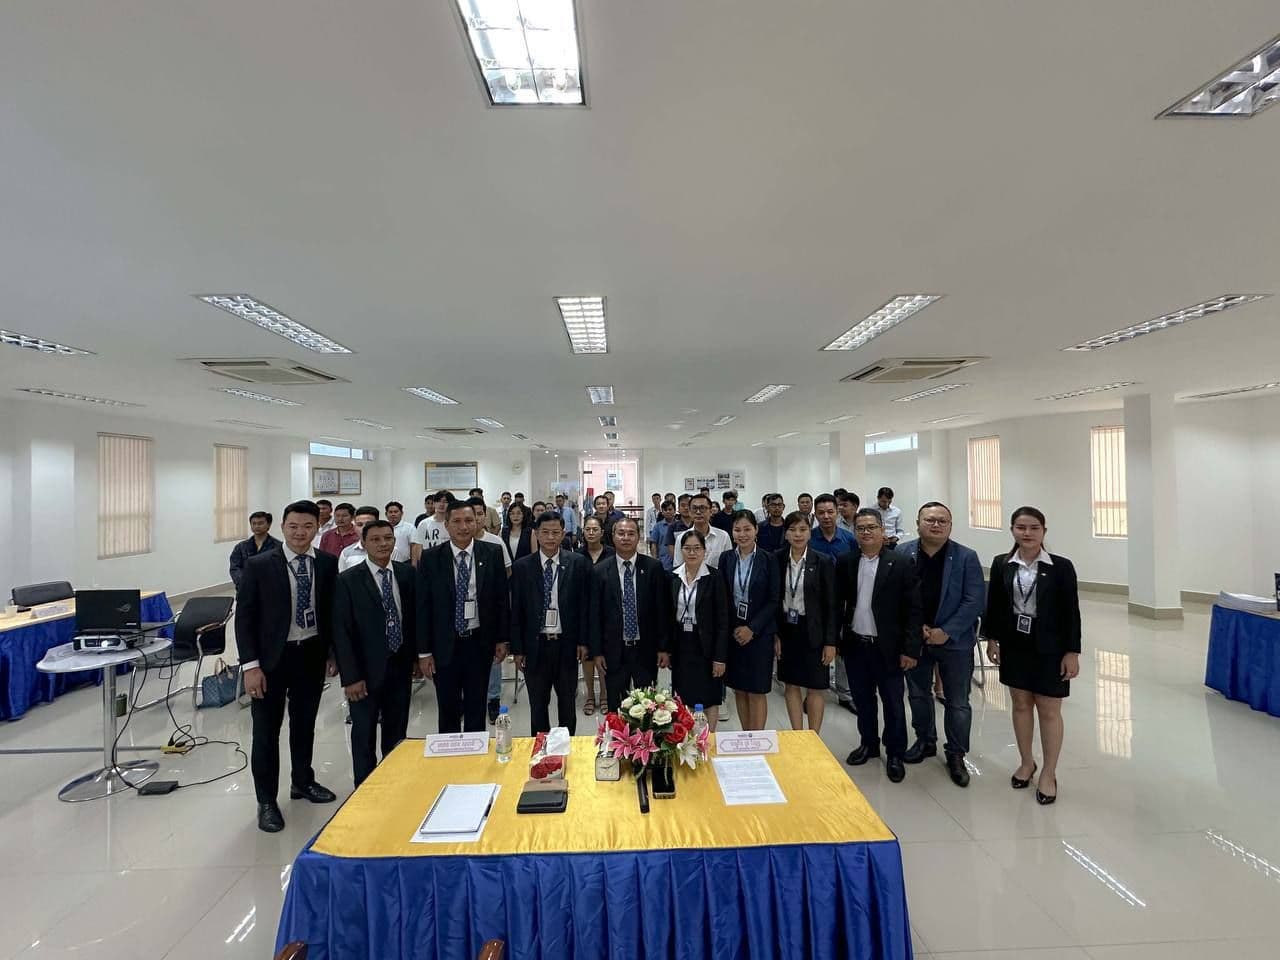
Roadshow Reflections: Insights and Innovations Unveiled
On the morning of December 7, 2024, Banjaran Asset Management (Cambodia) Plc. partnered with ACLEDA Bank Plc., Chamkar Doung Branch, to host the landmark event titled "Cambodia’s First Fund Subscription Roadshow." This pioneering initiative aimed to introduce local investors to the "BAMC Asia Equity Fund (BAEF)," showcasing its potential as a catalyst for capital growth and economic development in Cambodia. The roadshow featured an engaging presentation that outlined the strategic objectives of the "BAMC Asia Equity Fund", emphasizing its focus on high-growth sectors within the region. Attendees were given insights into the fund's investment philosophy, risk management strategies, and expected returns, all tailored to the unique opportunities present in the Cambodian market. Throughout the event, participants had the chance to engage in meaningful discussions with industry experts and gain firsthand knowledge about emerging trends and investment strategies. The roadshow not only highlighted the fund's potential to drive significant economic growth but also reinforced the importance of collaboration between financial institutions and asset management firms in fostering a robust investment landscape in Cambodia. In conclusion, the event served as a pivotal moment for local investors, providing them with valuable resources and insights to navigate the evolving financial market, while highlighting the BAMC Asia Equity Fund's crucial role in driving Cambodia's economic growth, signaling that this is just the beginning, with more exciting opportunities to come.
Cambodia's First Fund Subscription Roadshow
On morning, 23rd November 2024, Banjaran Asset Management (Cambodia) PLC. has participated in "Cambodia's First Fund Subscription Roadshow" hosted by Acleda Securities Plc. Through engaging presentations and topic about BAMC Asia Equity Fund (BAEF), we were able to connect and promote the CIS fund to a wide range of participants, marking another significant milestone in Cambodia’s financial market growth.A heartfelt thank you to the organizers and attendees for making this event a success.
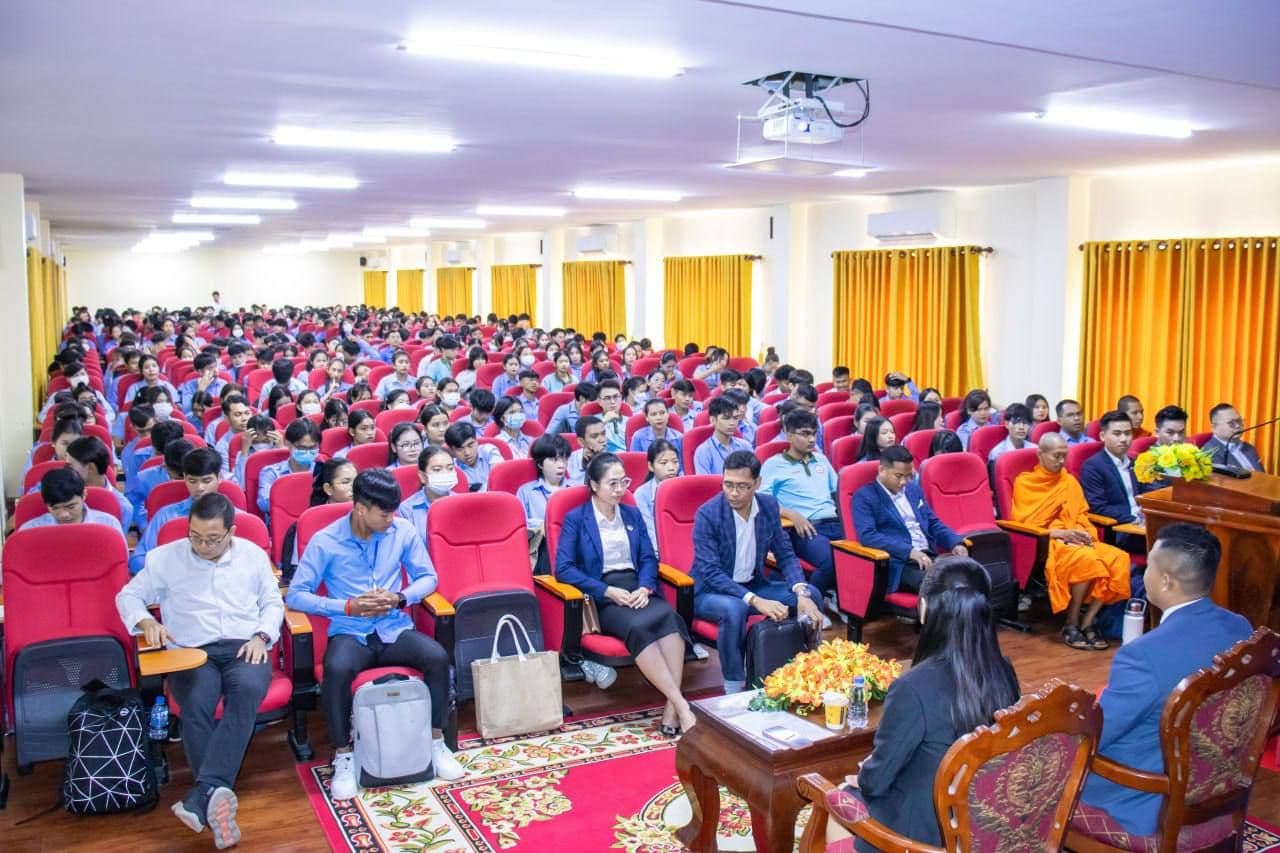
Empowering Future Investors: Banjaran Asset Management's Insightful Collective Investment Scheme (CIS) Fund
On the morning of October 30, 2024, Mr. Sok Chantola, Sales & Marketing Executive of Banjaran Asset Management (Cambodia) Plc., conducted a presentation on the Collective Investment Scheme (CIS) Fund at Preah Sihanouk Raja Buddhist University as part of the “Smart Investing” training program, organized by ACLEDA Securities Plc. The session aimed to deepen attendees’ understanding of CIS investment strategies.
Seminar on Professional Ethics in Collective Investment Schemes with SERC
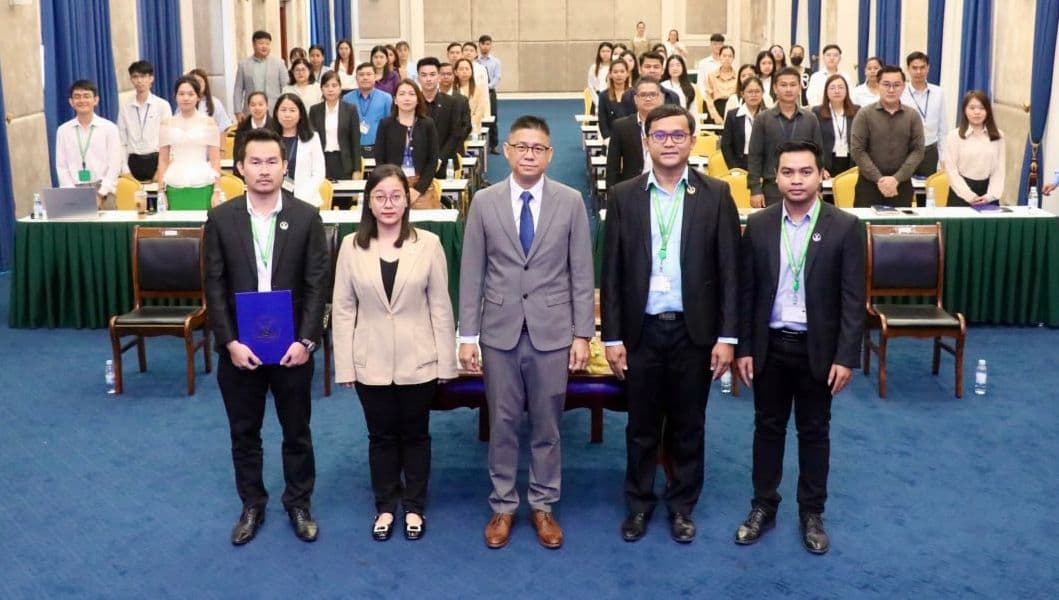
On the morning of Wednesday, corresponding to October 23rd 2024, the Securities and Exchange Regulator of Cambodia (SERC) organized a seminar to promote “Professional Ethics in Collective Investment Schemes” . This seminar was held for fund management companies, custodians, distributors, and trustees, at the building of the Non-Bank Financial Services Authority. The event was presided over by His Excellency Dr. Vin Pakdey , Deputy Director-General of SERC, representing His Excellency Sou Socheat , the Government Delegate in charge as Director-General of SERC. The seminar was designed to provide an opportunity for fund management companies and related businesses to understand the importance of professional ethics, transparency, and responsibility in the collective investment scheme business. It also aimed to ensure that these entities adhere to high standards in their operations, enhancing investor confidence in the financial market. The gathering covered important topics on how ethical practices contribute to sustainable business growth and regulatory compliance, reinforcing the importance of good governance in the financial sector. More Securities and Exchange Regulator of Cambodia
Market Outlook
2024 February, Market Outlook: Navigating Central Bank Strategies and Growth Opportunities in Asia
As we step into 2024, initial hopes for early interest rate cuts by the US Federal Reserve (FED) and the European Central Bank (ECB) are fading. Both central banks have downplayed the likelihood of reducing rates anytime soon, largely due to strong economic data released in recent months. The US economy continues to display resilience, with sustained expansion indicating that the FED must tread carefully. Lowering interest rates too soon could risk reigniting inflation, which the central bank is keen to avoid. At the same time, there are pockets of weakening growth within the economy, signaling the potential for a broader slowdown. This delicate balancing act places the FED in a challenging position, where policy mistakes could have significant consequences for both the US economy and global financial markets. In line with our earlier expectations, the Eurozone also faces similar inflationary pressures, with energy prices remaining persistently high. As a result, inflation remains sticky, preventing the ECB from easing rates. We foresee that both central banks will need to remain vigilant in navigating the complex dynamics of their respective economies, weighing inflation risks against the threat of economic slowdowns. Meanwhile, China's approach to monetary policy has taken a markedly different turn. The Chinese government recently lowered the 5-year loan prime rate by 25 basis points to 3.95%, signaling its determination to stimulate the economy and support the real estate sector. Under the “whitelist” initiative, commercial banks are encouraged to provide lending to property projects approved by local governments. These rapid, proactive measures underscore the government's commitment to front-loading stimulus to prevent weak sentiment in the housing market from deepening. We believe these policies will continue to evolve progressively, ensuring that the real estate sector stabilizes and recovers on a sustainable path. Signs of improvement are already emerging in China’s economy. Recent data on monetary aggregates indicate positive movement, and domestic travel and spending during the Lunar New Year suggest a rebound in consumer activity. On the global stage, China’s exports have grown for the second consecutive month in December 2023, further reinforcing the positive outlook for 2024. These rapid policy moves come as the State Council calls for "forceful measures" to restore confidence in both the economy and financial markets. Japan is also showing signs of strength, with the economy benefiting from long-anticipated corporate reforms. After decades of deflation, Japan appears to be breaking free from this prolonged economic phase. Reforms aimed at improving corporate profit margins and shareholder returns are finally coming to fruition, marking the end of the country's 30-year deflationary struggle. We believe these developments will unlock significant value for shareholders, creating opportunities for growth in the Japanese market. In summary, we remain optimistic about the prospects for the Asian markets, particularly as China and Japan implement aggressive economic measures. Conversely, we approach the US markets with caution, given the headwinds presented by inflationary pressures and an overconcentration in the technology sector. As we move forward, the balancing act between growth, inflation, and central bank policy will continue to shape the global market landscape, with Asia emerging as a bright spot for investors in 2024.
2024 January, Market Outlook - Navigating 2024 Amid Geopolitical Tensions and Economic Shifts
As we enter 2024, the global financial landscape is expected to shift focus from rising bond yields to interest rate stabilization and potential easing, particularly by the US Federal Reserve. After three years of tightening policies, we anticipate that both the US and Europe will experience sharply slower economic activity and increased unemployment. Europe, in particular, faces heightened risks of a prolonged recession. While interest rates in the US may hold steady for now, primarily due to persistent inflation pressures in areas like housing, rising geopolitical risks, such as recent airstrikes by the US and UK in response to Houthi rebel attacks, could lead to disruptions in global trade and shipping costs. Geopolitical Tensions: The US-China Factor Geopolitical developments, especially the enduring US-China tension, will be a critical driver in assessing global economic and financial market performances. The ongoing decoupling between the two economic giants, particularly in the semiconductor industry, presents both challenges and investment opportunities. We foresee increased innovation stemming from this geopolitical divide, providing promising prospects in certain sectors. The AI Revolution: A Long-Term Investment Opportunity The advent of generative artificial intelligence (AI), epitomized by innovations like ChatGPT, has sparked widespread interest in AI-driven technologies across industries. While the global addressable market for AI is still being estimated, we remain optimistic about its long-term growth potential. AI companies in our portfolio have already shown promise, and we continue to explore new investment opportunities in this space as AI applications expand. China's Economic Recovery: Stabilization Efforts China's economic recovery is gaining momentum, though the real estate sector remains a drag. However, recent fiscal and monetary policies have helped stabilize the situation. The Central Economic Work Conference's call for proactive fiscal expansion and real estate policy adjustments are positive signs for the market. China's central bank has also introduced liquidity-boosting measures, such as a 50 basis point reduction in the reserve requirement ratio and lower rates for loans to small firms. We believe these are incremental steps toward further stabilization, and we are optimistic about China's economic and market outlook in 2024. US Presidential Election: Market Implications This year’s US Presidential Election will undoubtedly shape economic policies and market directions, though we refrain from speculating on political outcomes. Instead, our focus remains on the data-driven economic and market trends, with a view that the US economy will increasingly look inward as the election approaches. Overall, we believe Asia, particularly China, remains a bright spot in the global economy, while the US and Europe may face slower growth and recessionary pressures. We remain vigilant in assessing geopolitical risks and continue to focus on sectors like AI and innovation, which offer long-term growth opportunities.
2023 December, Market Outlook: Asia Emerges as a Bright Spot Amid Global Economic Shifts
As 2023 draws to a close, the equity market has remained largely stable, with investors maintaining a preference for developed markets. While Asia Pacific markets have also posted positive returns, their performance still trails behind other regions despite notable improvements in economic data. This disparity is likely due to end-of-year dynamics such as tax-loss harvesting and institutional portfolio adjustments, or "window dressing," a common phenomenon seen during this period. Historically, such short-term volatility tends to carry over into January as fund managers rebalance their portfolios for year-end reporting. In developed markets, equity markets have experienced significant optimism since the Federal Reserve opted to hold interest rates steady for two consecutive meetings. This move has signaled to investors that the Fed's interest rate hike cycle may have peaked, fueling market euphoria. Additionally, concerns about a looming US recession have eased, with many economists now revising their forecasts toward a "soft landing" scenario, where economic activity slows but avoids a severe downturn. However, inflation in the US remains persistently above the Fed's 2% target, indicating that interest rates may stay elevated for an extended period. The future economic outlook remains uncertain, especially as housing inflation cools, but we believe that while the risk of a recession is still moderately high, it is unlikely to escalate into a systemic crisis. On the geopolitical front, China’s recent diplomatic overtures toward the US have been a positive development. Following Chinese President Xi Jinping's visit to the US last month, both nations have expressed a renewed commitment to peaceful cooperation. The resumption of military dialogue, after months of silence, signals China's intention to restore political ties with the US. Additionally, President Xi’s meeting with top US business leaders highlighted strong corporate support for continued engagement with China, despite ongoing geopolitical tensions. For instance, Mastercard's new joint venture with China's national transaction processor, NetsUnion Clearing, demonstrates the long-term business potential between the two countries, allowing Mastercard cardholders to enjoy seamless payments in China. Nevertheless, while these diplomatic efforts are encouraging, further reciprocal actions from the US government will be crucial to reducing geopolitical risks in the long term. With the US presidential elections on the horizon in late 2024, we expect China to remain a central theme in American political discourse, with both parties likely positioning the country as a major national security threat to garner electoral support. This political climate may perpetuate tensions, and as a result, we anticipate that geopolitical risks will remain elevated through 2024. Looking beyond the US, other significant elections, such as Taiwan's, will also play a key role in shaping geopolitical dynamics. As global security concerns intensify, we foresee a gradual restructuring of global supply chains, with capital and business operations increasingly shifting to countries deemed safer or more politically stable. This trend toward economic fragmentation will favor companies capable of maintaining market share and operational efficiency amid the reshoring of industries. In China, the recent Central Economic Work Conference concluded with the government setting a clear pro-growth agenda for 2024. Chinese policymakers are focusing on reviving confidence and stimulating economic growth through a series of supportive measures, including monetary, fiscal, and administrative interventions. These initiatives have been ramping up in intensity, and we anticipate additional measures in the coming months, particularly aimed at addressing risks in the real estate sector. Given these developments, we continue to see Asia, particularly China, as a bright spot for economic growth in the global economy. A lower interest rate environment, coupled with increased liquidity, should help alleviate financial pressures and reduce the debt burdens of companies and individuals. As the world economy navigates through geopolitical tensions and inflationary pressures, Asia remains well-positioned to drive global growth in the near term, making it a focal point for investors looking to capitalize on emerging market opportunities. In summary, while global economic conditions remain uncertain, Asia’s resilience, supported by pro-growth policies and improving economic indicators, offers a compelling investment case, even as geopolitical risks loom on the horizon.
2023 November, Market Outlook: Resilience, Stimulus, and Global Shifts
As we look ahead, the global market outlook remains shaped by several key developments. Despite geopolitical tensions and ongoing conflicts, such as the humanitarian crisis between Israel and Hamas, we expect limited broader economic impact due to stabilizing military presence and containment measures. The risk of a wider regional conflict appears low, preserving global market stability for the time being. US Economic Resilience and Slowdown Expectations In the US, resilience continues to be a dominant theme. While the Federal Reserve’s tightening measures have been in place since 2022, the financial system remains robust, supported by the aftereffects of COVID-19 stimulus and substantial fiscal spending by the US government. This liquidity, however, is expected to taper, with a corresponding economic slowdown projected over the medium term. Current forecasts suggest GDP growth of 0.7% in Q4 2023 and 0.3% in Q1 2024, indicating a likely deceleration in the coming quarters. China’s Recovery Gains Momentum China’s economy has begun to gain notable momentum, driven by improving retail sales, imports, and industrial output. The government has recently announced a significant RMB 1 trillion stimulus package to further bolster the recovery. However, investor sentiment remains cautious, keeping valuations suppressed relative to the US. We believe that this discrepancy is unsustainable and anticipate that over the medium term, valuations in China will close the gap, driven by stronger economic fundamentals. Japan’s Stimulus and Growth Prospects Japan is emerging as an intriguing opportunity as it moves away from years of deflation, with inflation now supported by demand. In response to weakening economic data, the Japanese government has introduced a US$ 110 billion stimulus package aimed at boosting private consumption. This should translate into economic growth in the near-to-medium term, further enhancing Japan’s market potential. Focus on Asia Amid Geopolitical Stability Asia remains our primary focus, especially in light of recent positive developments in China’s economic data and a decrease in US-China geopolitical tensions following the Biden-Xi meeting in San Francisco. Agreements between both countries signal a more stable relationship, reducing trade war fears and enhancing the region’s investment appeal. Overall, we maintain a cautiously optimistic view, focusing on opportunities in Asia while monitoring the evolving macroeconomic landscape.
2023 October, Market Outlook - Navigating China's Property Challenges, US Consumer Trends, and Asia's Resilient Growth Prospects
After a month since China relaxed its housing restrictions, overall home sales continued to be weak as consumer confidence has yet to be restored meaningfully. We believe that homebuyers in China will remain hesitant until the industry can contain the liquidity issues faced by property developers. This is a challenging issue to tackle as continued low sales will further worsen the developer’s cashflow position, which in turn will affect consumer confidence. The administration will likely arrest this situation by issuing liquidity for developers to complete their projects. Through government actions, we believe that they can bring the housing situation under control. Aside from the ongoing geopolitical tension between China and the US, we see the property crisis as the last hurdle for an overall recovery, given the broader improving economic data and earnings resilience from the leading firms that we cover. We are also encouraged by the Chinese government's continuous support for the economy through increased spending, hence a bigger budget deficit and more domestic investments. We are beginning to see early signs of the Chinese economy stabilizing. In early September, Huawei surprised the world by launching their Mate 60 Pro smartphone which carried a 7nm processor. Previously, the speculated limit for the Mate 60’s mass production using China’s existing technology was at 14nm. It is a clear win that China has produced this breakthrough internally despite continued semiconductor sanctions from the US. However, it remains to be seen whether China can mass produce such chips across multiple applications and further develop smaller nodes without access to cutting-edge machines. With the current geopolitical landscape, we maintain our view that the US-China rivalry will continue and possibly intensify over the long term. Retail sales in the US surprised in September, growing 3.7% yoy. This came at the cost of lower consumer savings, dropping to levels not seen since before the global financial crisis. We attribute the sudden economic pick-up to be due to pent-up demand over the summer holidays. Thus, we think that the current consumption growth is unsustainable over the long term. We have also been monitoring the employment situation in the US, where we observe weakening employment in higher value-added industries such as finance, professional services, and information technology. Therefore, we are wary of the short-term recovery in economic data. Our base case remains that the fundamental prospects remain brighter within Asia. While developed countries undergo a period of slowing growth, we believe that the effects are non-systemic and will not have a detrimental effect on the rest of the world.